Monday, November 16, 2026

Your Copy is on Hold (Claim it now)

Below is an important message from one of our highly valued sponsors. Please read it carefully as they have some special information to share with you.


Dear reader,

Your copy of Elon Musk’s Next Millionaire Maker is on hold.

Since you haven’t claimed it, we have NOT sent it to your inbox yet.

And I’d hate for you to miss this one.

Because it comes from James Altucher, arguably the #1 tech investor on the planet.

  • NVIDIA in 2008.
  • Bitcoin at $114.
  • SpaceX, years before a single share traded.

James called all three.

Now he believes he’s found Elon Musk’s Next Millionaire Maker.

One he estimates could create 1.8 million new millionaires in the coming years.

In his new report, James shows you how to position yourself in the company at the center of it for under $60.

Your copy is waiting.

But James won’t hold it forever.

Inside, you’ll get:

  • The name and ticker of the company at the center of Elon’s next millionaire maker industry takeover. A little-known stock that Elon has been trying to keep “SECRET” for years.

James will also show you:

  • The FCC filing Elon hoped nobody would find… and how James believes it exposes Elon’s plan to take over a $25 trillion industry.
  • Why December 8 could be your last chance to get in before Elon triggers the largest wealth creation event in history.

This is why I’m urgently trying to reach you.

You NEED to claim your copy now… before it’s too late.

Click here now to see how to claim your copy.

I don’t know how much longer we can hold it.

Regards,

Matt Insley
Publisher, Paradigm Press


This Month's Exclusive Story

Why Apple Stock Looks Like a Safe Haven After the Midterms

Authored by Sam Quirke. Date Posted: 11/11/2026.

The Apple Inc. logo mounted on the exterior glass facade of an Apple retail store.

Key Points

  • Apple's relatively restrained AI infrastructure spending could make it more resilient to a slowdown in data center construction.
  • Evercore ISI sees potential benefits for Apple if reduced AI infrastructure spending eases memory chip prices.
  • Rising memory costs, slowing Services growth, and a premium valuation remain risks despite the stock's resilience.
  • Special Report: Today's stock pick is on me tc pixel

For most of 2026, the main knock on Apple Inc. (NASDAQ: AAPL) was that it had become a bystander to the AI boom, watching rivals pour fortunes into chips and data centers while it kept its own AI infrastructure spending comparatively restrained. Increasingly, however, that caution is being seen as a strength.

While many tech stocks are still reeling from the market-wide sell-off on Nov. 5, Apple shares closed Nov. 10 roughly 2% below the intraday record high they set that day. For a company long written off as an AI also-ran, suddenly being seen as the steady one while the wider AI trade starts to crack is an unfamiliar role.

What if your familiar watchlist leaves too much out? (Ad)

The vote is over. Is your watchlist too familiar? Explore seven hidden-gem stock ideas beyond your usual tickers. Read our free report, then examine each business and its risks before deciding what deserves a closer look.

Let me see the reporttc pixel

The irony is that the AI-related sell-off followed the U.S. midterm elections on Nov. 3, yet those very results have some of Apple’s most optimistic bulls calling for further gains.

Is Apple the Best Stock to Own After the Midterms?

The biggest call came from Evercore ISI analyst Amit Daryanani, who reiterated his bullish view of Apple after the Democratic sweep of Congress. He called Apple “THE name to keep working when investors want to get defensive,” and his case rests on two very different ideas.

Unlike the hyperscalers and chipmakers pouring billions into data centers, Apple’s earnings engine runs on iPhone pricing, product mix and its Services arm—not on a breakneck buildout of AI infrastructure. If a Democratic Congress makes that buildout slower or more costly, Apple has far less riding on it than most of its peers.

That relative insulation is at the heart of the case. Apple could still ride the AI wave through device upgrades, ecosystem lock-in and potentially paid software features, effectively monetizing its enormous installed base without having to match the AI infrastructure spending of its largest rivals.

The Memory-Cost Twist That Could Help Apple

The other side of Daryanani’s thesis might seem counterintuitive, but it makes sense. It’s well known by now that surging memory prices have weighed on Apple throughout 2026, with the company again warning in its latest earnings report that they were likely to continue hurting its gross margins.

Daryanani’s wager is that a slower AI buildout, thanks to the so-called “Blue Wave,” could actually ease that pressure. His thinking is that if data center projects are delayed or blocked, the insatiable demand they create for memory chips could cool. Companies hurt by the resulting memory price inflation, with Apple chief among them, could see their costs drift back down. In other words, the same gridlock weighing on AI stocks might quietly give Apple a margin tailwind.

To be sure, this is a slow-burn benefit rather than an immediate one. Apple has locked in some supply and may have to wait several quarters before cheaper chips show up in its margins, and industry forecasts suggest memory prices could stay elevated through much of 2027. But it’s another reason to be more bullish than bearish on Apple after the midterms.

Valuation, China and a Margin Squeeze Still Loom

None of this makes Apple bulletproof. Management expects December-quarter gross margins of 45% to 46%, with memory costs, supply constraints and heavy purchase commitments set to continue weighing on margins for a while before any relief arrives.

There are softer spots, too. Apple’s Services growth has been cooling, its prospects in Greater China still carry a nagging question mark despite recent sales growth, and the stock’s valuation leaves little room for error. A Democratic sweep also raises the prospect of tougher congressional scrutiny of big tech, something Apple is no stranger to.

So Is Apple Really the Place to Hide?

For now, the case for Apple as an ideal defensive play is strong in theory but a little shakier at its current price. The company is well positioned to grow AI-related revenue through its devices and Services without having to bet the house on data center construction, and a cooling buildout could eventually give it a welcome margin reprieve.

The snag is that there may be more short-term pain before that reprieve arrives. If the wider tech landscape continues to sell off, it will be hard for Apple to stay near its highs at its current valuation.

The split across analysts on Wall Street sums it up. November has already seen Sanford Bernstein lift its price target to $380, matching Evercore’s, but there have also been downgrades from the likes of Phillip Securities and DZ Bank. As a hiding place, Apple might make far more sense than most of its peers right now, but as a bargain, it’s asking investors to pay a hefty price for that peace of mind.


This Month's Exclusive Story

The Trade Desk Beats on Revenue, But the Fine Print Matters

Authored by Chris Markoch. Date Posted: 11/11/2026.
The Trade Desk logo surrounded by digital screens, TVs, and devices connected by glowing blue data streams.

Key Points

  • The Trade Desk beat third-quarter revenue estimates, but sales declined slightly year over year.
  • The company's operating profit and adjusted EBITDA fell, although cash generation remained positive.
  • The Trade Desk's stock rallied following earnings, but investors may need evidence of renewed growth before the recovery can be sustained.
  • Special Report: Ron Paul: "Sorry Socialists, more handouts won't fix this" tc pixel

The Trade Desk (NASDAQ: TTD) broke out to a three-month high after delivering a better-than-feared earnings report following the market close on Nov. 9. The report comes with several asterisks, however, that may mean this isn't a clear buy signal for TTD.

On the other hand, the results lend credence to the idea that the pre-earnings rally wasn't entirely misplaced. Still, the stock's rise on heavy trading volume suggests that investors may have already priced in much of the expected growth.

Top Trader Reveals Stunning Black Friday Deal (Ad)

Others paid $500 for the Snapback Indicator. This Black Friday, it's available for just $7.

Base Camp Trading's Thomas Wood calls it one of the firm's most powerful proprietary trading indicators, and says the company has never run a deal like this before.

There are no strings attached, just a steep Black Friday discount on a tool built for traders.

Get the Snapback Indicator for just $7 in the Black Friday sale today.tc pixel

Investors are now weighing a headline beat against falling profits, a restructuring charge, and a stock still in a long-term downtrend.

A Revenue Beat With a Big Asterisk

In its Q3 2026 earnings report, The Trade Desk delivered revenue of $735.97 million, beating the consensus expectation of $650.93 million. Political advertising helped boost the number and is also expected to support results in the fourth quarter. Management also disclosed a nonrecurring benefit from a strategic partner that added approximately three percentage points to Q3 revenue growth.

That said, revenue was lower than in the same quarter of 2025, when the company delivered revenue of $739.43 million. Looking ahead, the company forecasts Q4 revenue of at least $755 million. That would represent sequential growth, although the guidance is below last year's $846.79 million.

The year-to-date picture is slightly better, although growth remains well below last year's pace. Revenue for the first nine months of 2026 rose 4.4% to $2.14 billion. Still, that’s a sharp slowdown. The company grew revenue 20% in the first nine months of 2025 and typically grew much faster from 2016 through 2024.

Profitability Moves in the Wrong Direction

The bigger concern lies below the top line. Total operating expenses climbed 11% to $643.4 million. Platform operations costs jumped 23% to $200.2 million. With revenue nearly flat, income from operations fell 43% to $92.6 million.

Part of that decline came from $44.3 million in restructuring charges, primarily severance costs tied to the company’s 2026 Restructuring Plan. Management excludes these charges from adjusted figures, but they’re a reminder that the company is resizing for slower growth.

Margins compressed even on an adjusted basis. Adjusted EBITDA fell to $265.8 million from $317.5 million. That puts the adjusted EBITDA margin near 36%, down from about 43% a year ago.

Taxes added another hit. The company recorded a $68.4 million tax provision on $106.5 million of pretax income, an effective rate of roughly 64%. GAAP earnings fell to eight cents per share from 23 cents. Non-GAAP earnings came in at 33 cents, down from 45 cents.

Cash Flow and Buybacks Offer Some Support

There were bright spots. Operating cash flow grew 15% to $258.3 million. Free cash flow was essentially flat at $153.3 million, as capital spending rose to $100.8 million from $66.3 million.

The share count is also shrinking. Weighted-average diluted shares fell to 470.2 million from 493.0 million, a drop of about 4.6%. Stock-based compensation declined 22% to $95.1 million, partly due to smaller CEO performance grants. Less dilution means each share represents a larger ownership stake in the company. The board also increased its share repurchase authorization by $731 million, bringing the total available for future buybacks to $1 billion.

The Business Model Is the Bull Case

The long-term bull case rests on a simple distinction. Alphabet (NASDAQ: GOOGL), Meta Platforms (NASDAQ: META), and Amazon.com (NASDAQ: AMZN) operate walled gardens. Each owns its ad inventory, its user data, and the tools used to buy ads. In effect, they sell the space and then grade their own results.

The Trade Desk works only for buyers. It doesn’t own media, so it has no incentive to steer advertisers toward its own inventory. The company pitches itself as a neutral partner for brands that want to protect their first-party data.

That neutrality shows up in its products.

  • Unified ID 2.0 is an open-source identity standard that other platforms can adopt.

  • OpenPath gives buyers a direct line to publishers.

  • OpenSincera offers free ad-quality metrics to the whole industry. Separately, the company's retail data marketplace covers over 80% of sales from top U.S. retailers, a pool that doesn’t include Amazon.

The opportunity is large. Using Magna's 2025 global advertising forecast and its own estimates, The Trade Desk puts open-internet ad spending at roughly $280 billion, more than either social media or search individually. The catch is that walled gardens offer convenience and scale. Nearly flat revenue suggests the open-internet pitch is harder to sell when budgets tighten.

TTD Stock Has Upside, But Growth Must Catch Up

The breakout is constructive, but investors should be careful not to trust it blindly. TTD still trades roughly 20% below its 200-day simple moving average, which is near $19.30. That average is still sloping lower.

The MACD has crossed above both its signal line and the zero line, indicating bullish momentum. However, the early-August gap down from near $19 creates overhead resistance. A sustained move through that zone would be more convincing than a single high-volume session.
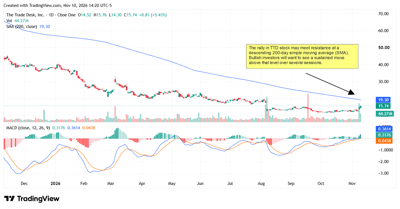
The Trade Desk (TTD) stock chart shows shares rallying with bullish MACD momentum toward resistance at the declining 200-day moving average.

The Trade Desk Rally Faces a 2027 Growth Test

The Trade Desk’s Q3 report was better than feared. But better than feared isn’t the same as better.

Revenue is nearly flat, margins are shrinking, and political ads are flattering near-term results.

With all that said, analyst forecasts for The Trade Desk on MarketBeat show a consensus price target of about $18.50 for TTD.

That suggests upside of roughly 20% from recent prices.

However, at least four analysts have raised their price targets since the report, but none are above the consensus target.

That fits the overall sentiment.

Investors may want proof that non-political revenue can grow in 2027 before treating this rally as a turning point.

Thank you for subscribing to Insider Trades Daily, which covers the most recent insider buying and selling activity from Wall Street CEOs, CFOs, COOs and other insiders.
 
This email communication is a paid sponsorship from Paradigm Press, a third-party advertiser of InsiderTrades.com and MarketBeat.
 
If you have questions or concerns about your subscription, feel free to contact our support team, based in the United States, at contact@marketbeat.com.
 
If you no longer wish to receive email from InsiderTrades.com, you can unsubscribe.
 
© 2006-2026 MarketBeat Media, LLC. All rights reserved.
345 North Reid Place #620, Sioux Falls, SD 57103. United States of America..
 
Further Reading: Boring, cheap, and paying 6% (Click to Opt-In)tc pixel

Your account is now eligible

Hi there,

Your account is eligible for a full month of MarketBeat All Access for $1.

Why a dollar? Because talk is cheap and seeing is believing. A month of using our tools on your own portfolio will tell you more than anything I could put in an email.

Offer ends in: countdown to midnight

Here is what you get to try:

  • Real-time alerts when an analyst upgrades, an insider buys or a company beats earnings on a stock you follow.
  • Analyst ratings with track records, so you can tell which calls are worth acting on.
  • Screeners, the weekly Idea Engine and every premium report, in one place instead of a dozen browser tabs.

Start your month of All Access →

Even people who manage money for a living rely on it. "It is one of my 'must have' resources that I depend on as we navigate the markets," writes Tom S. Take a look for yourself.

If you stay, your first year is $199, or $19.99 a month if you would rather pay monthly. If it is not for you, cancel online before your month is up and you will not be charged again.

Matthew Paulson
Founder and CEO, MarketBeat

P.S. The timer above runs out at midnight Central. Claim 1 Month of MarketBeat All Access for $1.


Bonus Article from MarketBeat Media

Firefly Aerospace Lights Up a High-Risk Space Opportunity

Authored by Thomas Hughes. Date Posted: 11/13/2026.

Firefly Aerospace logo beside a rocket on a launch tower at sunset, with a hangar facility in the background.

Key Points

  • Firefly Aerospace's backlog, contract wins, and a landmark $1.3 billion AST SpaceMobile deal position it to quickly close the gap with larger rival Rocket Lab.
  • Improved guidance, a Lockheed Martin launch agreement extension, and five concurrent lunar missions underscore accelerating momentum despite swelling adjusted losses.
  • Shareholder dilution, government contract concentration, and recurring Alpha launch delays remain significant risks clouding Firefly's path to profitability.
  • Special Report: Today's stock pick is on me tc pixel

Firefly Aerospace (NASDAQ: FLY) is still a small company, but it represents an aggressive opportunity in space development. While Q3 revenue came in at less than half of what Rocket Lab (NASDAQ: RKLB) reported for the same period, Firefly’s backlog, contract wins and expansion plans position it to catch up quickly. For investors, the opportunity is to enter the market while shares remain well below their earlier highs. Firefly is growing at a rapid pace, although the timeline for profitability remains uncertain.

Q3 results reflect a company executing its strategy and attracting strong demand. Highlights include a landmark deal with AST SpaceMobile (NASDAQ: ASTS) to provide hardware, intellectual property (IP) and support services. Valued at about $1.3 billion, the deal includes about $800 million for a license to manufacture Miranda and Vira engines, with the remainder covering engine deliveries and engineering services. The agreement validates Firefly’s technology and adds to its growth prospects. Its existing backlog represents nearly four years of activity at the Q3 pace, even before accounting for the AST agreement. The deal could also reduce launch risks for AST SpaceMobile.

Firefly Aerospace Builds Momentum With Q3 Results

What if your familiar watchlist leaves too much out? (Ad)

The vote is over. Is your watchlist too familiar? Explore seven hidden-gem stock ideas beyond your usual tickers. Read our free report, then examine each business and its risks before deciding what deserves a closer look.

Let me see the reporttc pixel

Firefly Aerospace’s Q3 results showed accelerating momentum, with revenue up about 260% year over year, 7.3% above expectations, and guidance improving. Revenue was driven by numerous projects, while work on five lunar missions also improved visibility. Contract wins include an extension of a multiyear launch agreement with Lockheed Martin (NYSE: LMT), providing visibility into the early next decade.

Margin news was mixed, with adjusted losses swelling as the company invested in strategic execution. This work included expanding a cleanroom facility, which now enables the simultaneous manufacture of up to 12 lunar landers and orbital vehicles. Despite the heavy spending, the adjusted loss per share came in five cents better than consensus.

Guidance is a catalyst. The improved outlook compounded quarterly strength and backlog growth, coming in ahead of consensus and forecasting approximately 24% sequential growth, though it remains cautious. While launch delays are weighing on the outlook, strength in other segments, including defense software, provides an offset. The five parallel lunar missions also provide a solid baseline and lay the groundwork for upside surprises.

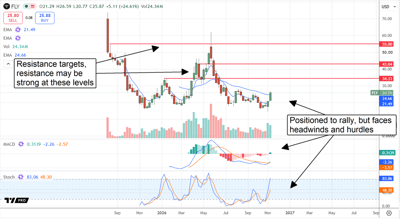
FLY stock chart shows a sharp rally on rising volume, with bullish momentum strengthening despite overhead resistance.

Analysts Lift Targets, Reinforcing Upside Potential for Firefly Investors

Analysts’ responses highlight the strength of Firefly’s quarter, with several firms raising their price targets after the report. Commentary focused on the earnings beat, backlog and guidance, as well as the validating AST SpaceMobile deal. The target range is wide, but Firefly has a Moderate Buy consensus rating and an average price target of $35.75, suggesting about 50% upside from recent trading levels. The expectation now is that Firefly will continue executing its strategy and sustain its bullish revision cycle.

Price action was bullish following the release, with shares rising by more than 10% and suggesting a potential market bottom. Whether this is the absolute bottom remains to be seen. Near-term signals point to upside potential, but technical hurdles remain. Prior highs near $35, along with a congestion band in the $35 to $45 region, may provide enough resistance to cap gains.

There Are Plenty of Risks and Headwinds for Firefly Shareholders

Risks include, but are not limited to, shareholder dilution. Q3 highlights show a well-capitalized company with limited debt and steady equity, but cash is down year to date despite a dilutive capital raise, and the cash burn continues. Cash could keep dwindling, increasing dilution risk until the company reaches profitability. Based on Q3 figures, additional financing remains a risk before that transition. News of capital-raising activity could create selling pressure.

Other risks center on concentration and execution. Firefly Aerospace’s outlook is rapidly improving, but its existing revenue and backlog are tied to a few government entities, while the new AST SpaceMobile agreement introduces additional execution risks. Government contracts are exposed to budget shifts and changes in administration, while ASTS is an equally speculative bet on space-based 5G services with no guarantee of success. The Alpha launch system has experienced several setbacks and delays, with the next launch not slated until early 2027. Governance is also a risk, with a large shareholder retaining significant influence over the company.

In short, bulls may be underestimating the time it will take Firefly to scale. Project delays, costs and widening adjusted losses weigh on the outlook and make the existing timeline uncertain at best. Bears may be wrong to treat Firefly as a pure launch company, since its primary revenue source and growth drivers are spacecraft solutions, including vehicles and defense software. While launch matters, the five concurrent lunar missions and the vehicles they require are the bigger story. In addition, acquiring SciTec gives Firefly a foothold in the defense software industry.


Bonus Article from MarketBeat Media

Alphabet Escalates AI Chip Rivalry With NVIDIA

Authored by Ryan Hasson. Date Posted: 11/11/2026.

Google logo displayed on a computer processor chip surrounded by illuminated circuit board pathways.

Key Points

  • Alphabet unveiled two new specialized TPU systems, the TPU 8tx and TPU 8i Max, challenging NVIDIA while shares remain well below their 52-week high.
  • The launch bolsters Alphabet's case that heavy capital spending is building a vertically integrated AI hardware business rather than simply adding costs.
  • Despite the TPU news, the announcement does little to resolve concerns about slowing Search query monetization, which remains the central worry for investors.
  • Special Report: Ron Paul: "Sorry Socialists, more handouts won't fix this" tc pixel

Alphabet (NASDAQ: GOOGL) has had a difficult few weeks. As MarketBeat reported, shares slid 12.6% in the Oct. 29 session after the company’s third-quarter report, as slowing Search growth and rising capital spending overshadowed an otherwise strong quarter.

The Nov. 5 sell-off in AI and chip stocks added to the pressure.

This is likely to EXPLODE (Ad)

Dr. Martin D. Weiss, founder of Weiss Ratings and a two-time Congressional witness on financial institution risk, is warning of a looming $3 trillion threat in today's financial system.

He says the same ratings agency practices that preceded the 2008 crisis are repeating themselves, while regulators stay quiet about the risks.

Watch Dr Weiss's free video to learn how to protect your moneytc pixel

Then, on Monday, Nov. 9, Alphabet gave investors something different to consider when it unveiled two specialized Tensor Processing Unit (TPU) systems, the TPU 8tx and TPU 8i Max, further challenging NVIDIA (NASDAQ: NVDA). Shares closed slightly higher after the announcement, though the stock remains about 30% below its 52-week high of $408.61.

The launch strengthens Alphabet’s position as one of the few AI spenders that can also sell its own hardware. Whether that’s enough to offset lingering concerns about Search and spending is a more complicated question.

Two Chips Built for Very Specific Jobs

The two systems join the TPU 8t and TPU 8i that Alphabet’s Google introduced in April, making 2026 the first year the company has rolled out four TPU systems. Both are specialized configurations built around existing eighth-generation chips and are expected to become available next year.

The TPU 8tx is aimed at confidential computing. Paired with an Advanced Micro Devices (NASDAQ: AMD) EPYC processor, it is designed for government agencies and companies in regulated industries such as finance and healthcare.

The TPU 8i Max combines two TPU 8i chips in a single package, doubling compute capacity and memory bandwidth. It is built for long-context AI applications that need to process far more information per request.

Google cited drug discovery, math and coding as key use cases, adding, “Our aim is to make TPUs more easily accessible to every developer and Cloud customer.”

A Stronger Answer to the Spending Question Than the Search One

The launch arguably does more to ease spending concerns than worries about Search. Alphabet’s capital expenditures reached $51.4 billion in the third quarter, exceeding the $42.3 billion in operating cash flow it generated over the same period.

TPUs change the conversation because Google can deploy its proprietary hardware in its own cloud infrastructure or sell complete systems to customers, rather than relying solely on outside suppliers.

Google Cloud brought in $30.7 billion in revenue in the third quarter, roughly double the $15.2 billion it generated a year earlier, with demand for TPU systems a key contributor. Google has also said it builds TPU-system inventory only after securing customer contracts.

The announcement does little to address Search, however. The central question hanging over Alphabet’s legacy business is the gap between query growth, which is at a five-year high, and the slower ad monetization of AI Mode.

Sizing the Opportunity Against NVIDIA

NVIDIA still operates on a far larger scale, generating $89 billion in data center revenue in its fiscal 2027 second quarter alone.

Alphabet does not disclose separate TPU revenue or profit figures, making a direct comparison difficult. Still, Google’s ability to design and sell complete AI systems gives it another way to generate revenue from its infrastructure investments.

From AI Labs to Trading Firms

Alphabet said on its third-quarter call that it now has more than 100 significant TPU customers. Anthropic stands out, with arrangements to obtain additional TPU compute from Google or third-party providers. According to a regulatory filing, these arrangements could involve $125 billion to $150 billion in future payments for capacity delivered from 2028 through 2031.

Apple (NASDAQ: AAPL) and Jump Trading are also customers, while Meta Platforms (NASDAQ: META) has collaborated with Google on software that supports TPUs. Oracle (NYSE: ORCL) plans to offer TPUs through Oracle Cloud Infrastructure in 2027, marking the first time the chips will be available on another major cloud platform. Potential new buyers include the government agencies, banks and healthcare providers the 8tx is designed for.

Enough to Quiet the Doubters?

The new systems alone are unlikely to settle those fears entirely.

However, they give bulls a stronger case that Alphabet’s heavy spending is building a vertically integrated AI business rather than simply adding costs.

Skeptics might point out that NVIDIA is still far larger, that OpenAI and Anthropic are both developing their own chips, and that the Search monetization gap remains unresolved.

The coming months should offer clearer answers. Management has said it expects TPU system sales to scale in the fourth quarter, ahead of a meaningful revenue ramp in 2027, when Oracle’s TPU offering is also expected to become available.

If TPU system sales continue to grow while Search monetization improves, the case that shares have been unfairly punished will become considerably stronger.

Thank you for subscribing to The Early Bird, MarketBeat's 7:00 AM newsletter that covers stories that will impact the stock market each day.
 
If you have questions about your subscription, please email MarketBeat's support team, based in the United States, at contact@marketbeat.com.
 
If you no longer wish to receive email from The Early Bird, you can unsubscribe.
 
© 2006-2026 MarketBeat Media, LLC. All rights protected.
345 N Reid Place #620, Sioux Falls, SD 57103-7078. United States..
 
Further Reading: Boring, cheap, and paying 6% (Click to Opt-In)tc pixel

You don't NEED motivation to run

+ Why is a marathon, a marathon?  ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏­­­­­­­­­­­­­­­­­­­­­­­­­­­­­­­­­­­­­­­­

Page List

Blog Archive

Search This Blog