Sunday, November 1, 2026

Why December 11 Could Reshape a 46 Billion Pentagon Program

$46 Billion Is Waiting on December 11

The Pentagon wants $46 billion for a "sovereign AI Arsenal." Bigger than Golden Dome.

A stopgap law has frozen every dollar of it until December 11.

The Arsenal runs on Elon's AI. And Elon's AI hinges on one tiny company he couldn't build around.

Get positioned before December 11 here >>


Further Reading from MarketBeat.com

ServiceNow Orchestrates AI's Next Act—Can Earnings Deliver?

Authored by Jeffrey Neal Johnson. Publication Date: 10/21/2026.
ServiceNow logo surrounded by glowing icons representing cloud computing, security, support, and analytics in an office setting.

Key Points

  • ServiceNow is attracting renewed analyst optimism as investors look toward enterprise software for AI monetization.
  • ServiceNow's new EmployeeWorks capabilities and AI Passport aim to expand automation while improving enterprise AI governance.
  • ServiceNow's upcoming third-quarter earnings will test whether its growth and AI adoption justify its premium valuation.
  • Special Report: One Company Spared After Renewable Credits Get Cut.

Investors scanning the market for sustainable monetization of generative artificial intelligence (AI) are noticing a distinct shift. The initial wave of capital that flooded into semiconductor manufacturers and hardware infrastructure is beginning to rotate.

Investors are increasingly looking for software providers that can turn raw computing power into measurable business efficiency.

Nvidia's Huang doubts Musk's latest mega plan can work (Ad)

Nvidia CEO Jensen Huang says Elon Musk's $119 billion plan will be extremely hard to pull off.

Larry Benedict, who ran a $900 million hedge fund and posted 20 consecutive years without a loss, including over $274 million in audited net income between 2004 and 2012, says one long forgotten American company already holds what Musk needs.

Get the ticker and his full analysis before the November 30 deadline.

Click here to get the free ticker before November 30tc pixel

By identifying businesses that are successfully embedding AI into daily corporate operations, investors can position themselves ahead of the next major valuation expansion.

ServiceNow Inc. (NYSE: NOW) appears uniquely positioned to capture this transition.

With Wall Street analysts issuing new price targets ahead of upcoming earnings, understanding how workflow-orchestration layers capture durable AI margins offers a strategic advantage.

Investors Pivot to High-Retention AI Software

Recent market activity suggests growing investor interest in high-retention enterprise software as an alternative to volatile AI hardware equities. After early investments in base-layer models and semiconductor foundries, institutional capital is showing renewed interest in the application layer. This approach may offer a different risk profile during broader sell-offs in the technology sector while maintaining exposure to the secular AI growth thesis.

ServiceNow benefits directly from this rotation. The company operates as a central nervous system for enterprise IT, human resources and customer service departments. Because these workflow systems are deeply embedded in daily operations, replacing them requires significant capital, extensive employee retraining and potentially substantial operational downtime.

This creates a wide economic moat and exceptionally high switching costs, allowing ServiceNow to exercise pricing power when rolling out new premium features. In the software-as-a-service business model, this level of customer retention provides a highly predictable revenue floor. That predictable foundation frees up cash flow for aggressive research and development investment, allowing ServiceNow to maintain a long-term technological edge over legacy competitors.

Orchestrating Cash Flow With Zero-Code AI

The fundamental driver behind the recent bullish sentiment is ServiceNow's ability to monetize automated AI-agent workflows across client software suites. As foundational-model hype gives way to immediate software deployment, the workflow-orchestration layer presents an opportunity to capture durable margins in generative AI.

The recent rollout of new EmployeeWorks capabilities, powered by a third-generation, employee-centric AI harness, illustrates this strategy. The platform allows employees to build AI agents without writing code, effectively democratizing automation across an entire organization. Paired with AI Passport, which ServiceNow is developing alongside NVIDIA (NASDAQ: NVDA), the company aims to govern agent permissions and preserve business context. These capabilities provide the technological foundation needed to move AI from a conceptual tool to a verified enterprise deployment. The new EmployeeWorks capabilities are in controlled availability, while ServiceNow expects AI Passport to become available in the fourth quarter of 2026.

By removing the coding barrier and ensuring strict governance over data access, ServiceNow could accelerate enterprise adoption and create high-margin upsell opportunities within its existing customer base. These higher-tier product upgrades could flow to the bottom line, improving operating leverage as deployment scales across global enterprises.

Momentum Building Ahead of Third-Quarter Earnings

Financial performance supports the narrative of elite enterprise AI monetization. In its most recent quarter, ServiceNow delivered revenue of about $3.99 billion, representing approximately 24% year-over-year growth and comfortably beating consensus estimates. This top-line momentum highlights strong enterprise demand and reinforces the company's dominant market share in workflow automation.

Anticipation is building ahead of the third-quarter earnings report, expected on Wednesday, Oct. 28. ServiceNow holds a Moderate Buy consensus rating, and analysts are actively pricing in the potential impact of AI-tier upselling on overall profitability.

Bernstein analyst Peter Weed recently issued a Street-high price target of $266, up from $248, while maintaining an Outperform rating. The aggressive upgrade came ahead of the earnings cycle, signaling institutional confidence in an impending beat-and-raise quarter driven by growing adoption of higher-priced, AI-native products.

Other investment desks share this optimism, with Piper Sandler raising its target to $175 and TD Cowen lifting its target to $165. Both firms cited demand from U.S. federal agencies and sustained customer upgrades. When multiple research desks lift targets within a short period, it often signals growing confidence that large enterprise clients will continue investing in the ServiceNow ecosystem.

Measuring SaaS Multiples Against Growth Rates

While the growth trajectory remains robust, pragmatic investors must weigh the premium valuation against underlying balance-sheet metrics. ServiceNow's stock trades at a trailing price-to-earnings (P/E) ratio near 93 and a forward P/E of roughly 67. While these multiples appear elevated at face value, they represent a compression from ServiceNow's historical premium, which frequently remained between 50 and 100 times forward earnings over the last decade. The current multiple offers a slightly less risky entry point relative to past peaks, particularly given the company's current 24% revenue growth rate.

Internal and external metrics present some headwinds that require monitoring. Short interest increased roughly 3% month over month, reaching about 29.6 million shares. This larger short position highlights a measurable group of investors positioning against further multiple expansion in the near term. Late-August regulatory filings also revealed executive share sales, with corporate insiders liquidating portions of their holdings.

Liquidity measures warrant attention as well. ServiceNow operates with current and quick ratios near 0.7, indicating that current short-term liabilities exceed current assets. Software-as-a-service companies frequently operate with lower current ratios because annual subscription payments are recorded as deferred-revenue liabilities until the service is delivered.

However, a sub-1.0 ratio still demands close monitoring of cash flow generation. Counterbalancing these friction points is ServiceNow's underlying profitability, highlighted by an approximate 11% net margin and a 16% return on equity. With nearly $13.28 billion in annual sales, the core business remains cash-generative despite the optical balance-sheet constraints.

Positioning Portfolios for the Software Shift

As investors look beyond volatile AI hardware toward high-retention software, the workflow-orchestration layer offers an opportunity for durable AI monetization. Recent analyst target increases, capped by the Street-high $266 price target, suggest that AI-native upgrades could drive substantial margin expansion.

Fundamental metrics support the narrative of strong enterprise monetization, provided the premium valuation remains justified by earnings beats and seamless product integration. Investors assessing exposure to enterprise software may want to add ServiceNow to their watchlists and monitor customer growth and margin expansion as the third-quarter earnings date approaches.


Exclusive Content from MarketBeat

SpaceX Earnings Launch: High Margins Fund AI Ambitions

Written by Jeffrey Neal Johnson. Originally Published: 10/21/2026.
SpaceX logo overlaid on a photo of a rocket on the launch tower at sunset.

Key Points

  • SpaceX posted third-quarter earnings of 35 cents per share, far exceeding the 10-cent consensus estimate, as total revenue rose about 161% year over year to $14.58 billion.
  • The new Super Intelligence AI segment generated $7.56 billion in quarterly revenue, while management guided for $35 billion to $40 billion in fourth-quarter capital expenditures.
  • SpaceX holds a $63 billion backlog and over $75 billion in IPO proceeds, supporting guidance for $33 billion to $37 billion in first-quarter 2027 revenue.
  • Special Report: One Company Spared After Renewable Credits Get Cut.

SpaceX (NASDAQ: SPCX) gave Wall Street just four days' notice before releasing its third-quarter earnings, catching investors off guard with an unusually short announcement window. The aerospace giant then delivered another surprise: Earnings of 35 cents per share easily beat the 10-cent consensus estimate, while quarterly revenue surged 161% year over year to $14.58 billion.

What makes this earnings report compelling is how SpaceX is financing its pivot into artificial intelligence (AI). The Super Intelligence segment generated more than $7.5 billion in revenue, demonstrating that newly deployed compute capacity and AI products are already producing substantial revenue. Management also guided for approximately $35 billion to $40 billion in companywide capital expenditures during the fourth quarter.

Igniting the Bottom Line: Profitability Meets Expansion

Nvidia's Huang doubts Musk's latest mega plan can work (Ad)

Nvidia CEO Jensen Huang says Elon Musk's $119 billion plan will be extremely hard to pull off.

Larry Benedict, who ran a $900 million hedge fund and posted 20 consecutive years without a loss, including over $274 million in audited net income between 2004 and 2012, says one long forgotten American company already holds what Musk needs.

Get the ticker and his full analysis before the November 30 deadline.

Click here to get the free ticker before November 30tc pixel

Achieving profitability during an aggressive infrastructure expansion is a rare feat. SpaceX reported approximately $14.58 billion in total revenue, up roughly 161% year over year. The standout driver was the Super Intelligence unit, which generated around $7.56 billion during the quarter. That figure represents a substantial increase from the roughly $2.56 billion reported in the second quarter. The rapid commercialization of compute capacity, which reached approximately 1.7 gigawatts by the end of September, suggests that cloud service contracts are absorbing the new supply.

The quarter also included the integration of Cursor following an acquisition that carried an implied equity value of approximately $60 billion. Cursor contributed roughly $608 million to the top line while adding about $1.22 billion in acquisition-related share-based compensation. Combined with approximately $675 million in interest expense, the company's ability to post positive net income highlights a durable operating model. High-margin segments are effectively absorbing the costs of rapid expansion, allowing SpaceX to demonstrate bottom-line resilience as the aerospace leader scales new business units.

Escape Velocity: Revenue Outpaces Infrastructure Spend

A critical metric for evaluating high-growth infrastructure plays is the relationship between capital expenditures and revenue generation. In the second quarter, SpaceX spent roughly $18.37 billion on capital expenditures against about $7.81 billion in revenue, resulting in a ratio of nearly 2.35x. In the third quarter, capital expenditures increased to roughly $19.59 billion, but revenue of $14.58 billion compressed that ratio to approximately 1.34x.

This sequential compression suggests that SpaceX's overall revenue is growing faster than its capital spending. AI revenue is scaling rapidly, although the companywide figures do not isolate the costs of building its data centers. Management expects fourth-quarter capital expenditures to accelerate to $35 billion to $40 billion as SpaceX deploys V3 satellites, scales Starship development and expands its compute footprint.

Under normal circumstances, a $40 billion quarterly capital outlay might trigger concerns about debt service and balance-sheet strain. The recent initial public offering fundamentally altered SpaceX's liquidity profile. The IPO generated approximately $85.7 billion in net proceeds, and SpaceX ended September with $51.3 billion in cash and cash equivalents, along with another $38.6 billion in marketable securities. This liquidity allows SpaceX to fund its fourth-quarter ambitions without immediately stressing debt markets or accepting unfavorable financing terms.

The Heavy Lift Booster: Starlink Subsidizes AI Growth

While compute infrastructure commands the headlines, the legacy space and connectivity segments are the financial bedrock supporting these endeavors. The connectivity segment, driven by Starlink, delivered approximately $5.25 billion in revenue and operates at an estimated 55% gross margin.

The consumer broadband base expanded to approximately 13.6 million subscribers, while enterprise and government revenue jumped 91% year over year.

Aviation contracts are also scaling, with thousands of aircraft currently equipped with satellite terminals. These high-margin, recurring revenues provide the operating cash flow necessary to subsidize the capital-intensive Super Intelligence buildout. SpaceX is essentially using its dominance in low Earth orbit to help fund its terrestrial data center ambitions.

Management is also laying the groundwork for an expanded total addressable market. A recent agreement to acquire a portfolio of 800 MHz spectrum licenses positions Starlink Mobile to operate directly as a primary U.S. mobile carrier, although the deal still requires regulatory approval and additional infrastructure investment.

Transitioning from a fixed broadband and aviation provider into the broader telecommunications market could unlock entirely new revenue streams. By establishing a direct-to-device network, SpaceX would create a potential pipeline of recurring revenue to support the cash flow needed in the coming years.

Plotting the Course: Forward Visibility Remains Strong

Looking beyond the immediate capital expenditure cycle requires visibility into future cash flows. SpaceX reported a total backlog of approximately $63 billion, with roughly $42 billion expected to be recognized over the next 12 months.

This contracted revenue provides a high degree of predictability for the coming quarters, helping reduce uncertainty surrounding the anticipated spending. For fundamental analysts, a backlog of this magnitude signals that enterprise demand is not merely theoretical but firmly committed.

Management leveraged this visibility to issue aggressive forward guidance, projecting first-quarter 2027 revenue of between $33 billion and $37 billion. This forecast directly challenges concerns that the AI compute market might face a near-term plateau.

If SpaceX reaches these targets, it would provide further evidence that enterprise demand for inference and training compute remains robust, validating the heavy, front-loaded investments and easing concerns about long-term payback periods.

Mission Control: SpaceX’s Next Phase of Growth

The third-quarter earnings report presents a clear picture of an enterprise successfully navigating a complex growth phase. On one side, improving profitability and a rapidly expanding total addressable market are driving record revenue.

On the other side, the sheer scale of the required capital expenditures demands flawless execution. The compression in the capital expenditure-to-revenue ratio offers a strong signal that the underlying strategy is working as intended.

Investors evaluating the aerospace and telecommunications sectors may view the recent earnings report as confirmation of SpaceX's operating leverage. Those monitoring SpaceX might prefer to watch how effectively the fourth-quarter capital deployment translates into the projected 2027 revenue targets before adjusting their allocations. The foundational elements are in place, but executing a $40 billion infrastructure deployment will be the ultimate test of operational discipline.


This message is a sponsored message for Behind the Markets, a third-party advertiser of MarketBeat. Why was I sent this email message?.
 
If you have questions or concerns about your account, please feel free to contact our support team, based in the United States, at contact@marketbeat.com.
 
If you would no longer like to receive promotional emails from MarketBeat advertisers, you can unsubscribe or manage your mailing preferences here.
 
Copyright 2006-2026 MarketBeat Media, LLC.
345 North Reid Place #620, Sioux Falls, S.D. 57103-7078. United States..
 
Read More: A weekly dividend fund holding Nvidia and Palantir 

अटलांटा में विदेश मंत्री मार्को रुबियो का संवाददाता सम्मेलन

Department of State United States of America

अनुवादअमेरिकी विदेश विभाग केसौजन्य से


अमेरिकी विदेश मंत्रालय
मार्को रुबियो, विदेश मंत्री
संवाददाता सम्मेलन
अक्टूबर 31, 2026
लोज़ अटलांटा
अटलांटा, जॉर्जिया

विदेश मंत्री रुबियो: धन्यवाद। यह थोड़ा अजीब सा है। मुझे लगता है आप लोग जानते हैं कि मैं कौन हूं। अगर आप नहीं जानते होते कि मैं कौन हूं, तो आप यहां नहीं होते। खैर, फिर भी आपका धन्यवाद। मैं अटलांटा शहर को धन्यवाद देना चाहता हूं। इस सप्ताह उन्होंने हमारी मेज़बानी बहुत अच्छे से की। यह अमेरिका के प्रमुख व्यापारिक और नवाचार केंद्रों में से एक है, और यह हमारे लिए एक आदर्श स्थान रहा है, न केवल अपने देश की उपलब्धियों को प्रदर्शित करने का, बल्कि आज दुनिया के सामने मौजूद महत्वपूर्ण आर्थिक नीतिगत मुद्दों पर ध्यान केंद्रित करने का भी। राष्ट्रपति ट्रंप के नेतृत्व में, अमेरिका ने जी20 के लिए एक स्पष्ट मिशन तय किया है कि वह अपनी मूल बातों पर वापस लौटे और उस मुख्य उद्देश्य पर ध्यान केंद्रित करे, जिसके लिए इस मंच का गठन किया गया था।

इसलिए, इस सप्ताह अटलांटा में, विदेश मंत्रियों के स्तर पर, हमने उसी निर्देश के अनुसार काम किया। हमने आर्थिक, ऊर्जा, प्रौद्योगिकी और आपूर्ति श्रृंखला (सप्लाई चेन) से जुड़ी मुख्य चुनौतियों पर ध्यान दिया। हमने ऐसे व्यावहारिक समाधानों और ठोस परिणामों पर चर्चा की, जिनसे न केवल यहां मौजूद देशों के नागरिकों को, बल्कि पूरी दुनिया के लोगों को लाभ हो सके। आज दुनिया में कई जटिल और परस्पर जुड़ी समस्याएं हैं, जिनका असर हम सभी देशों पर पड़ता है। इन समस्याओं का समाधान खोजने के लिए हमें मिलकर काम करना होगा। इसीलिए इस समूह को एक गंभीर और उद्देश्यपूर्ण बैठक के लिए एकजुट करना महत्वपूर्ण है, और मुझे यह कहते हुए खुशी हो रही है कि इस सप्ताह हमने कई मुद्दों पर विस्तार से चर्चा की है। हमने जिन भी विषयों पर चर्चा की है, वे सब आपको मेरे अध्यक्षीय वक्तव्य में मिल जाएंगे, जो जारी होने वाला है, अगर अभी तक जारी नहीं हुआ हो तो।

निश्चित रूप से, जिन मुख्य मुद्दों पर हमने चर्चा की, उनमें से एक था नौवहन की स्वतंत्रता। अंतरराष्ट्रीय जलक्षेत्र में जहाज़ों की सुरक्षित आवाजाही पूरी दुनिया की आजीविका के लिए अत्यंत महत्वपूर्ण है, और हम हमले होते देख रहे हैं – और असल में वे हमले ही हैं। मैं स्पष्ट कर दूं – और मैंने अपनी टिप्पणियों में भी इस बात को रेखांकित किया था; अब मैं आपके सामने भी इसे दोहरा रहा हूं। आज हम ऐसी दुनिया में जी रहे हैं जहां ईरानी शासन कमर्शियल जहाज़ों को – नौसैनिक जहाज़ों को नहीं – सक्रिय और खुले तौर पर हमलों का निशाना बनाता है; हम नौसैनिक जहाज़ों की बात नहीं कर रहे हैं, हम पनडुब्बियों की बात नहीं कर रहे हैं। हम उनकी इस मानसिकता की बात कर रहे हैं जहां वे कहते हैं: ये रहा माल, तेल या प्राकृतिक गैस से लदा कमर्शियल जहाज़, और हम इसे डुबोने की कोशिश करेंगे। वे कूटनीति के हथियार के रूप में जहाज़ों पर खुलेआम हमले कर रहे हैं। हम आज ऐसी ही दुनिया में रह रहे हैं। और मुझे लगता है कि सेंट्रल कमान और अमेरिका ने इन जहाज़ों की सुरक्षा के लिए बहुत ही बेहतरीन काम किया है।

और आज, वहां से गुज़रने वाले ईंधन की मात्रा लगभग उतनी ही है जितनी संघर्ष शुरू होने से पहले थी; लेकिन इसके बावजूद, हमें लगभग हर रात इन जहाज़ों को ड्रोन और मिसाइलों के हमलों से बचाना पड़ा है। अब हम न केवल होर्मुज़ जलडमरूमध्य में, बल्कि बाब अल-मंदेब में भी हमले देख रहे हैं। इसके अलावा, दक्षिण चीन सागर, ताइवान जलडमरूमध्य और अन्य जगहों पर भी हमें शत्रुतापूर्ण दबाव की कार्रवाई देखने को मिल रही है। हो सकता है कि ये सीधे तौर पर सैन्य हमले नहीं हों, लेकिन फिर भी चिंताजनक है, क्योंकि इनसे अर्थव्यवस्थाओं को भी ख़तरा पैदा होता है।

समुद्री मार्गों पर हमलों या दबाव के सबसे गंभीर परिणामों में से एक है खाद्य सुरक्षा से जुड़ी समस्याओं का बढ़ना। जब ऊर्जा, उर्वरक और कृषि उत्पाद अपने गंतव्यों तक नहीं पहुंच पाते, तो इससे हमारे प्रत्येक देश की और दुनिया के सभी देशों की सबसे बुनियादी ज़रूरतें खतरे में पड़ जाती हैं। मुझे खुशी है कि इस समूह ने इस विषय पर सार्थक बैठकें कीं और हम कम से कम अपने लक्ष्य को लेकर एकमत हैं और यह समझते हैं कि यह एक गंभीर समस्या है। हालांकि, मैं यह नहीं कह सकता कि इससे निपटने के तरीके को लेकर भी हमारे बीच सहमति है। विशिष्ट खनिजों को लेकर अपनी समापन टिप्पणियों में मैंने जो बात कही थी, वह इस मुद्दे पर भी लागू हो सकती है। हम सभी इस बात से सहमत हैं कि समस्या मौजूद है, लेकिन सामूहिक रूप से इसके समाधान पर सहमति बनाने के लिए अभी काम करना बाकी है।

मुझे इस बात की भी खुशी है कि जी20 बैठक के दौरान, एक बार फिर साथ लाने तथा अनेक विषयों और मुद्दों पर चर्चा करने में सफल रहे। हमने क्वाड में काफी समय लगाया है। मुझे लगता है कि सिर्फ इसी साल हम चार-पांच बार मिल चुके हैं। जनवरी 2025 में विदेश मंत्री का पद संभालने के बाद मेरी पहली बैठक क्वाड की ही थी। हम इस मंच के ज़रिए आगे भी काम करते रहेंगे, क्योंकि अब यह सिर्फ समस्याओं पर चर्चा करने का स्थान नहीं रह गया है, बल्कि एक ऐसा मंच बन गया है जहां हम मिलकर काम करने के क्षेत्र चुनते हैं और वास्तव में उन पर कदम भी उठाते हैं।

उम्मीद है कि हम जल्द ही घोषणा करेंगे – अगर पहले ही नहीं कर चुके हैं – कि अगले महीने – आज शायद 31 तारीख है – मनीला में क्वाड नेताओं की बैठक होगी। तो ये ऐसे मुद्दे हैं जो अमेरिका और आज यहां मौजूद सभी देशों के लिए बहुत महत्वपूर्ण हैं। क्वाड के सभी सदस्यों के साथ हमारे बहुत अच्छे संबंध हैं। हमारी साझेदारी हमें इन चुनौतियों से प्रभावी ढंग से और एकजुट होकर निपटने में सक्षम बनाती है, जिससे हमारे संबंधित देशों के साझा राष्ट्रीय हितों को लाभ होता है।

मेरी द्विपक्षीय बैठकें भी बहुत अच्छी रहीं। और, हमने जापान और दक्षिण कोरिया के साथ त्रिपक्षीय बैठक की। हमने पहले भी कई बार ऐसा किया है। हमने उनके साथ अंतरराष्ट्रीय आर्कटिक-प्रशांत साझेदारी पर सहयोग के एक ज्ञापन पर हस्ताक्षर किए। और हम मिलकर यह सुनिश्चित करेंगे कि आर्कटिक क्षेत्र आगे भी किसी के प्रभुत्व या दबाव से मुक्त रहे, और इसके बजाय शांतिपूर्ण संबंधों और व्यापार का केंद्र बना रहे।

हम उन सभी आमंत्रित प्रतिभागियों के आभारी हैं जो इस सप्ताह अटलांटा आए। मैं विशेष रूप से पोलैंड के प्रतिनिधिमंडल का उल्लेख करना चाहता हूं। पोलैंड आर्थिक और सुरक्षा, दोनों ही क्षेत्रों में बहुत तेजी से प्रगति कर रहा है, क्योंकि वे अपने राष्ट्रीय हितों और अपने नागरिकों को सबसे ऊपर रखते हैं। एक राष्ट्र के रूप में वे अधिक मज़बूत और सशक्त हुए हैं। और पोलैंड के सहयोगी देश और साझेदार के तौर पर, अमेरिका भी और अधिक मज़बूत हुआ है। राष्ट्रपति ट्रंप का दृढ़ विश्वास है कि पोलैंड वैश्विक नेताओं के इस मंच पर जगह पाने का हक़दार है। हमें पूरी उम्मीद है कि अगले साल उन्हें – और उभर रहे अन्य सशक्त राष्ट्रों को – फिर से आमंत्रित किया जाएगा।

अब जब हम दिसंबर में डॉरल में होने वाले शिखर सम्मेलन की तैयारी कर रहे हैं, मैं अपने कैबिनेट सहयोगियों का आभार जताना और उनकी सराहना करना चाहता हूं जिन्होंने इस शिखर सम्मेलन से पहले देश भर में बेहद सफल मंत्रिस्तरीय बैठकों का नेतृत्व किया है।

जी20 की अमेरिकी अध्यक्षता, अमेरिका की 250वीं वर्षगांठ से जुड़े प्रमुख आकर्षणों में से एक रही है। हमने इस मंच का सफलतापूर्वक उपयोग ऐसी वैश्विक पहलों के विकास के लिए किया है, जिनसे वास्तव में अमेरिकी जनता को लाभ होता है। अंततः यही हमारी प्राथमिक ज़िम्मेदारी है। इसलिए, हमें दिसंबर में फ़्लोरिडा में राष्ट्रपति ट्रंप के नेतृत्व में होने वाली एक और शानदार जी20 बैठक का इंतज़ार है, जो अमेरिकी नेतृत्व वाले इस वर्ष का एक महत्वपूर्ण समापन बिंदु होगी।

सवाल: यह देखते हुए कि 20 लोगों को किसी एक विषय पर सहमत करना ही कितना कठिन होता है, और यहां तो आप कई तरह के मुद्दों पर चर्चा कर रहे थे, तो मेरा सवाल यह है कि आप किस मुद्दे को लेकर सर्वाधिक चिंतित हैं – शायद चिंतित सही शब्द नहीं हो – लेकिन इस बैठक के बाद सबसे अहम मुद्दों पर आम सहमति बनाने में सबसे बड़ी बाधा क्या रह गई है?

विदेश मंत्री रुबियो: देखिए, सबसे पहली बाधा – अगर कोई है – तो समस्याओं को पहचानने की होती है। अगर आप इस बात पर ही सहमत नहीं होंगे कि समस्याएं क्या हैं, तो आप आगे नहीं बढ़ सकते। इसलिए, मुझे लगता है कि पिछले डेढ़ दिनों में आपने इस बैठक में जो देखा, और मुझे उम्मीद है जो आप नेताओं की बैठक में भी देखेंगे, वह इस बात की सार्वभौमिक स्वीकार्यता है कि विशिष्ट खनिजों, आपूर्ति श्रृंखलाओं, नौवहन की स्वतंत्रता और खाद्य सुरक्षा जैसे मुद्दे ऐसे हैं जिनके बारे में दुनिया के हर देश को चिंतित होना चाहिए।

तो, इन बैठकों में पेश तर्क-वितर्क में आपने जो देखा, उससे साफ़ हो जाता है कि अलग-अलग देश इन समस्याओं के कारणों पर बहस कर रहे हैं और इस बात पर भी चर्चा कर रहे हैं कि इन्हें कैसे सुलझाया जाए। लेकिन मेरा मानना है कि पहला कदम कम से कम इस बात पर व्यापक सहमति बनाना है कि नौवहन की स्वतंत्रता महत्वपूर्ण है, विशिष्ट खनिज मायने रखते हैं, आपूर्ति शृंखलाएं महत्वपूर्ण हैं और खाद्य सुरक्षा अहम है। ये मुद्दे केवल इस बैठक में शामिल देशों के लिए ही नहीं, बल्कि दुनिया भर के देशों के लिए महत्वपूर्ण हैं। मेरा मानना है कि हम इस बात पर सहमत हैं। अब, ज़ाहिर है कि इन समस्याओं को कैसे सुलझाया जाए, इस पर काफी काम करने की ज़रूरत होगी, और सच कहूं तो, इनमें से कुछ समस्याओं के समाधान की राह में बहुत गंभीर चुनौतियां हैं – जैसे रूस और यूक्रेन के बीच युद्ध, मध्य पूर्व में चल रहा संघर्ष, और कुछ अन्य ऐसे संघर्ष जिनका इन मुद्दों से सीधा संबंध नहीं है, लेकिन जो हमारे सामने हैं। उदाहरण के लिए, सूडान में संघर्ष तथा कांगो लोकतांत्रिक गणराज्य और रवांडा के बीच संघर्ष।

लेकिन कम से कम समस्याएं क्या हैं, इस बारे में सहमति तक पहुंचना महत्वपूर्ण है, क्योंकि इससे उन मुद्दों पर आगे बातचीत का आधार तैयार होता है, जिन पर आप चर्चा करना चाहते हैं या उसका प्रयास करते दिखते हैं। बेशक, मैं आज आपसे यह दावा नहीं करूंगा कि हम इन समस्याओं के सबको स्वीकार्य समाधान खोजने के करीब पहुंच गए हैं, लेकिन मेरा मानना है कि यहां प्रतिनिधित्व कर रहे जी20 देशों में से कुछ ऐसे देश हैं, जो इनमें से कुछ समस्याओं को सुलझाने के लिए मिलकर काम कर रहे हैं, खासकर आपूर्ति शृंखलाओं और विशिष्ट खनिजों के क्षेत्र में।


मूल स्रोत: https://www.state.gov/releases/office-of-the-spokesman/2026/10/secretary-of-state-marco-rubio-at-a-press-availability-2/

अस्वीकरण: यह अनुवाद शिष्टाचार के रूप में प्रदान किया गया है और केवल मूल अंग्रेज़ी स्रोत को ही आधिकारिक माना जाना चाहिए।


This email was sent to stevenmagallanes520.nims@blogger.com using Granicus Communications Cloud on behalf of: Department of State Office of International Media Engagement · 2201 C Street, NW · Washington, DC · 20520 Granicus Communications logo

The warning signs most investors see too late

Dear Reader,

Based on my 55 years of watching the market, I'm deeply concerned that we're in the early stages of a financial crisis that could be larger than the Great Financial Crisis of 2008.

This has very little to do with the national debt, as bad as that is.

Nor is it another debt crisis in the housing market like the one that tanked the markets in 2008.

In fact, it doesn't even involve the "AI bubble" or the high-flying stock market, although major, widely held stocks will almost certainly be among the first to crash.

No, this is something far worse, and even more dangerous.

I'm Dr. Martin D. Weiss, New York Times best-selling author, named "Mr. Independence" by Forbesand founder of Weiss Ratings, rated #1 in the Wall Street Journal.

Why #1? Because for 55 years, I have run Weiss Ratings as the nation's only 100% conflict-free, independent financial rating agency in America.

We have never accepted a dime from rated companies for the grades we issue, and we never will. We answer to no one but our members.

Since 1971, when I founded this company, I have publicly predicted six major American crashes before they happened, always naming the companies most likely to fail with ample warning.

And today I'm issuing a public warning about what could be the biggest crisis to ever hit America.

video

In previous financial crises, many have lost half, or even most of their retirement savings.

My job — and my family's job for nearly one hundred years — has been to give Americans the warning before the warning is too late.

And that's what I'm doing in a free video you can watch today.

>> Go here now to see the most important warning of my career. <<

Good luck and God bless!

Martin D. Weiss

Martin D. Weiss, PhD
Weiss Ratings Founder


11780 US Highway 1,
Palm Beach Gardens, FL 33408-3080
Would you like to edit your e-mail notification preferences or unsubscribe from our mailing list?

Copyright © 2026 Weiss Ratings. All rights reserved.


More Reading from MarketBeat

Microsoft's Earnings Problem: Even Great May Not Be Enough

By Chris Markoch. Published: 10/23/2026.

Illuminated Microsoft logo and sign displayed on a monument outside glass office buildings at dusk.

Key Points

  • Microsoft reports fiscal Q1 2027 earnings on Oct. 28, with the stock trading near its 52-week high and little margin for a disappointing result.
  • Analysts remain bullish with a $592.15 consensus price target, but Microsoft must hit its ambitious 45% Azure growth guidance and roughly $50 billion CapEx plans.
  • Technical indicators show fading momentum, including bearish MACD divergence.
  • Special Report: One Company Spared After Renewable Credits Get Cut.

Microsoft Corp. (NASDAQ: MSFT) heads into its fiscal 2027 (FY2027) first-quarter report with very little room for error. The stock closed above $530 per share on Oct. 21, putting it within striking distance of its 52-week high of $553.72.

MSFT is up about 33% since the company last reported earnings, raising the stakes for this release, which is scheduled after the market closes on Wednesday, Oct. 28. A stock trading near its high has already priced in plenty of good news. That's why a clean beat may not be enough to push it higher. Investors will want a beat that also raises the bar for the rest of the fiscal year.

Analysts Are Bullish on MSFT

Nvidia's Huang doubts Musk's latest mega plan can work (Ad)

Nvidia CEO Jensen Huang says Elon Musk's $119 billion plan will be extremely hard to pull off.

Larry Benedict, who ran a $900 million hedge fund and posted 20 consecutive years without a loss, including over $274 million in audited net income between 2004 and 2012, says one long forgotten American company already holds what Musk needs.

Get the ticker and his full analysis before the November 30 deadline.

Click here to get the free ticker before November 30tc pixel

The good news is that analysts don't appear worried. Microsoft analyst forecasts on MarketBeat give the stock a consensus price target of $592.15, up from $578.73 less than two weeks ago. That implies roughly 12% upside from current levels. Adding to the bullish sentiment, 43 of the 49 analysts tracked by MarketBeat rate the stock a Buy.

The latest moves are notable. Jefferies raised its target from $575 to $650 on Oct. 14. Citigroup followed a day later, lifting its target from $600 to $636. Wells Fargo sits near the high end of the range with a $725 target.

Microsoft Azure Growth: Can It Hit 45% Guidance?

As usual, Azure is the headline number to watch. Last quarter, Azure grew 43%, ahead of the 40% analysts expected. The business also topped $100 billion in annual revenue for the first time.

Then management raised the stakes. Microsoft guided for 45% Azure growth in constant currency this quarter, well above the roughly 41% analysts had modeled at the time.

However, that makes 45% the baseline, not the upside case. The market has a history of punishing Microsoft for small misses. In January, Azure grew 38%, beating guidance. The stock still fell 10% because buy-side expectations were higher.

Microsoft guided for total revenue between $89.85 billion and $90.95 billion. Analysts expect earnings of roughly $4.70 per share. Last quarter, the company posted earnings of $4.74 per share, topping consensus by 50 cents.

Microsoft Spending: Why AI Stocks Are Watching

The second number may matter even more. Microsoft guided for about $50 billion in capital expenditures (CapEx) this quarter, up from roughly $36 billion in the prior quarter. The company also projected $175 billion in CapEx for calendar 2026.

Investors will listen closely to management's tone around that spending. Microsoft has said demand still exceeds its available capacity. That's the bullish case for continued investment.

But any hint of a pause would ripple far beyond Redmond. Chipmakers, data center operators and power suppliers all depend on hyperscaler budgets. A slowdown signal from Microsoft would likely be viewed as bearish for the broader AI trade.

There's a counterweight to watch. Free cash flow fell 23% year over year last quarter. Investors want spending to remain aggressive, but they also want proof that it's paying off.

Xbox and Game Pass: Can Microsoft Gaming Return to Growth?

Gaming rarely moves Microsoft stock, but it could shape the narrative. In July, CEO Satya Nadella said he expects Xbox to return to growth in fiscal 2027. That's a bold promise after a rough year.

Xbox revenue fell 7% in fiscal 2026. Hardware revenue dropped 29% on lower console sales. Content and services, which include Game Pass, declined 10% in the fourth quarter alone. Management guided for another mid-single-digit decline this quarter.

That makes October's launch of Gears of War: E-Day an early test. The game set a franchise record with more than 31,000 concurrent players on Steam. Yet estimates from Alinea Analytics put early unit sales at only about 230,000 copies.

The bigger number is subscriptions. The same estimates show about 1.7 million players accessing the game through Game Pass. Microsoft is betting on recurring subscription revenue rather than one-time game sales.

Gears launched in the current quarter, so it won't appear in these results. But management's holiday-quarter outlook could reveal how much it's counting on the franchise. Any update on Game Pass growth will offer a tell on the turnaround.

MSFT Stock: Momentum Fades Near Highs

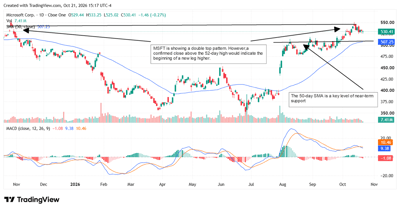
The technical picture is constructive, but momentum is fading. MSFT gapped higher after its July report and has trended upward since. The stock remains well above its rising 50-day simple moving average (SMA), now near $507.

TradingView chart of Microsoft Corp stock price showing a double top pattern, 50-day moving average, and MACD indicator.

However, the stock stalled near $550 in mid-October. That's close to where it peaked last fall before a long decline. A failure to clear that level would raise the risk of a double top.

The MACD indicator adds to the caution. The MACD line has crossed below its signal line, and the histogram has turned negative. MACD also made a lower high in October, even as the stock made a higher high. That bearish divergence suggests buyers are losing conviction.

Initial support sits near $515, the top of the August-September trading range. Below that, the 50-day SMA near $507 is the next key level. On the upside, a decisive close above $554 would confirm the breakout.


Additional Reading from MarketBeat

Not All Tech Is Getting Crushed: 5 Names Holding Up Through the AI Sell-Off

Submitted by Ryan Hasson. First Published: 10/26/2026.

Illustration of a rising green stock chart and arrow above a computer chip, with a declining red chart in the background.

Key Points

  • While semiconductor and memory stocks have sold off sharply, cybersecurity and software names like HACK and IGV have stayed near their 52-week highs.
  • Microsoft, CrowdStrike, and Palantir have shown notable resilience and relative strength, with CrowdStrike up about 120% year to date despite a recent pullback.
  • Upcoming earnings from Microsoft on Oct. 28 and Palantir on Nov. 2 will test whether these resilient tech names can justify their valuations.
  • Special Report: One Company Spared After Renewable Credits Get Cut.

The past few weeks have been rough for much of the technology sector. Concerns about AI spending, lofty valuations and new competition in the chip space have weighed on many tech stocks, particularly semiconductor stocks, neocloud companies and memory stocks. The VanEck Semiconductor ETF (NASDAQ: SMH), for example, finished Friday, Oct. 23, more than 21% below its 52-week high and near major higher-timeframe support and its 200-day simple moving average (SMA).

The good news for bulls, however, is that the sell-off hasn’t been a one-way street across the entire tech sector. Look a little closer, and several pockets of the sector have held up surprisingly well, with a few still trading within striking distance of their 52-week and even all-time highs. Interestingly, much of that strength has come from software and cybersecurity stocks—two areas many investors had written off earlier this year as likely losers in the AI race. That narrative has since flipped on its head.

Nvidia's Huang doubts Musk's latest mega plan can work (Ad)

Nvidia CEO Jensen Huang says Elon Musk's $119 billion plan will be extremely hard to pull off.

Larry Benedict, who ran a $900 million hedge fund and posted 20 consecutive years without a loss, including over $274 million in audited net income between 2004 and 2012, says one long forgotten American company already holds what Musk needs.

Get the ticker and his full analysis before the November 30 deadline.

Click here to get the free ticker before November 30tc pixel

That recent outperformance and relative strength are worth watching. When one corner of a sector sells off while another holds firm, it can reveal where capital is flowing and which groups could lead if sentiment improves. Here are five names and funds within the technology sector that stand out.

Cybersecurity’s Basket Sits Near Its Highs

The Amplify Cybersecurity ETF (NYSEARCA: HACK) has been one of technology’s steadiest corners through the recent sell-off and turbulence. The fund is up 60% year to date and closed Friday less than 3% below its 52-week high. The ETF is arguably one of the purest ways to gain exposure to the broader cybersecurity industry.

HACK holds 49 cybersecurity names. Its largest positions include Broadcom (NASDAQ: AVGO), CrowdStrike (NASDAQ: CRWD), Cisco (NASDAQ: CSCO), Palo Alto Networks (NASDAQ: PANW) and Fortinet (NASDAQ: FTNT), each representing roughly 5% to 6.5% of the fund.

The bull case for cybersecurity has strengthened as AI spreads and gains wider adoption. Every AI agent and automated workflow a company deploys creates new access points that need protection, and security budgets have historically been among the last to be cut when spending tightens. With a beta of 0.84, HACK has also traded with less volatility than the broader market.

From a technical perspective, the relative strength is clear. The ETF pulled back in early October to its rising short-term SMAs but quickly confirmed a higher low within its uptrend. Unlike the broader technology benchmark, it is holding close to its 52-week high and above all its key SMAs. That’s a clear sign that capital has flowed into this pocket of the technology sector, potentially setting it up as a future leader.

Software’s Comeback Is Holding

At first glance, the iShares Expanded Tech-Software Sector ETF (BATS: IGV) doesn’t look like a standout, up only about 5% on the year. That figure, however, obscures how far the fund has come. IGV has rallied nearly 50% from its 52-week low and now sits roughly 6% below its high, near the top of its higher-timeframe range.

Technically, it’s also shaping up for a potential breakout. The fund has spent several months consolidating near its 52-week high, with that high now acting as a potential springboard for further upward momentum and continued outperformance.

The shift in narrative has been the key driver. Earlier in the year, investors worried AI would undercut traditional software. More recently, they seem to be recognizing that companies controlling customer data and everyday business workflows are often best positioned to sell AI on top of those assets. IGV’s top holdings tell the story: Palo Alto Networks, CrowdStrike, Palantir (NASDAQ: PLTR) and Microsoft (NASDAQ: MSFT) each make up roughly 8% to 9.6% of the fund, and many of those names have shown notable short-term outperformance versus the broader sector.

Microsoft Heads Into Earnings Near Its Highs

Microsoft (NASDAQ: MSFT) closed Friday at $524.51, up about 9% this year and roughly 5% below its 52-week high. For a $3.9 trillion company in the middle of an AI-driven sell-off, that’s notable resilience.

The next big test for the mega-cap tech titan is just around the corner. Microsoft reports fiscal first-quarter 2027 results on Oct. 28, and investors will be watching closely to see whether Azure delivers on growth guidance of around 45%, along with updates on capital spending.

The fundamentals remain strong, with net margins above 40% and projected earnings growth of 18%. Analysts have a Moderate Buy consensus from 49 analysts, with an average price target of $592.15 implying 13% upside. Still, with the stock near its highs heading into the report, the bar for a positive reaction is high.

CrowdStrike Has More Than Doubled This Year

CrowdStrike (NASDAQ: CRWD) is the standout performer of the group, up about 120% year to date. Shares have pulled back about 10% from their 52-week high of $286.99.

Friday’s action stood out in particular. The stock held its rising 50-day SMA and sharply rallied intraday to close above its 20-day SMA. That move confirmed a higher low in its steady uptrend and, from a technical perspective, further established the stock as a leader in the technology sector.

CrowdStrike is the largest holding in HACK and the second-largest holding in IGV, so its strength helps explain both funds’ resilience. Demand for its Falcon platform has stayed sticky, and CEO George Kurtz recently warned that a fresh wave of cyberattacks is coming—a reminder that security spending tends to be driven by threats rather than the economic cycle.

One thing worth noting, however, is that the average analyst price target of $239.27 now sits below the current share price, suggesting the stock has moved faster than Wall Street’s models. The stock’s next major known test will be its next earnings report, estimated for early December.

Palantir’s Next Test Is the Numbers

Palantir Technologies (NASDAQ: PLTR) has also held up relatively well, closing Friday at $196.75. That put it up nearly 11% this year and roughly 8% below its 52-week high of $212.94. While many other retail-favorite technology names have fallen below their key SMAs, PLTR has done a great job maintaining its uptrend and staying above its key moving averages.

Beyond its much-discussed stretched valuation, including a forward price-to-earnings ratio of almost 150, the business has continued to impress fundamentally. Palantir generates net margins of about 49%, and analysts project earnings growth of nearly 46% over the next year.

Palantir recently announced a new partnership with Knox Systems that expands its reach in government technology. However, valuation remains the central debate. At more than 100 times sales, the stock leaves little room for disappointment, and the average price target of $203.48 implies only about 3% upside. With third-quarter earnings due around Nov. 2, the results will need to justify the premium.

A Divergence Worth Watching

Taken together, these five suggest the recent sell-off has been more of a rotation within technology than a wholesale exit from the sector. Chips and memory have taken the brunt of AI fears, while many mega-cap software and cybersecurity names have held near their highs.

That doesn’t make these names immune. CrowdStrike and Palantir already trade near or above their average analyst targets, while Microsoft’s Oct. 28 earnings report and Palantir’s Nov. 2 results will be key tests. But if fears around AI valuations and spending ease, the groups that held up best under pressure may be best positioned to lead the next move higher.

Thank you for subscribing to The Early Bird, MarketBeat's 7:00 AM newsletter that covers stories that will impact the stock market each day.
 
This email communication is a sponsored message for Weiss Ratings, a third-party advertiser of The Early Bird and MarketBeat.
 
If you have questions about your account, please feel free to contact MarketBeat's support team, based in South Dakota, at contact@marketbeat.com.
 
If you no longer wish to receive email from The Early Bird, you can unsubscribe.
 
© 2006-2026 MarketBeat Media, LLC. All rights reserved.
345 North Reid Place, Sixth Floor, Sioux Falls, S.D. 57103-7078. United States..
 
Read More: A weekly dividend fund holding Nvidia and Palantir 

Page List

Blog Archive

Search This Blog

Why December 11 Could Reshape a 46 Billion Pentagon Program

See why one overlooked company could play a pivotal role before this Pentagon deadline hits ͏  ͏  ͏  ͏  ͏...