|
Friday, June 5, 2026
RLRH: Are you fueling for YOUR training load?


This same-day trade is getting a lot of attention
Hey Trader,
There’s a specific type of trade happening every single day…
And most traders either ignore it…
Or completely misuse it.
It’s called a zero-days-to-expiration trade or 0DTE for short.
Now, most people assume a trade that starts and ends on the same day means you’re taking on more risk.
But that’s not always the case. At least not the way I do it.
Because my 0DTE trades give you:
- Shorter exposure to risk
→ Faster feedback
→ Clear entry/exit windows
And when done right…
They can turn a single day into a solid payday.
That’s exactly what my new 0DTE Playbook shows you how to do (click here for details)…
Inside, you’ll see how my strategy works step-by-step…
Without needing to stare at charts all day.
Take a look here while it’s still available.
To one-day trading success,
Dave Aquino
Lead Income Trader, Base Camp Trading
Exclusive News
Quantum Computing's Commercial Breakout Has Arrived
Authored by Jeffrey Neal Johnson. Originally Published: 5/27/2026.
Key Points
- Government funding and strategic investments are establishing a secure domestic manufacturing foundation for advanced quantum hardware platforms.
- The transition toward recurring cloud service models is creating predictable revenue streams and driving widespread enterprise adoption across global sectors.
- Maturing commercial foundries are successfully scaling up the production of sophisticated computing components to support long-term technological growth.
- Special Report: The Biggest IPO Ever: Claim Your Stake Today
The quantum computing sector is undergoing a fundamental repricing, but the catalyst is not what most investors might expect.
While the U.S. government's recent $2 billion capital injection via the CHIPS and Science Act provides a meaningful operational runway, the more profound structural shift is happening at the commercial level. The industry has finally crossed the chasm from theoretical lab physics to utility-scale industrial infrastructure, driven by rapid growth in enterprise bookings, the maturation of recurring cloud-based revenue models, and a structural pivot toward high-yield commercial wafer fabrication.
Elon's new "super startup" (Ad)
Adam O'Dell - the analyst who recommended Palantir before it became the top S&P 500 performer - has identified a new venture quietly incubating inside Tesla. It has nothing to do with EVs, AI, or robotics, yet it generated $12 billion in 2025 alone.
Blackstone calls the broader opportunity a $23 trillion investment runway. Adam believes investors who position themselves before July 22 are early. He's also giving away a free ticker pick in his latest briefing.
Watch Adam O'Dell's full briefing and get his free ticker nowFor investors, this marks a critical inflection point. The speculative phase, once defined by academic milestones and prototype demonstrations, is giving way to a new era of tangible enterprise adoption, scalable manufacturing, and defensible business models. This evolution demands a fresh look at the key players who are not just building the future of computing, but also constructing the commercial and industrial foundation for it today.
Building the Quantum Backbone
The clearest signal of the industry's maturation is the pivot from bespoke, low-yield research projects to standardized, high-yield commercial fabrication. Two companies exemplify this crucial infrastructure build-out, positioning themselves as the essential picks and shovels of the new quantum economy.
International Business Machines (NYSE: IBM) is leveraging its deep manufacturing expertise to anchor the domestic supply chain.
The new Anderon subsidiary, capitalized with $1 billion in federal funding and a matching $1 billion internal investment, is set to become a dedicated 300mm quantum wafer fabrication facility.
This strategic move separates the high-capital-expenditure foundry business from IBM's core operations, allowing the company to build a foundational manufacturing moat. It also gives investors direct exposure to the sector's long-term industrial potential, backed by IBM's formidable balance sheet and existing profitability.
Similarly, GlobalFoundries (NASDAQ: GFS) is carving out a critical niche as a multi-platform foundry. Its new Quantum Technology Solutions division, bolstered by a $375 million CHIPS Act grant, is designed to produce quantum components across multiple modalities, including superconducting, trapped-ion, and photonic systems.
This positions GlobalFoundries not as a bet on a single winning technology, but as an indispensable partner for the entire ecosystem. GlobalFoundries is set to capture value regardless of which modality ultimately dominates specific applications, making it a powerful horizontal play on the sector's overall growth.
From Lumpy Hardware to Predictable Cloud Revenue
For the pure-play quantum operators, the business model itself is undergoing a transformation that significantly de-risks the investment profile. The historical reliance on lumpy, unpredictable hardware sales is being replaced by the stable, recurring revenue streams of quantum-as-a-service (QaaS) platforms, which are proving their commercial viability.
D-Wave Quantum (NYSE: QBTS) offers a compelling case study.
A superficial look at its Q1 2026 earnings reveals a sharp revenue contraction. A deeper analysis, however, shows this was due to a non-recurring hardware sale in the prior year's quarter.
The real story for D-Wave Quantum lies in bookings, which surged an astonishing 1,994% to $33.4 million, driven by major enterprise and institutional deals. This demonstrates accelerating demand for its hybrid quantum-classical cloud services, establishing a predictable, high-margin revenue base that is far more valuable than one-off system sales.
This trend is echoed across the sector. Rigetti Computing (NASDAQ: RGTI) is driving adoption through its Quantum Cloud Services platform, which now provides access to its newly available 108-qubit Cepheus-1 system.
By focusing on cloud access, these operators lower the barrier to entry for enterprise clients, accelerating the discovery of commercial use cases in financial modeling, pharmaceutical research, and logistics optimization.
It’s Not a Winner-Takes-All Race
While concerns about a winner-takes-all scenario persist, the sector's diversification across modalities such as superconducting, neutral-atom, and annealing technologies reduces overall risk and fosters resilience.
The field includes several distinct approaches, each with unique strengths:
Superconducting Qubits: Pursued by leaders like IBM and Rigetti Computing, this is one of the most mature technologies for building universal gate-model quantum computers.
Neutral Atoms: Championed by newcomers such as Infleqtion (NYSE: INFQ), this approach offers the potential for large qubit counts and strong connectivity, attracting significant attention and capital following its public market debut.
Quantum Annealing: The specialty of D-Wave Quantum, this modality is already delivering commercial value for complex optimization problems today, even as the dual-platform quantum computing company develops its own gate-model systems.
This technological diversity is a sign of a healthy, expanding market. It suggests the future of quantum computing will not be a monolith but a rich ecosystem of specialized solutions tailored to different problems, much like the classical computing world has both central processing units and graphics processing units.
Balancing Near-Term Risk With Long-Term Runway
While the long-term outlook appears robust, investors must balance this potential against near-term financial realities. The pure-play operators are currently experiencing significant cash burn and deep margin compression as they invest heavily in research and development.
However, many are fortified with strong balance sheets. Rigetti Computing, for instance, holds approximately $569 million in cash with virtually no debt, providing a multi-year runway to execute its technology roadmap without the immediate threat of shareholder dilution.
For investors building a quantum portfolio, the paths to exposure are becoming clearer.
The infrastructure players, IBM and GlobalFoundries, offer a more conservative approach, grounding their quantum ambitions in profitable, cash-flow-positive legacy businesses.
The pure-play companies, including D-Wave Quantum, Rigetti Computing, and the recently public Infleqtion, present a higher-risk, higher-reward opportunity. Investors with a long-term horizon might consider watching these names closely as they translate technological breakthroughs into recurring enterprise revenue, marking the true beginning of the commercial quantum era.
Exclusive News
Ulta's Q1 Report Primes It for a Beauty of a Rebound
Authored by Thomas Hughes. Originally Published: 6/4/2026.
Key Points
- Ulta Beauty is trading near long-term lows, setting up for a solid rebound this year.
- A deep value opportunity is highlighted by analysts' trends and institutional stock accumulation.
- Upside potential runs in the 40% range in the mid-term, with a triple-digit gain expected over the long term.
- Special Report: The Biggest IPO Ever: Claim Your Stake Today
Ulta Beauty (NASDAQ: ULTA) has faced the same hurdles as many consumer companies this year, but it is navigating them well, and its strategies are working. Focused on store expansion, international growth, acquisitions, and broader product offerings, the company is growing, outperforming estimates, and appears positioned to sustain that strength in the quarters ahead.
For investors, the key takeaway is that Ulta Beauty’s stock price is at long-term lows and set up to rebound as the year progresses. The main question is timing, and it may come sooner than early June price action suggests. With the company gaining traction, the stock trading at deep-value levels, and sell-side activity in accumulation mode, the shares have little room left to go but up.
Elon's new "super startup" (Ad)
Adam O'Dell - the analyst who recommended Palantir before it became the top S&P 500 performer - has identified a new venture quietly incubating inside Tesla. It has nothing to do with EVs, AI, or robotics, yet it generated $12 billion in 2025 alone.
Blackstone calls the broader opportunity a $23 trillion investment runway. Adam believes investors who position themselves before July 22 are early. He's also giving away a free ticker pick in his latest briefing.
Watch Adam O'Dell's full briefing and get his free ticker nowThe initial analyst response to the company's Q1 earnings report sums up the situation well. It included several price target reductions issued immediately after the report, but those were cautionary notes within an otherwise bullish outlook. The cuts pressured sentiment, yet the $651 consensus price target still offers substantial upside for a Buy-rated stock. A move to Cannaccord’s new $731 target would put Ulta at new all-time highs, and catalysts ahead could drive the stock higher.
Catalysts Loom for Ulta Beauty: Rebound Ahead
Future earnings reports are likely to show additional momentum, supporting a bullish outlook for this stock. MarketBeat tracks 27 analysts who rate the stock a consensus Moderate Buy, with a 75% Buy-side bias. The trailing 12-month (TTM) average price target of $688 implies 40% upside from key support levels and could be reached within months of a confirmed bottom. Signs that a bottom has been reached include technical and sell-side factors, while signs of new highs would come from analyst forecasts and continued technical strength.
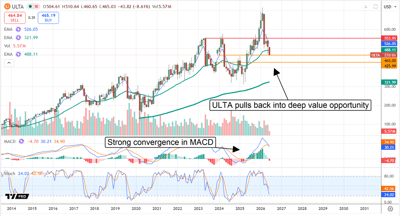
Institutions are the driving force in this market. They own approximately 90% of the stock and have been accumulating shares on a TTM basis. MarketBeat data show that institutions were adding at a rate of nearly $2 per $1 for four consecutive quarters, even as price action remained highly volatile. On the technical side, the monthly chart shows a sharp convergence. The MACD convergence suggests a market gaining strength as it approached the early 2026 peak, setting up a retest of the existing high at least on the next rebound. Again, the only question is timing, and it could easily begin by mid-summer, if not sooner.
Ulta Beauty Fires on All Cylinders in FQ1 2026
Ulta Beauty delivered a solid Q1, with revenue rising 11.1% to $3.16 billion, 130 basis points better than expected. The strength was driven by a 5.3% comparable-store increase, new stores, and acquisitions. Sales were strong across product categories, with cosmetics leading at up 40%. Skin care grew 24%, hair 18%, and fragrances 12%, all strong results. Sales were also solid across channels, reflecting the impact of Ulta’s digital and e-commerce efforts.
Margin news was also positive. Fears of margin degradation tied to tariffs, macro headwinds, and aggressive growth plans proved overblown. The company widened its gross margin by 100 bps and kept costs under control. Operating income grew 11.6%, adjusted net income rose 10.8%, and diluted earnings per share increased 15.5%, beating consensus by more than 1,000 bps. Looking ahead, management expects margin strength to continue. It reaffirmed its revenue target and raised its earnings outlook to align with consensus estimates.
Management also increased the 2026 buyback target, a catalyst for institutional money flows. The increase was worth $500 million, bringing the total to $1.5 billion and signaling confidence in future cash flow. The key takeaway is that Ulta is aggressively reducing its share count while accelerating growth, which raises questions about the stock’s valuation. At $465 per share, Ulta trades at only 7X its 10-year earnings outlook, suggesting that 200% or more in stock price upside is possible over time.
Ulta’s balance sheet shows no red flags, only reasons to believe share buybacks will continue. Quarter-end highlights include lower cash, higher current and total assets, persistently low leverage, and a 6% increase in equity despite heavy investment and capital returns. The likely outcome is that Ulta will continue reducing its share count in the coming quarters, helping its stock rebound over time. The biggest risk for Ulta this summer is oil and gas prices and their impact on consumer spending.
Thank you for subscribing to The Early Bird, MarketBeat's 7:00 AM newsletter that covers stories that will impact the stock market each day.
This email communication is a paid advertisement for Base Camp Trading, a third-party advertiser of The Early Bird and MarketBeat.
If you have questions or concerns about your account, please don't hesitate to email MarketBeat's U.S. based support team at contact@marketbeat.com.
If you no longer wish to receive email from The Early Bird, you can unsubscribe.
© 2006-2026 MarketBeat Media, LLC. All rights protected.
345 North Reid Place, Suite 620, Sioux Falls, SD 57103-7078. USA..
Today's Bonus Content: I wish this wasn’t the case (From Porter & Company)
This email communication is a paid advertisement for Base Camp Trading, a third-party advertiser of The Early Bird and MarketBeat.
If you have questions or concerns about your account, please don't hesitate to email MarketBeat's U.S. based support team at contact@marketbeat.com.
If you no longer wish to receive email from The Early Bird, you can unsubscribe.
© 2006-2026 MarketBeat Media, LLC. All rights protected.
345 North Reid Place, Suite 620, Sioux Falls, SD 57103-7078. USA..
SpaceX Goes Public. Your 401k Funds It.
Dear Reader,
SpaceX is going public at $1.75 trillion.
The largest IPO in the history of Wall Street.
The excitement is real. The valuation is real. The gains available to the people already inside are real.
You are not one of those people.
By the time you can buy a single share, the institutions have bought it all.
The 30x gain is gone.
But here is the part nobody is talking about.
Your 401(k) is not just excluded from the upside. It is funding the exit.
Nasdaq approved a rule on March 30, the Fast Entry provision, which requires every Nasdaq-100 index fund to buy SpaceX shares 15 trading days after listing. The full Nasdaq-100 ecosystem represents over $1.4 trillion in exposure sitting in millions of IRAs and 401(k)s.
Your index fund must comply. It does not ask your permission.
It buys at whatever price the market sets on entry day. After the deal is priced. After the float is established. After the insiders who hold 95% of shares are positioned to sell into the demand your fund creates.
Michael Burry has two words for the role your 401(k) plays in this arrangement.
"Exit liquidity."
Robin Wigglesworth of the Financial Times calls the whole structure the biggest bagholder operation in history.
You did not choose to be the exit liquidity for the largest IPO in history. That is simply where index fund savings go.
Physical gold is not inside Nasdaq. No Fast Entry rule touches it. No IPO forces it to buy anything. It holds what you put into it. And it grows in value.
The 2026 Gold Guide explains how to move a portion of your savings outside the mechanism. Tax-free. Penalty-free. In days.
Everyone is talking about how to get into SpaceX.
The question worth asking is how to get your savings out.


Further Reading from MarketBeat Media
Silicon Shake-Up: The AI Trade Is Moving Beyond NVIDIA
Author: Jeffrey Neal Johnson. Date Posted: 5/21/2026.
Key Points
- Surging trading volume confirms that major institutional funds are actively deploying capital into legacy semiconductor manufacturers to capture expanding data center demand.
- Strategic acquisitions of next-generation architecture providers are immediately enhancing the competitive positioning and future growth prospects for incumbent silicon foundries.
- Monumental supply chain victories and new hyperscaler deployment contracts are actively validating the lucrative expansion of total addressable market opportunities across the sector.
- Special Report: The Biggest IPO Ever: Claim Your Stake Today
The first wave of the artificial intelligence (AI) boom created unprecedented wealth, catapulting a select group of mega-cap tech stocks into the stratosphere. Now, the second act is beginning.
Institutional capital, wary of valuations priced for perfection, is carrying out a structural rotation. It is bypassing the saturated high-flyers and flowing into foundational semiconductor sector equities positioned to capture an expanding $132 billion data center compute market.
Elon's new "super startup" (Ad)
Adam O'Dell - the analyst who recommended Palantir before it became the top S&P 500 performer - has identified a new venture quietly incubating inside Tesla. It has nothing to do with EVs, AI, or robotics, yet it generated $12 billion in 2025 alone.
Blackstone calls the broader opportunity a $23 trillion investment runway. Adam believes investors who position themselves before July 22 are early. He's also giving away a free ticker pick in his latest briefing.
Watch Adam O'Dell's full briefing and get his free ticker nowThis strategic shift is no longer just a forecast; it is happening now, with recent market action providing clear evidence. Aggressive M&A activity and imminent hyperscaler deployment contracts are permanently re-rating the sector's margin profile as the AI halo effect finally moves down the supply chain to legacy silicon providers with the scale to execute.
Awakening the Giants: Trading Volume Confirms the Rotation
The most telling indicator of a major market rotation is not analyst commentary, but the flow of capital itself.
Exceptional trading volume often precedes a structural re-rating of an asset, and the semiconductor sector is offering a textbook example.
The clearest evidence comes from Intel Corporation (NASDAQ: INTC), which recently saw its shares trade on a healthy intraday volume of 137.66 million, a stark deviation from its average.
This surge is not an isolated event but the culmination of accumulated interest that has propelled the stock to a remarkable year-to-date performance of more than 220%.
Such heavy volume does not come from retail traders alone; it signals that large institutional funds are actively deploying capital, building significant positions in a name they believe is at an inflection point.
This activity confirms the thesis that a deliberate, large-scale rotation is underway, targeting undervalued legacy players with the capacity to meet surging AI demand.
A Multi-Billion Dollar Bet on Next-Generation Architecture
With the AI landscape evolving at a breakneck pace, established semiconductor manufacturers are using their balance sheets to acquire the next-generation technology needed to compete. This M&A pipeline is a core catalyst driving the sector's re-rating. Intel Corporation is again at the center of this trend, with reports of advanced discussions to acquire Tenstorrent for as much as $5 billion.
This is far more than a simple bolt-on acquisition; it would represent a strategic masterstroke to gain a foothold in the critical RISC-V architecture. Acquiring Tenstorrent's AI accelerator technology and open-source software stack would give Intel Corporation an immediate, credible path to challenge current data center monopolies.
The Street understands the significance of this potential move, with Melius Research issuing a $150 price target, anticipating immediate margin accretion as Intel Corporation pivots toward these higher-growth opportunities. This aggressive M&A posture is a clear signal that legacy silicon is not content to be left behind; it is actively buying its way into the AI halo effect.
How Legacy Silicon Is Capturing Critical Market Share
Speculation can only drive a stock so far; eventually, a company must deliver tangible business wins to justify its valuation. The rotation into legacy silicon is now being validated by exactly these kinds of wins, as hyperscalers and AI labs diversify their supply chains.
Advanced Micro Devices (NASDAQ: AMD) exemplifies this phase of the thesis.
AMD has reportedly secured a significant capacity allocation for its upcoming MI450 accelerator to power a new deployment for AI leader Anthropic.
This major win provides concrete evidence that Advanced Micro Devices is successfully capturing market share from incumbents in the lucrative AI accelerator space—and is a key reason why analysts now project the data center TAM will exceed $120 billion by 2030.
The market's conviction is reflected in AMD's options chain, where a 30-day put/call ratio of 0.98 signals strong bullish sentiment and limited hedging.
It is also being validated by Wall Street, where Citi recently raised its price target on Advanced Micro Devices to $460, citing the Anthropic deal. These contracts are the ultimate litmus test, proving that these companies have the technology to compete and win in the AI era.
Positioning for Profit: How to Approach the Semiconductor Rotation
The evidence points toward a multi-year infrastructure build-out that provides a powerful tailwind for the entire semiconductor ecosystem. The bull case rests on a $132 billion capital expenditure cycle redirecting toward these foundational providers.
However, this rotation is not without risk. The forward multiples on these stocks reflect high expectations, leaving little room for error.
The primary risk for Intel and Advanced Micro Devices is execution; any delays in product roadmaps or manufacturing issues could lead to significant margin compression. Competition remains intense, and the geopolitical landscape surrounding semiconductor manufacturing adds another layer of complexity.
For investors, this environment demands a clear strategy. The AI trade is undeniably broadening, and the data suggests the rotation into legacy silicon is well underway. Investors with a higher risk tolerance might consider the powerful volume and strategic catalysts as confirmation that the market is finally rewarding these manufacturing giants. More cautious investors may prefer to wait for a market-wide pullback to offer a more attractive entry point, while also watching the next round of earnings reports to confirm that margin expansion is not just a forecast, but a reality.
Further Reading from MarketBeat Media
The Careful Consumer: What Q1 Earnings Reveal—And Where Cracks May Appear
Author: Chris Markoch. Date Posted: 5/25/2026.
Key Points
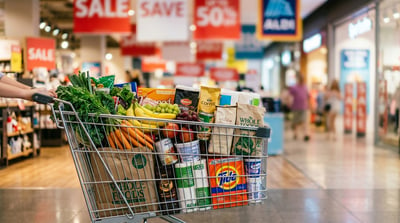
- Walmart, Home Depot, and other retailers say consumers remain active but increasingly price-sensitive.
- Buy-Now-Pay-Later delinquencies are rising sharply, signaling growing financial stress among lower-income consumers.
- Investors may need a more selective approach toward retail and consumer-facing stocks in a bifurcated economy.
- Special Report: The Biggest IPO Ever: Claim Your Stake Today
The stock market and the economy are not the same thing, but in 2026 they share one trait: skepticism. Despite blockbuster earnings reports from companies like NVIDIA (NYSE: NVDA), Palantir Technologies (NASDAQ: PLTR), and Alphabet (NASDAQ: GOOGL), this may be the most reluctant bull market in history. That doesn’t mean investors are leaving the market, but the concentration of market winners is still not broadly expanding into other sectors.
The recent retail earnings reports aren’t going to change that. On the surface, the consumer looks resilient. Retail sales data continues to at least meet, if not exceed, expectations. However, all may not be as it seems. Retail giants like Walmart Inc. (NASDAQ: WMT), Home Depot (NYSE: HD), and TJX Companies (NYSE: TJX) have been telling a cautious story.
Elon's new "super startup" (Ad)
Adam O'Dell - the analyst who recommended Palantir before it became the top S&P 500 performer - has identified a new venture quietly incubating inside Tesla. It has nothing to do with EVs, AI, or robotics, yet it generated $12 billion in 2025 alone.
Blackstone calls the broader opportunity a $23 trillion investment runway. Adam believes investors who position themselves before July 22 are early. He's also giving away a free ticker pick in his latest briefing.
Watch Adam O'Dell's full briefing and get his free ticker nowConsumers are still spending, but with real intentionality. And since investors are also consumers, it may be getting harder to separate the two. The investor deciding whether to add a retail stock to their portfolio and the shopper deciding whether to remodel their kitchen are increasingly the same person making the same calculation: Is now the right time to commit?
How Consumers Are Actually Spending
The word "choiceful" has become part of the retail lexicon. Walmart used it explicitly on its Q1 earnings call to describe a customer who is still showing up but making sharper trade-offs at every price point. Management also pointed to consumers shifting toward private-label brands, even among higher-income shoppers.
Home Depot offered one of the more telling data points of the earnings season: same-store sales growth remained modest, with customers completing smaller repair and maintenance projects while continuing to defer large remodels.
Lowe's (NYSE: LOW) also spoke of a consumer who is engaged but not confident. Both stocks have held up reasonably well because repair-and-maintain spending is more recession-resistant than new construction—but neither is a growth story right now.
At the lower leg of the "K-shaped" economy, consumers are even more careful. Tax refunds, no matter how much bigger they were, have largely been spent. Inflation and rising energy prices are squeezing budgets further, leading some analysts to raise the prospect of interest rate hikes, which would be an additional headwind for discretionary retail and for the housing-adjacent names that depend on an active mortgage market.
A more uncomfortable, but honest, question is: How are lower-income consumers doing? Consumer delinquency rates are a lagging indicator and can be tricky, as can the percentage of revolving debt being carried by consumers. However, one of the newest arrows in the consumer purchasing quiver is sending a clear signal that’s hard to ignore.
Buy Now Pay...Never?
As of March 2026, 47% of buy-now-pay-later (BNPL) users report having paid late on a loan in the past year. That was up 6 points from 41% in 2025, and up 13 points from 34% in 2024. Delinquencies on multiple loan types have hit historic highs in recent years, concentrated primarily among low-income earners.
The structural problem is twofold. First, BNPL was designed to be a budgeting tool; instead, it's become a financial lifeline, with more than half of current users reporting they wouldn't be able to make ends meet without it.
Second is the issue of invisible debt: most BNPL debt doesn't appear in credit bureaus, creating what regulators call "phantom debt." That means the stress doesn't show up in traditional delinquency metrics until it's already acute. For investors watching retail same-store sales for signs of consumer strain, this is precisely why those numbers can look fine right up until they don't.
The Bifurcated Investor
This has been a sobering look at the data, but data shouldn't be ignored simply because it's inconvenient. And there is genuine good news: the stock market is truly different from the economy. Despite, and maybe because of, the uncertain retail environment, it's never been more important to build wealth, and stocks remain a proven way to do that.
But it's also important to know what you own. A K-shaped economy calls for a K-shaped portfolio approach. That means being deliberate about which end of the consumer spectrum each stock is actually serving. For many investors, this means buying companies with strong, growing earnings and plenty of cash on the balance sheet.
In the case of technology stocks, investors should pay less attention to valuation models that don't account for the digital age and let the company's performance do the talking. The “customers” of these companies are hyperscalers that are committing billions of dollars to AI infrastructure. Those companies are spending based on defined future demand.
Energy stocks are a momentum play right now, and there's a technology tie-in to this sector that is becoming increasingly hard to ignore. At every level of the AI infrastructure chain, this earnings season has confirmed the demand story—and as buildout accelerates, it confirms the need for energy in every form.
For investors who find that retail stocks are closer to "buying what they know," there's still quality and value to go around. TJX Companies and Ross Stores (NASDAQ: ROST) have a structural tailwind in this environment. The off-price retail companies attract both the value-seeker trading down and the bargain-hunter trading across, making them more resilient than most in a bifurcated economy.
But with retail stocks broadly, valuation matters a great deal. That may mean keeping names on a watch list until there is stronger evidence of a consumer recovery—or until the BNPL data, which may be the most honest real-time signal we have, starts moving in the right direction. After all, the same consumer who is leaning on installment loans to cover groceries is the one your favorite retail stock is counting on to walk through the door.
Thank you for subscribing to Insider Trades Daily, which covers the most recent insider buying and selling activity from Wall Street CEO's, CFO's, COO's and other insiders.
This email is a sponsored email sent on behalf of Americas Gold Company, a third-party advertiser of InsiderTrades.com and MarketBeat.
If you have questions about your newsletter, feel free to contact MarketBeat's South Dakota based support team at contact@marketbeat.com.
If you no longer wish to receive email from InsiderTrades.com, you can unsubscribe.
© 2006-2026 MarketBeat Media, LLC. All rights protected.
345 North Reid Place, Sixth Floor, Sioux Falls, SD 57103-7078. U.S.A..
Today's Bonus Content: I wish this wasn’t the case (From Porter & Company)
This email is a sponsored email sent on behalf of Americas Gold Company, a third-party advertiser of InsiderTrades.com and MarketBeat.
If you have questions about your newsletter, feel free to contact MarketBeat's South Dakota based support team at contact@marketbeat.com.
If you no longer wish to receive email from InsiderTrades.com, you can unsubscribe.
© 2006-2026 MarketBeat Media, LLC. All rights protected.
345 North Reid Place, Sixth Floor, Sioux Falls, SD 57103-7078. U.S.A..
(Português Continental) Caso não tenha assistido: O Embaixador Mike Waltz e o Embaixador Dan Negrea Falam sobre a Nova Iniciativa do Departamento de Estado dos Estados Unidos: “Comércio em vez de Ajuda”.
|
|
||||
Subscribe to:
Posts (Atom)
Save 20% sitewide 🔥 Fuel competitive drive in every session
Take head-to-head reaction training to the next level with BlazePod ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏...
-
Having trouble viewing this email? View it as a Web page . You are subscribed to Constit...
-
Plus, Deaths of foreign fighters draw renewed attention to the military volunteers in Ukraine. ...
-
We'll be sending you the latest buy and sell ratings from Wall Street's top analysts, but first,...


