| Unsubscribe |
Dear Reader,
I need to speak with you directly.
I want you to see the most important warning of my career …
And one of the most important warnings any American family will receive before the next great financial crisis hits this country.
I'm Dr. Martin D. Weiss. I'm a Wall Street Journal, BusinessWeek, and New York Times best-selling author.
And for 55 years I have run Weiss Ratings … the only 100% conflict-free, independent financial rating agency in America.
We are paid by no one we rate. We answer to no one but our subscribers.
And in the 55 years since I issued my first public warning before a financial crisis, I have publicly predicted six major American crashes, before they happened.
What I'm seeing now is a $3 trillion problem.
And the biggest danger right now is NOT just another stock market crash.
The biggest danger is NOT only a major bank failure.
Rather, it's a chain reaction of crashes and failures that could cause a global freeze in the financial markets. And it starts here:
Go here now to see the most important warning of my career
Good luck and God bless!
Sincerely,
Martin D. Weiss, PhD
Weiss Ratings Founder
11780 US Highway 1,
Palm Beach Gardens, FL 33408-3080
Would you like to edit your e-mail notification preferences or unsubscribe from our mailing list?
Copyright © 2026 Weiss Ratings. All rights reserved.
There's a New Q in Town: Invesco's ETF Targets International Innovators
By Jessica Mitacek. First Published: 10/22/2026.
Key Points
- Invesco launched QQI on Sept. 23 to track the Nasdaq International Innovators 100 Index, targeting innovative companies headquartered outside the United States.
- The ETF screens for heavy research and development spending, revenue and margin growth, and sustained profitability, with top holdings including Taiwan Semiconductor and ASML.
- As a new fund with just $3.91 million in assets, QQI faces low trading volume and a higher expense ratio of 0.29% compared with QQQ and QQQM.
- Special Report: Why This Clean Energy Well Escaped the Solar and Wind Cuts.
On Sept. 23, investment management firm Invesco—the company behind the enormously popular Invesco QQQ Trust Series 1 (NASDAQ: QQQ) and its sister fund, the Invesco NASDAQ 100 ETF (NASDAQ: QQQM)—launched the newest member of its Q-themed offerings: Invesco Nasdaq International Innovators 100 ETF (NASDAQ: QQI).
This new ETF builds on QQQ’s track record.
Pentagon Eyes 75-Year Rare Earth Deal With This Nasdaq Company (Ad)
The Pentagon is moving to cut US dependence on Chinese rare earth metals, and a Nasdaq-listed company just signed a term sheet for a potential 75-year agreement with the US Army.
The proposed deal would let the company build and operate a rare earth processing facility on an active military base, with the Army getting first right to production. New Pentagon restrictions on Chinese-origin rare earth magnets take effect January 1, 2027.
The company's mine-to-magnet platform covers feedstock agreements, processing, metallization, and downstream manufacturing, with commercial output targeted for 2027.
Read the full breakdown on this rare earth opportunity nowFor more than 25 years, QQQ—which now boasts more than $485 billion in assets under management (AUM)—has provided growth-focused investors with access to some of the market’s most innovative companies in a single basket.
However, while QQQ and QQQM track the Nasdaq-100 Index, which includes the 100 largest nonfinancial companies listed on the Nasdaq—many of them U.S.-domiciled firms—Invesco’s newest fund provides exposure to often-overlooked international growth stocks.
Invesco’s Expansion Into Global Growth Innovators
QQI expands the Invesco QQQ Innovation Suite with a global slant.
The fund is composed of large- and mid-cap companies across developed and emerging markets that Nasdaq identifies as innovators.
QQI seeks to replicate, as closely as possible, the performance of the Nasdaq International Innovators 100 Index, which tracks companies headquartered outside the United States.
Specifically, the index comprises firms that demonstrate innovative characteristics, including significant research and development (R&D) expenditures, revenue growth, gross margin growth, and measures of sustained profitability that could help shape the global economy.
These core tenets build on other ways of identifying innovators and go beyond many of the backward-looking metrics often used, such as earnings-per-share trends and long-term sales growth. The Nasdaq International Innovators 100 Index screens for five metrics organized around three innovation-based concepts:
-
Intentional investment in innovation: The index measures a company’s R&D expense as a percentage of annual sales, indicating its commitment to R&D as part of its corporate strategy.
-
Commercialization of R&D: The index calculates revenue growth and gross margin growth to identify companies that have successfully translated R&D spending into measurable business results.
-
Durable competitive positioning: The index calculates the three-year average gross margin and the three-year gross margin Sharpe ratio to help identify companies with sustained profitability over time.
For context, companies in the MSCI ACWI ex USA Index and the developed-markets-focused MSCI EAFE Growth Index spend approximately 5% of annual sales on R&D, while those in the broader MSCI EAFE Index spend around 3%. By comparison, companies in the Nasdaq International Innovators 100 Index devote approximately 13% of sales to R&D.
According to Invesco, “these measures help separate companies that have merely benefited from past growth from those actively investing in innovation and turning that investment into business performance.”
For investors, the approach offers international growth exposure that emphasizes not just innovation spending but also a company’s ability to translate that investment into profitable growth.
QQI’s Diverse Basket of Global Innovators
If QQI sounds like an ETF with a heavy bias toward tech, that’s because it is. Currently, 42% of the fund’s portfolio is allocated to that sector. But QQI also has significant allocations to healthcare (24.1%), industrials (8.8%), and consumer discretionary (7.1%).
QQI’s holdings are also geographically diverse, providing exposure to companies across developed and emerging markets, including Taiwan, China, Japan, South Korea, and several European countries. That geographic reach gives investors access to innovation beyond the United States, although the fund remains heavily concentrated in technology and other growth-oriented industries.
Among the fund’s top holdings—which, nearly a month after its debut, include $3.91 million in AUM—are several names familiar to growth investors. Taiwan Semiconductor Manufacturing (NYSE: TSM) is the ETF’s largest position, at 10.34% of the portfolio, followed by ASML Holding N.V. (NASDAQ: ASML) at 5.63%, SK hynix (NASDAQ: SKHY) at 4.59%, Roche Holding AG (OTCMKTS: RHHBY) at 4.24%, and Tencent Holdings Ltd. (OTCMKTS: TCEHY) at 3.82%.
The Fund’s Potential Upside Could Come With Growing Pains
As a new fund, QQI’s biggest concern is liquidity. Average daily volume is less than 11,500 shares. By comparison, an average of 47.88 million QQQ shares change hands daily. That difference could translate into wider bid-ask spreads and higher trading costs for QQI investors.
Another risk is volatility. Amid the current AI sell-off, ETFs that track tech-heavy indices could face increased selling pressure. While QQI is too new to assess, QQQ and QQQM both have betas of 1.22, meaning they are 22% more volatile than the broad S&P 500. QQI’s focus on international stocks in developed and emerging markets also introduces currency and geopolitical risks, which could contribute to greater volatility than in its Invesco counterparts.
Lastly, with a net expense ratio of 0.29%, the fund is more expensive than QQQ (0.18%) and QQQM (0.15%). But for investors looking to maintain growth exposure while diversifying away from potential concentration among U.S. innovators, QQI could be an ideal fit.
5 Stocks to Buy in November: Bargains Worth Giving Thanks For
By Thomas Hughes. First Published: 10/30/2026.
Key Points
- Spending fears have pushed several leading AI-related stocks to long-term lows despite improving fundamentals.
- Oracle, Salesforce, and Zscaler show growing backlogs, monetization, and cash flow, suggesting the market is undervaluing their long-term AI growth prospects.
- Applied Digital and Amprius Technologies present additional low-priced opportunities, backed by data center contracts, government grants, and upcoming earnings catalysts.
- Special Report: Why This Clean Energy Well Escaped the Solar and Wind Cuts.
November is nearly here, and many leading AI stocks have fallen to especially low prices. Concerns about spending have pushed many high-quality tech stocks to long-term lows, setting them up for potentially big rebounds.
The question is one of timing, and for many investors, now may be the time. Q2 results and news since then point to traction, monetization, and cash flow among leading AI-critical companies—all of which are expected to improve sequentially over the next six to eight quarters.
Oracle: This Market Is Pricing in a No-Growth Outlook
A free stock pick, from me to you (Ad)
Elon's paid this chip supplier since 2012. When NVIDIA tried to buy the company, he fought the deal.
Without its chip, his AI satellites don't fly. Now he wants 1,000,000 of them in orbit, 100 times what's up there today, and every one pays this company a royalty.
Dylan believes shares could react by December 8th.
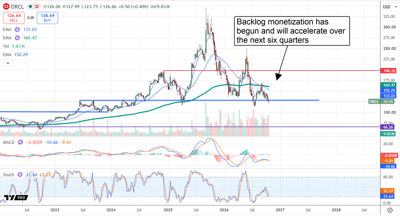
Claim this free stock pick before the December 8 deadline todayOracle (NASDAQ: ORCL) is a compelling buy in November because its growing debt has pushed its share price to long-term lows, as the market prices in little but risk and a no-growth outlook. The market continues to get it wrong: Oracle’s backlog is swelling, outpacing debt, and monetization has begun.
The Jupiter New Mexico project presents a potential hurdle to growth, but it accounts for only a small portion of the company's backlog. While the exact amount hasn’t been confirmed, it is estimated at approximately 3.5% of the backlog—a drop in a much larger bucket.
Monetization is the key. The company reported monetization of early AI investments in its fiscal Q1 2027 earnings report, boosting cash flow and adjusted margins to offset the impact of spending. The narrative for the remainder of 2026 and 2027 is that monetization will continue and accelerate, with a significant acceleration expected by year’s end.
Upcoming catalysts include the fiscal Q2 release, expected in early December, and a clearer view of Oracle’s strategy. The company leverages capital from clients, landlords, and partners to fund its buildout, so debt figures don’t tell the whole story. In this scenario, end-state infrastructure is far larger—and more valuable—than the market realizes.
Salesforce: Recovering From a Case of SaaS-Pocalypse Fear
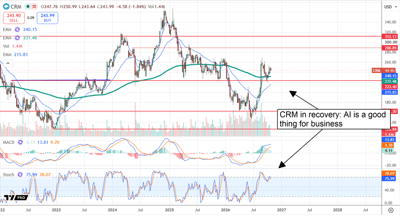
Salesforce (NYSE: CRM) is an attractive buy in November because the market has finally moved past its SaaS-Pocalypse fears and begun reevaluating the stock.
Salesforce is gaining traction with agentic AI, which depends on the company’s data capabilities. Like Oracle, which trades at an even deeper discount, Salesforce is valued as if it isn’t growing, outperforming, and generating reliable cash flow. Forward estimates put CRM at around 10 times the five-year consensus, suggesting at least 100% upside over the next few years.
Investors should not misread Salesforce’s position: It isn’t a high-growth engine anymore, though growth remains central to the outlook. It has transitioned into a mature, blue-chip tech powerhouse with reliable cash flow and capital returns.
Capital returns include a dividend but focus on share buybacks. Buybacks reduced the share count by 14% year over year in Q2, including through an accelerated repurchase plan. They are expected to continue at a brisk pace in the coming quarters, increasing shareholder leverage.
Zscaler: Regaining Market Confidence With AI Driving Business
Zscaler (NASDAQ: ZS) shares fell earlier this year after the company announced unexpected C-suite departures and reduced its guidance.
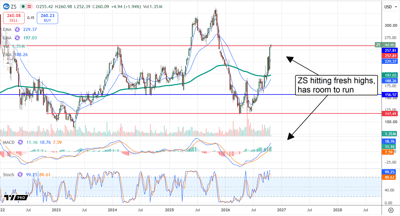
However, the company has recovered, hired new talent in its sales department, and reinvigorated market appetite for its stock. Key drivers include demand for its zero-trust architecture, its ability to secure AI, and its ability to generate free cash flow.
Analysts have been bullish on Zscaler as of late October and have reversed the downtrend in price targets. Their consensus price target implies modest downside, but analyst sentiment is firming, with targets trending toward the high end and the stock staging a significant technical breakout.
Valuation carries some risk. Trading above 50 times earnings, ZS isn’t a cheap stock, but its outlook is robust. Like Oracle and Salesforce, Zscaler trades at pennies on the dollar compared with long-term forecasts. It has become an execution story: It only needs to grow into its forecast for the stock to rise.
Applied Digital: Extreme Lows Are Extremely Attractive
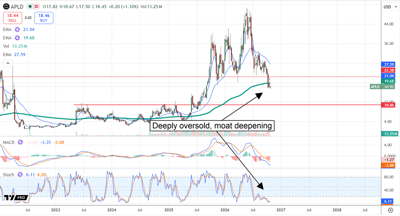
Applied Digital (NASDAQ: APLD) has risks, primarily related to debt and execution, but, like Oracle, it has begun to monetize AI assets and has a long runway ahead.
It is a compelling buy because of its low stock price and expected catalysts, including a capacity ramp, monetization, and adjusted results.
Investors should consider Applied Digital's moat. Its data center projects are backed by long-term contracts with hyperscale-quality clients. The business is also diversifying and has a first-mover advantage.
The company's data center projects face hurdles, but they are established, progressing, and supported by available power.
The focus is now on North Dakota, where power is ample, the local population is more welcoming, and there is room to expand.
Early projects and first-mover neoclouds are protected by increasingly high barriers to entry, including real estate, regulatory hurdles, power supply, environmental constraints, and local pushback. It will take time, but Applied Digital is well-positioned to monetize AI, generate cash flow for investors, and push its stock price to fresh highs.
Amprius Technologies: Execution Phase Has Begun
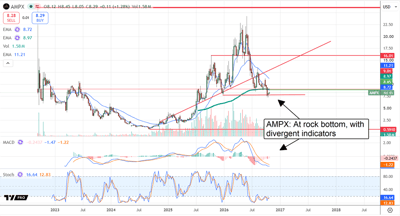
Amprius Technologies (NYSE: AMPX) is also trading at long-term lows, offering an attractive entry point as the company transitions from speculation to execution.
Production is ramping up, and a $75 million government grant is now in play to expand domestic battery manufacturing that meets National Defense Authorization Act sourcing requirements.
Upcoming results, including the mid-November Q3 release, will reflect these developments and provide further insight into revenue growth and profitability. Profitability is crucial, with a shift to adjusted profits expected over the coming year.
Catalysts for the share price include increased analyst coverage. More coverage matters for several reasons, including greater confidence, conviction, and institutional interest. Institutions follow analysts' lead and can quickly drive share prices higher. Institutional interest in AMPX is still tepid but could change quickly. News that validates the outlook could prompt analysts to take a closer look.
This email message is a sponsored message for Weiss Ratings, a third-party advertiser of MarketBeat. Why did I receive this email content?.
If you need help with your newsletter, feel free to contact MarketBeat's support team, based in the United States, at contact@marketbeat.com.
If you would no longer like to receive promotional emails from MarketBeat advertisers, you can unsubscribe or manage your mailing preferences here.
© 2006-2026 MarketBeat Media, LLC. All rights protected.
345 N Reid Place, Suite 620, Sioux Falls, South Dakota 57103-7078. U.S.A..



No comments:
Post a Comment