| Unsubscribe |
Below is an important message from one of our highly valued sponsors. Please read it carefully as they have some special information to share with you.
Dear reader,
A few years ago, every expert swore Elon Musk would never build a car that could drive itself.
A top federal safety adviser said, "you are never getting real self-driving."
Ford called the whole effort "vaporware."
But they were dead wrong. Today, Tesla's robotaxis pick up paying passengers, with no one in the driver's seat, in cities across America.
I have ridden in one myself.
Here’s why that matters to you, today:
Elon cracked self-driving by putting eyes on the car and letting it watch and learn from countless hours of footage. And he is about to unleash the exact same playbook on his next breakthrough.
He calls it his "infinite money glitch," and he predicts it will be the biggest product launch in history. I expect it will enter production as soon as October 21.
I have spent almost forty years investing in technology, and this is easily the biggest breakthrough I have covered yet.
I put the whole story into a short presentation. Watch it before October 21.
▶️ Watch the presentation here.
Regards,
James Altucher
These 4 Companies Are Monetizing AI Today
Reported by Thomas Hughes. Date Posted: 9/23/2026.
Key Points
- NVIDIA, Microsoft, Alphabet, and Palantir each successfully monetize AI through distinct strategies, protected by moats that safeguard future cash flow.
- NVIDIA leads through AI hardware and software sales, generating substantial cash flow that supports dividends, buybacks, and continued investment in future technology.
- Microsoft, Alphabet, and Palantir monetize AI via embedded cloud services, advertising strength, and safe orchestration for enterprises and governments, respectively.
- Special Report: The Untouched Energy Source Behind a New Eight Year Tax Break
Monetizing AI matters for many reasons, including recapturing hundreds of billions of dollars in infrastructure spending, advancing technology and, of course, generating profits. The challenge is that AI monetization requires a delicate balance between upfront costs, continued research and user adoption—and adoption may be the greatest risk of all.
While the upfront research costs are enormous, they can be mitigated if users embrace the technology. The risk lies in driving usage too far, too fast, potentially eroding confidence in AI’s capacity and capabilities. Companies monetizing AI today share several qualities, including proven utility for consumers and the ability to innovate in their respective arenas. More importantly, each has a moat that helps protect future cash flow.
No Company Monetizes AI Like NVIDIA
Forbes calls this a "golden era" for retirement income (Ad)
Forbes recently called a new category of exchange-traded income funds a 'golden era,' and Bloomberg noted the eye-popping yields are fueling a boom among everyday investors. Three years ago, barely a dozen of these funds existed - today there are more than 100, holding over $140 billion.
These funds trade on the NYSE and NASDAQ and are built to generate monthly income. Some investors are targeting $5,000 a month with roughly one-tenth of the nest egg Wall Street says you need.
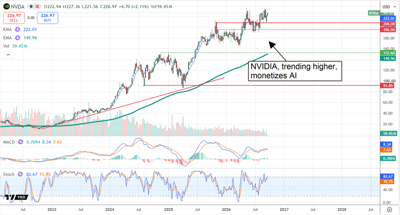
Watch the short briefing to see how this income approach worksNVIDIA (NASDAQ: NVDA) is the hands-down winner when it comes to monetizing AI, providing both the hardware and full-stack software needed to run it.
Hardware is the primary source of revenue, including GPUs and the networking equipment that connects them into clusters. It drives most of NVIDIA’s revenue and earnings, but other avenues include royalties, revenue sharing and investments in future technology.
Royalties and revenue sharing are linked to neoclouds and startups that provide third-party services using NVIDIA technology. Investments in future technology create a circular advantage, keeping NVIDIA ahead of the curve while helping GPU customers maintain access to capital.
The impact on NVIDIA’s cash flow is substantial and reflected in its balance sheet. Its cash pile has grown over the past few years and remained high at more than $50.5 billion as of Q2, despite aggressive investments. This enables a token dividend, dividend increases and share buybacks, which incrementally reduce the share count. Looking ahead, NVIDIA is likely to continue generating strong cash flow and sustaining capital returns over time.
Microsoft Leads With Embedded Services
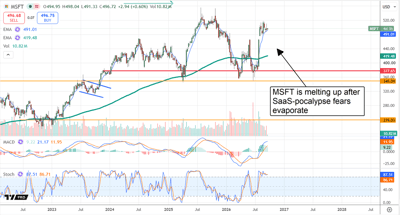
While it garners less attention than other AI companies, Microsoft (NASDAQ: MSFT) leads in monetizing AI applications.
Microsoft is embedding AI throughout its ecosystem, using it as both an incentive and an upsell to drive business.
Recent earnings results included an overall beat, accelerating growth in the cloud segments and strength in Azure, the company’s cloud infrastructure business, which generated more than $100 billion in annual revenue for the first time.
Looking ahead, analysts forecast that Microsoft will sustain modest single-digit growth while steadily widening margins over the next five to 10 years.
Like NVIDIA, Microsoft uses its cash flow to maintain financial health, reinvest in new technology and return capital to shareholders. It also pays a token, albeit slightly larger, dividend while incrementally reducing its share count. Forty-seven analysts rate MSFT as a Moderate Buy, with approximately 15% upside as of late September, compared with NVIDIA’s Buy rating and 40% upside potential.
Alphabet Taps Consumers to Monetize AI
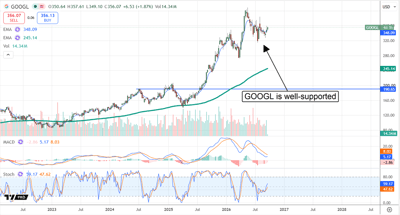
Alphabet (NASDAQ: GOOGL) monetizes AI in many ways, including through software, infrastructure and services, but its primary driver is the advertising business.
AI increases both clicks and their quality, which is reflected in the company’s results. First-half 2026 results included the sixth and seventh consecutive quarters of accelerating revenue growth, along with outperformance and strong guidance. Second-quarter revenue increased nearly 25% year over year.
The Services segment, which accounts for about 90% of the business, underpins the results and is supported by strength in Cloud. Google Cloud grew more than 80%, driven by strength across all business lines.
Alphabet, too, pays a token dividend and incrementally reduces its share count. A healthy balance sheet, low and manageable debt, and relatively unimpeded cash flow offset its tepid return. These factors limit risk, provide some insulation amid higher interest rates and give institutional investors a reason to buy.
Palantir Monetizes AI Safety
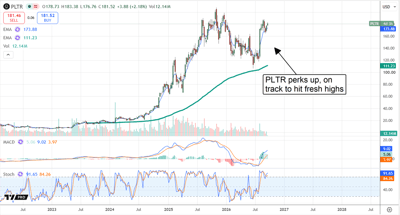
Palantir (NASDAQ: PLTR) monetizes AI in many ways, but first and foremost as an orchestration layer that allows businesses and governments to access AI safely.
Its moat lies in compliance and its Ontology, the data layer beneath its AIP platform. It keeps data safe and secure while creating easy-to-follow roadmaps for AI. Palantir’s products not only make AI safer but also make it more useful, driving widespread adoption. Catalysts in 2026 include accelerating revenue growth and profitability.
Palantir is returning capital, but at an even slower pace, choosing to offset share-based compensation while preserving capital for growth initiatives. The company has an aggressive go-to-market strategy focused on onboarding clients and developing solutions before they commit. The strategy works, translating into long-term contracts and rapidly improving revenue visibility.
Analyst trends reflect these strengths, with coverage increasing, sentiment firming and price targets trending higher. The consensus price target forecasts only modest upside, but the trend matters, with the high-end price target implying fresh all-time highs. Institutions are buying and supporting the stock’s price action.
3 Software Stocks Rebounding as AI Fears Give Way to Growth
Reported by Leo Miller. Date Posted: 9/21/2026.
Key Points
- Atlassian, Salesforce, and Dynatrace were all hit by fears that AI could erode demand for traditional software, but each has staged a sharp rebound in 2026.
- Fresh results suggest enterprise AI adoption may be creating new demand for collaboration, CRM, and observability tools rather than simply replacing them.
- Rovo adoption, Claudeforce monetization, and Dynatrace’s net revenue retention will help show whether those rebounds are backed by durable growth.
- Special Report: The Untouched Energy Source Behind a New Eight Year Tax Break
Early in 2026, markets viewed software stocks as among the biggest losers from AI adoption. The advent of “vibe coding” largely drove this view, as it significantly increased software development productivity. This led to fears that traditional software companies would face intense competition, eroding their businesses.
While this argument is neither entirely correct nor entirely incorrect, many key software companies are demonstrating their ability to benefit from enterprise AI adoption rather than suffer from it. Several have rebounded sharply as investors reassess those risks.
Atlassian Rises From the Ashes
The $15 Gold Fund That Pays Up to $1,152/Month (Ad)
Gold is hitting record highs, but most investors are leaving income on the table. A $15 fund is quietly paying out up to $1,152 a month to regular investors - no mining stocks, no options, no physical metal required.
Chief Income Strategist Tim Plaehn calls it a breakthrough strategy that transforms gold's rally into reliable monthly payouts. The next distribution is just days away.
Discover the gold income fund before the next payout dateProductivity software company Atlassian (NASDAQ: TEAM) has arguably seen the most dramatic shift in sentiment of any software stock in the market. Notably, through mid-April 2026, shares were down more than 60% year to date (YTD).
One factor behind this decline was the idea that AI coding tools would reduce employment among software engineers. This could hurt demand for Atlassian’s key products, such as Jira, which helps manage software development and charges based on the number of licenses a company buys.
However, it appears that AI adoption is actually increasing demand for Atlassian’s products, as companies need more help coordinating across teams to implement AI. In its latest quarter, the company signed a record number of $1 million, $3 million and $5 million deals.
Its Rovo AI assistant is also gaining significant traction. The company notes that more than 80% of Fortune 500 companies use Rovo. Additionally, Rovo-assisted actions increased by 50% in just one quarter, while Rovo adopters increased their annual recurring revenue (ARR) commitments more than twice as fast as non-Rovo adopters. Amid this success, shares have rebounded sharply from their spring lows.
Salesforce New Order Value Growth Hits 4-Year High
The tide has also turned in a big way for software giant Salesforce (NYSE: CRM). Through June 2026, Salesforce shares were down approximately 40%, driven by fears that AI would disrupt its seat-based model. However, the company’s latest earnings strongly pushed back against this idea, and shares have recovered much of their earlier 2026 losses.
Last quarter, the company noted that growth in its net new annual order value (NNAOV) was the strongest in four years. NNAOV measures the annual contract value from customers who entered subscriptions during the period. In other words, Salesforce is saying that the size of new customer commitments is rising at a pace not seen in years. This contradicts the idea that AI would hurt demand for Salesforce’s products.
Meanwhile, the company is finding ways to drive AI-related growth. Notably, its Agentforce offering reached $1.5 billion in ARR last quarter, up 240% year over year (YOY). The company also announced Claudeforce, its product collaboration with Anthropic, indicating that AI models and Salesforce’s products can be complementary.
Dynatrace Is Winning on AI Observability Demand
Last up is Dynatrace (NYSE: DT). The stock fell considerably less than TEAM and CRM earlier in 2026, declining around 25% through mid-April. However, shares have rallied sharply from their mid-April lows.
Dynatrace is a key player in the observability market, which is rapidly expanding as enterprises implement AI. Using AI agents means that enterprises must be able to monitor and correct their performance, a need that Dynatrace’s observability platform addresses. Dynatrace says that 1,000 customers used its platform to observe AI and LLM workloads in production last quarter, up 17.6% from the previous quarter.
Amid this growth, the company achieved record new-customer, or logo, growth of 160% last quarter. Looking ahead, Dynatrace expects the AI observability market to exceed $10 billion by 2030, growing by more than 50% annually. This represents just a portion of the $92 billion total addressable market Dynatrace sees, which includes core observability and application security.
Watch Items Across Atlassian, Salesforce, and Dynatrace
Increased adoption of Rovo will be an important indicator for Atlassian going forward. Given that Rovo adopters are increasing their spending more than twice as fast as non-adopters, continued adoption would reflect favorably on Atlassian’s future growth potential.
For Salesforce, a key watch item will be how Claudeforce adoption affects the company’s growth, as it is unclear how Salesforce and Anthropic will share the resulting revenue. If user growth is strong but Salesforce’s revenue receives a limited uplift, it would suggest that Anthropic is benefiting disproportionately.
Dynatrace’s net revenue retention rate (NRR) is another key metric to watch. It stood at 110% last quarter, meaning existing customers spent 10% more year over year. Management expects NRR to improve in the second half of fiscal year 2027. If it does, that would signal stronger expansion among existing customers as Dynatrace capitalizes on rising AI observability demand.
This email message is a paid sponsorship from Paradigm Press, a third-party advertiser of MarketBeat. Why did I receive this email message?.
If you have questions about your account, feel free to contact our South Dakota based support team at contact@marketbeat.com.
If you would no longer like to receive promotional emails from MarketBeat advertisers, you can unsubscribe or manage your mailing preferences here.
© 2006-2026 MarketBeat Media, LLC.
345 N Reid Place, Suite 620, Sioux Falls, S.D. 57103-7078. USA..



No comments:
Post a Comment