| Unsubscribe |
Dear Reader,
You're probably hearing all kinds of wild rumours about the best way to play AI right now...
The SpaceX IPO created 4,400 new millionaires... and OpenAI is reportedly planning its own $1 trillion IPO as early as this fall, which is expected to create even more overnight millionaires...
While early holders of Nvidia have had the chance to make millions of dollars on just one stock. (One schoolteacher in New Hampshire retired early after making $2,545,000 on the stock.)
MIT says right now is the best time in history to become wealthier, thanks to AI.
But the truth is...
The best way for ordinary folks to take advantage from what's happening isn't to speculate on AI IPOs... or try to guess which stock will be the "next Nvidia".
It's simply to hold these five stocks.
Put simply, our system (which is built on an AI platform pioneered by Google) ranks every stock in the S&P 500...
And narrows everything down to just five names.
There are no complex charts to read. No spending hours in front of a computer screen. No guesswork.
All you do is buy five stocks, then hold them for a month.
Our backtests show this simple approach could make you 1,000% on your money, without ever ‘holding and hoping' AI stocks themselves.
And it could grow your money much faster than the market.
For instance, in August you'd have made 4x more money holding just our Top Five Stocks, compared to the S&P 500.
That's why I'm trying to share my free demo with as many folks as possible, while there's still time to try this out for yourself.
Everything you need to know is here.
Regards,
Keith Kaplan
CEO, TradeSmith
P.S. Sam Altman says AI will be "as essential as electricity" in the future. That's a very grand claim. But it doesn't tell you where your money should be for the best chance to profit and avoid falling behind.
That's why I'm urging you to try our new AI tool now and potentially grow your money 10x using just five stocks.
3 Defense Stocks Riding Nuclear, Missile, and Aerospace Demand
Written by Nathan Reiff. Originally Published: 9/26/2026.
Key Points
- Rising global defense spending on military modernization and nuclear deterrence creates opportunities for both large and small defense-related companies.
- BWX Technologies and Mercury Systems both reported strong backlog growth and raised guidance, reflecting robust demand for their specialized defense niches.
- Howmet Aerospace continues posting strong revenue growth and pursuing acquisitions despite facing new competition from GE Aerospace's purchase of a rival supplier.
- Special Report: Trump goes "all-in" on Grand Canyon energy breakthrought.
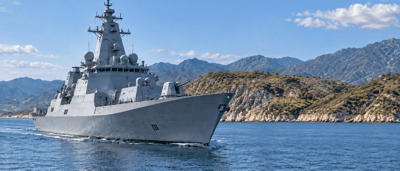
The United States and other governments around the world are prioritizing military modernization, building their nuclear deterrence capabilities, enhancing missile defense systems and investing heavily in defense overall. The shift toward a more militarized world may give investors opportunities to capitalize on both large defense contractors and smaller companies with significant growth potential.
When seeking substantial returns in the defense sector, investors may want to look for firms with unique technological niches, distinct positions within the defense supply chain and significant operational updates or other signs of business momentum. BWX Technologies Inc. (NYSE: BWXT), Mercury Systems Inc. (NASDAQ: MRCY) and Howmet Aerospace Inc. (NYSE: HWM) may all be appealing candidates for these reasons.
BWX Finds a Lucrative Niche in Nuclear Propulsion
The $15 Gold Fund That Pays Up to $1,152/Month (Ad)
Gold is hitting record highs, but most investors are leaving income on the table. A $15 fund is quietly paying out up to $1,152 a month to regular investors - no mining stocks, no options, no physical metal required.
Chief Income Strategist Tim Plaehn calls it a breakthrough strategy that transforms gold's rally into reliable monthly payouts. The next distribution is just days away.
Discover the gold income fund before the next payout dateBWX is a nuclear component maker that serves the nuclear energy market, medical customers and the U.S. government. In particular, its work designing nuclear reactors and components for naval vessels has made it a major player in the U.S. Navy's nuclear propulsion program.
This has led to noteworthy demand and a growing backlog, which climbed 40% year over year (YOY) to $8.4 billion in the latest quarter.
BWX's niche relationship with the U.S. Navy has also boosted its top and bottom lines. Second-quarter 2026 revenue climbed 18% to approximately $902 million, just shy of analyst estimates. Adjusted EBITDA and adjusted earnings per share (EPS) also increased YOY, and the company's leadership raised its full-year guidance in response.
There's reason to believe this momentum could continue and potentially reverse BWXT stock's downward performance trend. (Shares have fallen about 20% so far in 2026.) Over the summer, the company secured a contract with the National Nuclear Security Administration to develop a new lithium processing facility.
Additionally, BWX is narrowing its focus by selling its medical business for up to $800 million. The transaction would provide a substantial boost to its capital reserves while allowing the company to prioritize its highest-potential operations.
Mercury's Financials Continue to Improve as Defense Moves Toward Software
Mercury's role in the defense industry is different. The company provides secure processing hardware, computer equipment, sensors and other subsystems for aircraft, missiles and radar systems. As the defense industry increasingly shifts toward software and electronics, Mercury may have an increasingly important role to play.
Like BWX, Mercury reported impressive bookings and backlog in its latest quarter. Bookings rose 93% YOY to $660 million, while backlog approached $2 billion. The company also raised its forward guidance and now expects fiscal 2027 revenue to reach nearly $1.1 billion.
Mercury is improving its margins, with its adjusted EBITDA margin climbing 217 basis points last quarter to 15.3%.
Shares of MRCY have performed differently from BWXT stock, rising about 14% year to date (YTD) despite shedding approximately 7% over the past month. As the company demonstrates that it can continue addressing manufacturing inefficiencies while maintaining strong revenue growth, it may better justify analysts' optimistic views of the stock, including projections for approximately 33% potential upside.
Howmet Holds Its Own Against GE
Perhaps best known for its engineered components for commercial aerospace applications, Howmet continues to expand its offerings for the defense sector as well.
The company may present a buy-the-dip opportunity for investors following news that GE Aerospace (NYSE: GE) would spend $12 billion to acquire Consolidated Precision Products, a rival aerospace component maker. While the move appears to threaten Howmet's share of the customer base, significant capacity shortages across the industry may allow both companies to benefit from strong demand for years to come.
Even after a 13% decline over the past month, HWM stock remains up 12% YTD, suggesting that investors see strength in the company's operations and financials. In the latest quarter, that strength was reflected in strong top- and bottom-line results that exceeded analyst expectations, including 24% YOY revenue growth driven by broad-based demand.
Howmet also benefits from data center demand, which has driven interest in its gas turbines. The company is pursuing consolidation as well. Like GE, Howmet made a major acquisition earlier this year of Consolidated Aerospace Manufacturing. The deal expands both its manufacturing capacity and product offerings. Howmet could continue to benefit from the essential nature of the products it supplies to commercial and military aircraft.
3 Software Stocks Rebounding as AI Fears Give Way to Growth
Written by Leo Miller. Originally Published: 9/21/2026.
Key Points
- Atlassian, Salesforce, and Dynatrace were all hit by fears that AI could erode demand for traditional software, but each has staged a sharp rebound in 2026.
- Fresh results suggest enterprise AI adoption may be creating new demand for collaboration, CRM, and observability tools rather than simply replacing them.
- Rovo adoption, Claudeforce monetization, and Dynatrace’s net revenue retention will help show whether those rebounds are backed by durable growth.
- Special Report: Trump goes "all-in" on Grand Canyon energy breakthrought.
Early in 2026, markets viewed software stocks as among the biggest losers from AI adoption. The advent of “vibe coding” largely drove this sentiment, as it significantly increased software development productivity. This led to fears that traditional software companies would face intense competition, eroding their businesses.
While this view is neither entirely correct nor entirely incorrect, many key software companies are demonstrating their ability to benefit from enterprise AI adoption rather than suffer from it. Several have rebounded sharply as investors reassess those risks.
Atlassian Rises From the Ashes
This will be bigger than SpaceX (Ad)
James Altucher once called Facebook's rise to a hundred-billion-dollar valuation and Apple's run to a trillion while experts laughed. Now he is making what he calls his biggest prediction yet.
It centers on new drone footage from one of Elon Musk's expanding production facilities, tied to a product Musk reportedly calls an infinite money glitch, with production possibly starting in days.
Altucher cites Dallas Fed data suggesting the opportunity could approach 2 quadrillion dollars by 2040.
Watch the full presentation before the factory goes liveProductivity software company Atlassian (NASDAQ: TEAM) has arguably seen the most dramatic shift in sentiment among software stocks. Through mid-April 2026, shares were down more than 60% year to date (YTD).
One factor behind this decline was the idea that AI coding tools would reduce employment among software engineers. This could hurt demand for Atlassian’s key products, such as Jira, which helps manage software development and charges based on the number of licenses a company buys.
However, AI adoption appears to be increasing demand for Atlassian’s products, as companies need more help coordinating across teams as they implement AI. In its latest quarter, the company signed a record number of $1 million, $3 million and $5 million deals.
Its Rovo AI assistant is also gaining significant traction. The company notes that more than 80% of Fortune 500 companies use Rovo. Additionally, Rovo-assisted actions increased by 50% in a single quarter, and Rovo adopters increased their annual recurring revenue (ARR) commitments more than twice as fast as non-Rovo adopters. Amid this success, shares have rebounded sharply from their spring lows.
Salesforce New Order Value Growth Hits a Four-Year High
The tide has also turned in a big way for software giant Salesforce (NYSE: CRM). Through June 2026, Salesforce shares were down approximately 40%, driven by fears that AI would disrupt its seat-based model. However, the company’s latest earnings strongly pushed back against this idea, and shares have recovered much of their earlier 2026 losses.
Last quarter, the company noted that growth in its net new annual order value (NNAOV) was the strongest in four years. NNAOV measures the annual contract value from customers who entered subscriptions during the period. In other words, Salesforce is saying that the size of new customer commitments is rising at a pace not seen in years. This contradicts the idea that AI would hurt demand for Salesforce’s products.
Meanwhile, the company is finding ways to drive AI-related growth. Notably, its Agentforce offering reached $1.5 billion in ARR last quarter, up 240% year over year (YOY). The company also announced Claudeforce, its product collaboration with Anthropic, indicating that AI models and Salesforce’s products can be complementary.
Dynatrace Is Winning on AI Observability Demand
Last up is Dynatrace (NYSE: DT). The stock fell considerably less than TEAM and CRM earlier in 2026, declining around 25% through mid-April. However, shares have rallied sharply from their mid-April lows.
Dynatrace is a key player in the observability market, which is rapidly expanding as enterprises implement AI. Using AI agents means enterprises must be able to monitor and correct their performance, a need that Dynatrace’s observability platform addresses. Dynatrace says that 1,000 customers used its platform to observe AI and LLM workloads in production last quarter, up 17.6% in a single quarter.
Amid this growth, the company achieved record new-customer growth, also called logo growth, of 160% last quarter. Looking ahead, Dynatrace expects the AI observability market to exceed $10 billion by 2030, growing by more than 50% annually. This represents just a portion of the $92 billion total addressable market Dynatrace sees, which includes core observability and application security.
Watch Items Across Atlassian, Salesforce and Dynatrace
Increased adoption of Rovo will be an important indicator for Atlassian going forward. Given that Rovo adopters are increasing their spending more than twice as fast as non-adopters, continued adoption would support Atlassian’s future growth potential.
For Salesforce, a key watch item will be how Claudeforce adoption affects the company’s growth, as it remains unclear how Salesforce and Anthropic will share the resulting revenue. If users grow strongly but Salesforce’s revenue receives a limited uplift, it would suggest that Anthropic is benefiting disproportionately.
Dynatrace’s net revenue retention rate (NRR) is another key metric to watch. It stood at 110% last quarter, meaning existing customers spent 10% more year over year. Management expects NRR to improve in the second half of fiscal year 2027. If it does, that would signal stronger expansion among existing customers as Dynatrace capitalizes on rising AI observability demand.
This message is a sponsored message for TradeSmith, a third-party advertiser of MarketBeat. Why did I receive this email?.
This ad is sent on behalf of TradeSmith at 1125 N. Charles Street, Baltimore, Maryland 21201. If you’re not interested in this opportunity, please click here.
If you have questions or concerns about your subscription, please feel free to email our South Dakota based support team at contact@marketbeat.com.
If you would no longer like to receive promotional emails from MarketBeat advertisers, you can unsubscribe or manage your mailing preferences here.
© 2006-2026 MarketBeat Media, LLC. All rights protected.
345 N Reid Place, Suite 620, Sioux Falls, S.D. 57103-7078. United States..



No comments:
Post a Comment