| Unsubscribe |
Dear Reader,
According to the shocking new prediction from Marc Chaikin...
Elon Musk's empire is doomed.
He just doesn't know it yet.
Bottom line for U.S. investors?
Those who understand what's coming could sidestep disaster...
While pocketing the biggest windfall in history, starting now.
AI investors who ignore what's coming could "lose all," he says.
That may sound hard to believe, but keep in mind...
Chaikin is a 60-year Wall Street legend.
His former client list has included multiple billionaires.
They have names like Paul Tudor Jones...
Steve Cohen, owner of the Mets...
Michael Steinhardt, of Steinhardt Partners...
And George Soros, founder of Quantum Fund...
His Chaikin Money Flow indicator is built into every Bloomberg terminal.
You could have followed his 20-factor Power Gauge system into Micron...
- Before the stock climbed 970% in one year...
- And into Celestica, before that AI stock soared 6,600%...
- And Nvidia, before it soared more than 50,001%...
As Mad Money host Jim Cramer says: "I learned a long time ago not to be on the other side of a Chaikin trade."
Chaikin's newest trade involves this radical new AI technology...
Launching before the end of 2026...
An innovation that will render all current AI data centers obsolete when it comes to major AI breakthroughs. (And yes, that includes Elon's Colossus data center in Tennessee.)
Called "micro cluster" technology, these next-gen data centers take up 99% less space.
They take up 99% less electricity and water.
Yet they're more than 1 trillion times more powerful than the #1 data center on earth today.
Marc's research shows that when this replacement technology launches by the end of the year...
- It'll help to solve the data center bottleneck in America.
- It'll render Elon's Colossus obsolete when it comes to major breakthroughs.
- It'll shrink breakthrough times from 5 years to 5 days (360X acceleration).
- And it could make early investors very, very, VERY rich, starting now.
The U.S. government is quietly pouring billions into the company behind this breakthrough right now.
But the story has yet to break open in the mainstream media.
Meaning there's still time to get in early.
Click this link now for Chaikin's full research... including the name and ticker of the company behind this coming breakthrough.
Fair warning: This video contains timely information, including a detailed recommendation.
Chaikin reserves the right to take it offline at any moment.
Sincerely,
Vic Lederman
Publisher, Chaikin Analytics
P.S. We recommend checking out Marc's presentation right now. Drop whatever you're doing. When this company's new AI tech launches, it'll render all current AI tech virtually obsolete – instantly. How? By accelerating AI breakthrough times 360X. (Breakthroughs that were supposed to come in 5 years could come in 5 days.) The time to invest is now, he says. And he reveals the full story – and stock ticker – here, for free. Don't delay. This launch will happen before the end of this year.
AI Uncertainty Is Rising, But These 3 Chip ETFs Still Have Momentum
By Nathan Reiff. First Published: 9/30/2026.
Key Points
- Despite concerns about slowing AI development, semiconductor demand may remain resilient, making diversified ETFs an appealing way to gain exposure while managing risk.
- The iShares Semiconductor ETF and Invesco PHLX Semiconductor ETF both offer broad, passively managed exposure to major chipmakers, with SOXX up over 80% and SOXQ up 78% year to date.
- The actively managed Roundhill Memory ETF has grown rapidly amid a memory shortage, delivering 121% returns since its April 2026 launch.
- Special Report: The Last Energy Revolution Starts Now
It's easy to get skittish about the tech sector amid recent talk of slowing AI development and OpenAI scrapping the launch of its latest model due to safety concerns. AI demand has driven much of the sector's growth in recent years, after all. Still, talk of an AI slowdown doesn't necessarily mean semiconductor demand overall will decline—some parts of the industry are more exposed to AI infrastructure spending than others.
Further, AI-related capital spending on hardware may remain elevated even if technological growth moderates. In this environment, semiconductor makers with multiple growth drivers could stand out, alongside critical networking and connectivity firms, major foundries and other industry players.
This AI fund sends investors payouts every Thursday (Ad)
CrowdStrike, Palantir, Nvidia none of them pay a real dividend. But one fund holding the biggest AI names distributes income every single Thursday, with payouts reported as high as $1,051 a month.
Chief Income Strategist Tim Plaehn breaks down the fund's real Thursday distribution history, how the income is generated, and how to buy it in any brokerage account.
Watch the free presentation before this Thursday's payoutOne of the more appealing ways to remain exposed to the semiconductor industry amid this volatility while also attempting to moderate risk is through a diversified exchange-traded fund (ETF). The funds below each offer a somewhat different way to play this corner of the market.
Tried-and-True Exposure to Some of the Largest Chipmakers
One of the cornerstones of the semiconductor ETF space, the $48 billion iShares Semiconductor ETF (NASDAQ: SOXX) appeals to investors seeking broad exposure to the semiconductor manufacturing industry.
Most of the fund is allocated to mid- and large-cap stocks, giving it exposure beyond the biggest names and potentially increasing volatility as a result.
The growth potential of some of these smaller firms may appeal to investors who believe the industry is not yet fully developed.
Still, SOXX has a narrow portfolio of just 34 total companies, with major producers like Intel Corp. (NASDAQ: INTC) and Advanced Micro Devices Inc. (NASDAQ: AMD) each accounting for more than 9% of assets.
This concentration at the top prioritizes the largest chipmakers, which works well when the overall industry is experiencing strong demand but may limit growth potential.
That said, SOXX is still up more than 80% year to date (YTD), an appealing return for a fund with an annual fee of 0.33%. This may help explain why the fund is so popular.
Fast-Growing Memory Hardware Fund With Stellar Returns
A memory shortage has meant record-breaking growth for the Roundhill Memory ETF (BATS: DRAM), which has grown to $27 billion in assets under management and maintains similarly robust trading volume.
One benefit of this fund is its easy access to many of the world's largest chipmakers. Its 19 holdings include major firms from Korea, Taiwan and other regional industry hubs.
DRAM has traded only since April 2026, making it one of the newer tech hardware funds. However, its rapid ascent in popularity has accompanied returns of 121% since launch. Investors may be drawn to the fund's active management style, which allows it to quickly adapt its portfolio to changing market conditions.
Its international exposure in a single trade is another perk. Still, the fund remains largely untested in more challenging market environments.
An Alternative to SOXX With Heavier Concentrations, Lower Fees
The Invesco PHLX Semiconductor ETF (NASDAQ: SOXQ) is similar to SOXX in several ways—both have significant exposure to the largest names in the semiconductor industry and follow a passive management approach.
SOXQ distinguishes itself in terms of portfolio weighting and cost. SOXX may be slightly more balanced, while SOXQ tends to weight its largest positions somewhat more aggressively. NVIDIA Corp. (NASDAQ: NVDA), for example, makes up more than 11% of the basket, a higher allocation than any single stock in SOXX's portfolio. Still, the fund remains similarly diversified in terms of its total number of positions.
SOXQ also comes in significantly cheaper than SOXX, with an expense ratio of just 0.19%. Nonetheless, SOXX tends to have better liquidity, which may offset the fee difference for more active traders. SOXQ may appeal more to investors interested in buying and holding a semiconductor fund.
Overall, these two funds are very similar and have significant portfolio overlap. Still, subtle but important distinctions between them may cause them to appeal to different investors. SOXX may draw those who believe AI enthusiasm is too heavily concentrated in a handful of mega-cap names, for example, while SOXQ may be preferable for hands-off investors content to focus on the largest companies. SOXQ's YTD returns of 78% are slightly below SOXX's over the same period, but both funds have drastically outperformed the broader market this year.
Six Flags Launches FlexPay—Is There Any FUN Left in the Stock?
By Chris Markoch. First Published: 9/28/2026.
Key Points
- Activist investor JANA Partners is pressing Six Flags' board to explore a sale after weak second-quarter results and a 45% stock decline.
- Six Flags launched Flex Pay, a buy-now-pay-later financing option with up to 36% APR, shortly after missing Q2 2026 earnings and revenue expectations.
- Despite a heavy debt load near $4.9 billion against a $1.2 billion market cap, analysts still see roughly 85% upside to their consensus price target.
- Special Report: The Last Energy Revolution Starts Now
Six Flags Entertainment (NYSE: FUN) has launched Flex Pay by Upgrade. This buy-now, pay-later (BNPL) solution offers consumers a pay-over-time option for eligible online purchases of $49 or more, including season passes. Approved guests can activate their season passes immediately and begin visiting the parks while making fixed monthly payments.
The initiative comes after the company announced disappointing Q2 2026 earnings in August. Six Flags posted earnings per share (EPS) of 14 cents, while analysts had expected EPS of 29 cents. Revenue also came in light at $864.92 million, compared with the $929.31 million analysts had forecast.
This will be bigger than SpaceX (Ad)
James Altucher once called Facebook's rise to a hundred-billion-dollar valuation and Apple's run to a trillion while experts laughed. Now he is making what he calls his biggest prediction yet.
It centers on new drone footage from one of Elon Musk's expanding production facilities, tied to a product Musk reportedly calls an infinite money glitch, with production possibly starting in days.
Altucher cites Dallas Fed data suggesting the opportunity could approach 2 quadrillion dollars by 2040.
Watch the full presentation before the factory goes liveIn addition to missing expectations, both figures were lower year over year. Six Flags' net loss more than doubled to $202.6 million from $99.6 million a year earlier. That's troubling because the company's second and third quarters are typically its strongest based on seasonal factors. It also raises questions about what consumer health could mean for the company's outlook.
FUN is down 45% over the past 12 months. Now, an activist investor wants the board to consider selling the company. That leaves investors weighing a slow turnaround against the possibility of a buyout premium.
Flex Pay Arrives at a Telling Time
The theme park operator is announcing Flex Pay during the company's softer time of year. Many of its theme parks are about to close until next spring, meaning investors shouldn't read too much into Flex Pay's initial results.
The timing stands out for another reason. Flex Pay went live on Sept. 7, the same day promotional pricing on 2027 season passes was set to expire. Six Flags appears to be using financing to keep pass sales moving after the discount window closed.
Investors should understand what Flex Pay is. It isn't an in-house payment plan; it's a loan from Upgrade's lending partners. Approval depends on a credit check, and APRs range from 0% to 36%, depending on the borrower.
That's a sharp contrast with the industry's biggest names. Universal and Disney (NYSE: DIS) both let annual passholders pay over time without interest, though Disney restricts its plan to Florida residents. Six Flags is marketing Flex Pay as a value tool, but budget-conscious families may feel differently if they have to pay interest on their purchases.
Can Financing Fix a Demand Problem?
A larger concern is why the company is failing to attract consumers. Theme parks like Six Flags tend to be somewhat defensive. First, the parks are within driving distance for most guests. Second, they generally offer good value.
However, higher gas prices are causing some consumers to put off theme park trips, which come with their own on-site costs. That's where Flex Pay could make a difference. But is it too little, too late for investors?
Six Flags May Go Private
JANA Partners is leading a group of activist investors pressing Six Flags to explore a sale, which could include a take-private deal. On Sept. 22, JANA urged the board to hire an investment bank to run that process, citing frustration with the company's second-quarter results.
JANA isn't new to this story. The fund built a roughly 9% stake alongside co-investors last fall, worth around $200 million at the time. That group included Kansas City Chiefs tight end Travis Kelce, who later signed on as a Six Flags brand ambassador. JANA's original demands covered marketing, the park experience, technology, leadership changes and a review of a possible sale.
The case for going private comes down to the balance sheet. Net debt stands at roughly $4.9 billion, while the company's market capitalization is about $1.2 billion. With debt near four times its equity value, a buyer's premium may look better than waiting for a multi-year turnaround.
There are reasons for investors to proceed with caution. The 2024 merger of Cedar Fair and Six Flags promised synergies that haven't materialized. History also offers a warning. Red Zone's 2005 takeover of Six Flags promised a brand revival but ended in bankruptcy in 2009.
Investors Aren't Thrilled
Flex Pay hasn't given Six Flags stock a lift. Shares fell about 26% in the month leading up to JANA's letter. The report then sparked a 5.4% after-hours pop. However, shares are still trading near five-year lows. A troubling sign for investors is that FUN continues to trend lower, even below its descending 50-day simple moving average (SMA).
Retail investors will have to overcome short interest of around 21%. However, some factors are working in buyers' favor, including the stock's relative strength index (RSI) tipping into oversold territory and a high percentage of institutional ownership.
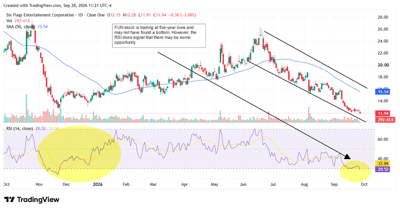
Analyst price targets have been moving lower since the company's disappointing Q2 earnings report in August. However, the consensus price target for FUN is $21.50, which represents about 85% upside.
The fundamentals still point to a long, expensive turnaround. But the possibility of a sale gives FUN a potential floor it didn't have a month ago. If the board hires bankers, the debate shifts from attendance to takeover value.
Investors should watch two things. First, how FUN's board formally responds to JANA. Second, whether early season pass sales hold up in the next earnings report. Until the board acts, FUN remains a turnaround story with a takeover option attached—not a takeover story.
This email communication is a paid advertisement for Chaikin Analytics, a third-party advertiser of MarketBeat. Why was I sent this message?.
This ad is sent on behalf of Chaikin Analytics, 201 King Of Prussia Rd., Suite 650, Radnor, PA 19087. If you would like to optout from receiving offers from Chaikin Analytics please click here.
If you need help with your subscription, please don't hesitate to contact our South Dakota based support team at contact@marketbeat.com.
If you would no longer like to receive promotional emails from MarketBeat advertisers, you can unsubscribe or manage your mailing preferences here.
© 2006-2026 MarketBeat Media, LLC. All rights protected.
345 N Reid Pl., Sixth Floor, Sioux Falls, S.D. 57103-7078. USA..



No comments:
Post a Comment