| Unsubscribe |
Hello there,
I was taking a look over your account and noticed that you haven't yet upgraded your MarketBeat subscription to MarketBeat All Access.
Through Friday, October 30, you can upgrade to MarketBeat All Access for $149 a year instead of $249. That is a $100 account credit toward your subscription, and it is not just for the first year: you keep the $149 rate at every renewal for as long as you stay subscribed. If you prefer monthly billing, it is $14.99 a month instead of $29.
We rarely make an offer where the discount stays with you, so I wanted to make sure you didn't miss it.
If MarketBeat All Access is not for you, you can get a full refund within your first 30 days.
Rebecca McKeever
MarketBeat
Curaleaf’s Higher Aurora Bid Raises the Stakes in Cannabis Consolidation
By Jeffrey Neal Johnson. First Published: 10/6/2026.
Key Points
- Curaleaf raised its hostile takeover bid for Aurora Cannabis to $5 per share, a 25% increase, amid a cannabis sector consolidation wave.
- The Schedule III reclassification of medical cannabis removes Section 280E tax burdens, prompting multi-state operators to acquire distressed international assets quickly.
- Tilray Brands' upcoming Oct. 8 earnings report will signal sector-wide cash-burn trends, while the MSOS ETF offers diversified exposure to consolidation gains.
- Special Report: Trump goes "all-in" on Grand Canyon energy breakthrought.
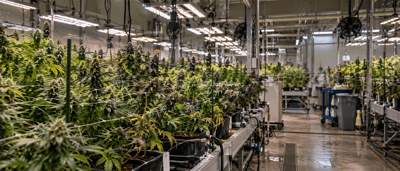
The multi-year cannabis sector bear market is beginning to give way to a calculated wave of industry consolidation. Behind the urge to merge is a significant shift in U.S. federal regulatory policy, encouraging better-capitalized operators to secure global supply chains before tax relief drives widespread multiple expansion.
At the center of this structural shift is a hostile bidding war. Multi-state operators are aggressively targeting distressed assets, seeking to acquire international infrastructure and clean balance sheets at a discount to replacement cost.
The Schedule III Catalyst Changing the Game
Ian Cooper Unveils a Simple Options Trade Strategy (Ad)
Ian Cooper's newest strategy targets triple-digit returns in just 9 days. It doesn't work every time, but a 73% win rate and 2,671% return on capital stand on their own.
Ian is breaking down the full strategy and offering his newest report at no charge.
Get the free report and see the full options strategy nowIn April 2026, the Department of Justice issued an order placing state-regulated medical cannabis in Schedule III. For fundamental investors, this is a cash flow event, not just a headline. Under Schedule I, Section 280E of the U.S. tax code, cannabis businesses cannot deduct ordinary operating expenses. This archaic rule forces companies to pay taxes on gross profit rather than net income, artificially crushing operating margins across the industry. Moving medical cannabis to Schedule III removes this tax burden, allowing operators to deduct standard expenses such as payroll, rent and marketing.
The regulatory timeline recently fractured, creating a specific opportunity. In September 2026, a Drug Enforcement Administration administrative law judge paused the broader adult-use rescheduling process. This regulatory delay created a narrow window for multi-state operators.
Companies that scale their global medical footprints now can capture immediate tax parity, while recreational-only operators remain subject to federal tax burdens. This divergence in tax treatment may be one catalyst driving the current wave of cross-border asset consolidation. Acquirers may see an opportunity to secure medical infrastructure before broader regulatory benefits are fully reflected in valuations.
Why Aurora Cannabis Is the Ultimate Target
Curaleaf Holdings, Inc. (OTCMKTS: CURLF) is moving aggressively during this regulatory window. Curaleaf recently filed a Notice of Variation and Change, escalating its hostile takeover attempt of Aurora Cannabis (NASDAQ: ACB).
The revised bid increases the total implied consideration by 25% to $5 per share. The offer consists of 0.4013 Curaleaf shares plus a cash component increased by 33% to $1 per share. A newly established cap price of $6 per share represents a maximum premium of 118% over Aurora Cannabis' pre-bid trading level.
Part of the logic behind this hostile maneuver lies squarely in the balance sheet. Curaleaf has a market capitalization of roughly $2.31 billion and generates about $1.27 billion in annual sales. The company is managing a negative net margin of 2.62%.
Acquiring Aurora Cannabis could strengthen Curaleaf's financial and operating profile. Aurora Cannabis holds no debt and has approximately $105 million in cash, restricted cash, short-term investments and cash equivalents. Before the bid, Aurora Cannabis traded at a steep discount to replacement cost, with a price-to-book ratio of 0.72.
Absorbing Aurora Cannabis would allow Curaleaf to leverage 280E tax relief across a broader, EU-GMP-certified global medical supply chain while adding clean cash to its operations. Recognizing the value of its debt-free position, Aurora Cannabis' management is deploying defensive tactics.
By filing complaints with the Alberta Securities Commission regarding alleged disclosure deficiencies, Aurora Cannabis is attempting to stall the takeover. This defensive posture pressures the acquirer to increase the cash component, preventing Aurora Cannabis from surrendering its balance sheet cash at a distressed multiple. Institutional traders are pricing in a finalized premium payout or a competing bidder, as call option volume on Aurora Cannabis shares recently surged 248% above the daily average.
Tilray Earnings Will Test Sector Strength
While Curaleaf and Aurora Cannabis battle over valuation, the broader health of legacy Canadian operators will face an immediate test when Tilray Brands (NASDAQ: TLRY) reports its first-quarter fiscal 2027 (FY2027) earnings on Oct. 8. Tilray Brands serves as a key near-term barometer of the sector's underlying macroeconomic health.
Last quarter, Tilray Brands delivered a top-line beat, reporting $281.71 million in revenue against estimates of $246.30 million. Despite the revenue growth, Tilray Brands missed on the bottom line, reporting an earnings-per-share loss of 43 cents and a trailing earnings-per-share loss of $1.08.
For investors monitoring the M&A landscape, Tilray's upcoming earnings report is primarily about cash burn rates. If Tilray Brands demonstrates balance sheet stabilization, target operators across the sector gain leverage to demand higher acquisition premiums from U.S. buyers. If cash burn accelerates, it would signal further sector weakness, giving U.S. acquirers the upper hand in absorbing distressed assets at steep discounts.
Playing the Takeover War Through ETFs
Navigating single-stock execution risk during a hostile bidding war requires a high risk tolerance. Investors looking to capture the aggregate upside of Schedule III multiple expansion have an alternative investment vehicle.
The AdvisorShares Pure U.S. Cannabis ETF (NYSEARCA: MSOS) offers a structural hedge for investors seeking exposure to broader industry consolidation without absorbing the dilution and integration risks inherent in individual corporate battles.
Operating as a non-diversified fund with about $868 million in assets under management and a 0.74% expense ratio, the U.S. Cannabis ETF tracks a basket of U.S. multi-state operators. As medical operators achieve tax parity and look to roll up distressed Canadian assets, the fund's underlying holdings stand to benefit from sector-wide margin expansion. The ETF offers a measured way to capitalize on the current regulatory shift without guessing which acquisition target will deliver the highest return.
Strategic Moves for Cannabis Investors
The escalated bid for Aurora Cannabis confirms that institutional capital views current sector valuations as a fundamental floor. Multi-state operators are unwilling to wait for the DEA to finalize recreational guidelines, choosing instead to consolidate medical supply chains immediately to capture early tax advantages.
Investors evaluating this sector might consider monitoring balance sheet health rather than just top-line revenue. Companies with no debt and long cash runways may be prime acquisition targets, while highly leveraged operators may struggle to participate in the consolidation phase.
Cautious investors may prefer sector-wide funds to gain exposure to the anticipated arrival of tax relief, while those with higher risk tolerance can evaluate individual operators with clear paths to positive cash flow following the Schedule III transition. The current environment may favor operators with stronger balance sheets and the strategic foresight to scale before regulatory tailwinds fully materialize.
MarketBeat Week in Review – 10/05 - 10/09
Submitted by MarketBeat Staff. Date Posted: 10/10/2026.
Key Points
- Stocks have stayed resilient heading into earnings season despite elevated Treasury yields, oil-price volatility, and upcoming midterm election uncertainty.
- Investors are watching upcoming bank earnings and fresh consumer and producer inflation data ahead of the Federal Reserve's late October meeting.
- MarketBeat contributors covered a wide range of companies, including Nike, NVIDIA, Amazon, Apple, Tesla, Meta, Alphabet, and Constellation Energy, amid ongoing AI-driven market themes.
- Special Report: Trump goes "all-in" on Grand Canyon energy breakthrought.
Stocks remained resilient heading into earnings season despite elevated Treasury yields and oil price volatility. AI-related stocks continued to support investor sentiment, but upcoming corporate earnings could help determine whether the rally extends through year-end.
We're less than a month away from the midterm elections, which means investors may be starting to consider where they want to be positioned if the balance of power in Washington changes.
The REAL Reason Trump is Invading Iran (Ad)
For a moment…
Forget about Trump’s ties to Israel.
Forget about reports of Iran’s nuclear program.
Because my research has led me to believe we’re risking World War 3 with Iran for a completely different reason.
Click here to find out what it is.In addition to reports from the big banks next week, investors will get the latest inflation readings at both the consumer and producer levels. These will be among the last key data points before the Federal Reserve meeting in late October, and an unexpected reading in either direction could move markets.
Articles by Thomas Hughes
Nike Inc. (NYSE: NKE) continues to deliver disappointing financial results. But with NKE trading at new lows, Thomas Hughes explained why an improving balance sheet and new products arriving in early 2027 make at least a technical case for the troubled stock.
NVIDIA (NASDAQ: NVDA) sits at the opposite end of investor sentiment. NVDA reached a new all-time high in October. Hughes provided several reasons the stock may have more room to run.
BigBear.ai (NYSE: BBAI) shares have fallen sharply in 2026. However, Hughes pointed out several potential catalysts that, combined with high short interest, could trigger a short squeeze.
Articles by Sam Quirke
Amazon (NASDAQ: AMZN) signed a multiyear deal worth more than $1 billion with chip-design specialist Synopsys (NASDAQ: SNPS). Sam Quirke wrote that the price tag isn't the most important part of the story. He explained what the deal says about Amazon's AI ambitions and why it involves more than any single chip.
Morgan Stanley is still bullish on Apple (NASDAQ: AAPL), but the firm trimmed its price target anyway. Quirke explained the catch behind the call and why the debate over Apple comes down to more than how many iPhones it can sell.
Tesla (NASDAQ: TSLA) beat delivery estimates for the third quarter. But Quirke wrote that the headline number doesn't settle the debate. He laid out the key questions that remain as investors look ahead to earnings.
Articles by Chris Markoch
Constellation Energy (NASDAQ: CEG) jumped after announcing a nuclear deal with Google. Chris Markoch explained why nuclear uprates matter for AI and whether the stock is a buy after the move.
Constellation Brands (NYSE: STZ) beat earnings estimates, but weak guidance overshadowed the headline numbers. Markoch explained why beer demand is still a problem and what that means for investors.
The AI buildout has a new bottleneck, and it isn't chips or power. Markoch explained why light is becoming a critical constraint and highlighted three photonics stocks positioned to benefit.
Articles by Ryan Hasson
Even the best stocks need a breather. Ryan Hasson pointed out why that appeared to be the case for Alphabet Inc. (NASDAQ: GOOGL). The stock has been building a base for several months, but Hasson explained why the company's upcoming earnings report could reinforce its strong fundamentals and support further upside for GOOGL.
While technology stocks have driven much of the market's gains, Hasson highlighted five oversold areas that could benefit if market participation broadens beyond the sector.
Articles by Leo Miller
Insider sales at one tech giant topped $1 billion, while Berkshire Hathaway bought into a struggling homebuilder. Leo Miller explained what both trades may be telling investors.
Meta Platforms (NASDAQ: META) is building a new enterprise AI platform. Miller explained why it could become the next major pillar of Mark Zuckerberg's AI vision.
Analysts handed out plenty of upgrades in September, but three tech names stood out. Miller highlighted the stocks that got the most love from Wall Street and what may be driving the bullish shift.
Articles by Nathan Reiff
Acting on insider selling without context can be problematic. This week, Nathan Reiff highlighted three stocks with notable insider selling but explained why each stock presents a very different investment case.
D-Wave Quantum (NASDAQ: QBTS) launched a beta program for its gate-model quantum simulator. QBTS stock remains under pressure, and Reiff noted that the milestone supports the long-term investment thesis but is unlikely to drive near-term revenue or earnings.
Consumers know that once inflation pushes prices higher, they rarely go back down. However, Reiff suggested that dynamic could be profitable for investors. This week, Reiff pointed out three service-oriented stocks that can profit from sticky inflation.
Articles by Dan Schmidt
Following its acquisition of Warner Bros. Discovery, Skydance Corp. (NYSE: SKYD) began trading under its new name and ticker symbol. Dan Schmidt explained why an $80 billion debt load means the real work is just beginning for Skydance.
The AI buildout has created a wave of new business for semiconductor companies, with growing margins driven by their ability to charge higher prices. However, Schmidt highlighted three AI stocks that have employed different strategies to grow their margins and explained why understanding those strategies is critical to determining whether the stocks are good long-term buys.
Analysts are frequently hesitant to become bullish on beaten-down stocks. That's why Schmidt argued investors should pay attention to three market laggards that are getting a contrarian vote from analysts.
Articles by Jeffrey Neal Johnson
DraftKings (NASDAQ: DKNG) is pivoting toward prediction markets, a move that could unlock $800 million. Jeffrey Neal Johnson explained how the company is stacking the deck and what the shift could mean for investors.
Disney (NYSE: DIS) is licensing content to Netflix (NASDAQ: NFLX), a move few would have expected a few years ago. Johnson explained why the deal could change the streaming playbook.
An AI game development deal backed by Alphabet lifted shares of Unity Software (NYSE: U) and put pressure on Roblox (NYSE: RBLX). Johnson explained how the partnership levels up game development and why investors reacted the way they did.
Articles by Peter Frank
Linde (NASDAQ: LIN) is better known for industrial gases than AI. Peter Frank examined how rising AI chip demand could fuel growth and whether that opportunity outweighs concerns about the company's margins.
Allient (NASDAQ: ALNT) has rallied past analysts' price targets on strong data center and defense demand. Frank explained why that momentum is raising the stakes and whether record orders can justify the move.
Lemonade (NYSE: LMND) is growing faster, but investors want to see profits. Frank looked at whether the company's growth signals profits ahead.
MarketBeat empowers individual investors to make better financial decisions by delivering up-to-the-minute financial information and best-in-class investment analysis.
If you need help with your newsletter, please email MarketBeat's U.S. based support team at contact@marketbeat.com.
If you would like to unsubscribe or change which emails you receive, you can manage your mailing preferences or unsubscribe from these emails.
© 2006-2026 MarketBeat Media, LLC. All rights reserved.
345 N Reid Pl., Sixth Floor, Sioux Falls, SD 57103. USA..



No comments:
Post a Comment