| Unsubscribe |
Dear Friend,
The average American bank plans to put $170 million into AI over the next 12 months, by KPMG's count.
JPMorgan alone will spend about $19.8 billion on technology this year.
They're not spending like men who think it's a story.
They're spending like men who've read the same report I have.
The last three times the money was cracked open, the people who owned the defense made 170%, 1,017% and 1,107%.
Now the banks are paying a new set of companies to stop the night I've mapped.
I've narrowed it to one.
And a federal rule says the rewiring has to be finished by December 31.
Not started. Finished.
Go here for the company the banks are paying, before December 31 >>
The Buck Stops Here,
Dylan Jovine
Founder, Behind the Markets
Apple’s $5.7 Billion Patent Verdict Raises a Bigger Royalty Question
Author: Sam Quirke. Article Published: 10/1/2026.
Key Points
- Apple faces a $5.7 billion jury verdict after jurors found that its Taptic Engine infringed claims in two Taction Technology patents, and Apple plans to appeal.
- Apple has the financial capacity to absorb a one-time award, but a potential ongoing royalty on affected products could create a longer-lasting margin risk.
- Apple retains a Moderate Buy consensus among analysts, although its elevated valuation leaves less room for legal or operational setbacks.
- Special Report: Trump goes "all-in" on Grand Canyon energy breakthrought.
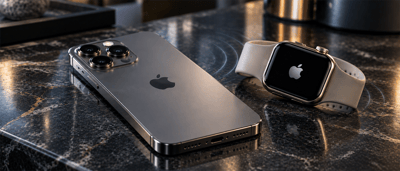
Shares of Apple Inc. (NASDAQ: AAPL) fell 2.66% on Tuesday, Sept. 29, extending the decline from the prior session. The pullback came despite the stock having set an intraday all-time high on Tuesday, Sept. 22. A federal jury’s $5.7 billion verdict against Apple on Friday, Sept. 25, added a fresh legal overhang and reminded investors that even the largest companies can see their stocks spooked by a single piece of legal news.
The ruling ordered the tech giant to pay more than $5.7 billion to Taction Technology after finding that Apple’s Taptic Engine infringed claims in two patents covering haptic-feedback technology used in iPhones and Apple Watches. Apple has said it will appeal. A $5.7 billion one-time payment might be material in absolute terms, but Apple has substantial financial capacity to absorb it, having generated nearly $117 billion in operating cash flow during the first nine months of fiscal 2026.
The energy story near the Grand Canyon (Ad)
The largest energy source on Earth contains 50,000 times every oil and gas reserve on the planet combined - and much of it sits beneath the desert near the Grand Canyon.
A drilling crew just hit the DOE's 2035 targets twelve years early, with costs down 50% in 18 months. Google signed on, Gates invested, and the Pentagon made it a priority. One company has been quietly building this infrastructure for sixty years.
See the company sitting on the biggest energy source on EarthHowever, here is where the verdict gets interesting: The real threat isn’t the one-time payout. It’s the possibility of an ongoing royalty on every affected iPhone and Apple Watch sold going forward. That scenario would put material pressure on hardware margins over time, which is why some investors are treating this verdict as more than a legal sideshow.
Why the Royalty Risk Matters More Than the Verdict
Thankfully for investors, Apple’s scale makes the headline figure look worse than the underlying economics. The company can comfortably absorb a multibillion-dollar charge without threatening its balance sheet, buybacks or ability to invest in new products.
A recurring royalty is different. It would affect the economics of every affected device for years rather than hitting earnings once. The market, therefore, has good reason to focus less on the Sept. 25 award and more on what Apple might ultimately have to pay to keep using the technology.
Apple’s Pricing Power Still Supports the Bull Case
For now, Apple’s pricing power remains the foundation of the broader bullish thesis. The company has consistently raised prices on iPhone Pro models without losing meaningful volume. It has done so while managing component-cost inflation and maintaining solid gross margins.
Services revenue, which has started to exceed hardware revenue in some quarters, provides a diversification buffer that did not exist five years ago. Recent iPhone Pro demand indicators remain healthy, with lead times elevated in several markets—a backdrop consistent with pricing power holding up.
The bulls argue that Apple’s cash-generation capacity can absorb the $5.7 billion hit. The real constraint is whether the company can avoid paying a recurring royalty, and the appeal offers a credible path forward.
A federal district court originally granted Apple summary judgment of noninfringement in 2023, but the U.S. Court of Appeals for the Federal Circuit vacated that ruling on Aug. 13, 2025, and sent the case back for further proceedings. A successful appeal or a settlement that avoids a significant ongoing royalty would remove much of the overhang. Under that framework, the verdict creates an opportunity for a settlement that removes longer-term uncertainty without gutting margins.
Valuation Leaves Less Room for Legal Setbacks
The bearish argument continues to rest on valuation and execution risk, and bears will consider the Sept. 25 verdict another point in their favor. When Apple’s valuation is already stretched compared with historical levels, there is not much room for setbacks like this.
If hardware margins were compressed by new recurring royalty payments, current upgrade cycles disappointed or component costs rose faster than pricing could offset them, the stock’s valuation could contract rather sharply.
Bears will also argue that Apple’s new premium devices may raise average selling prices without generating enough incremental earnings growth to justify the current valuation. A legal headwind only compounds that concern when the stock is already priced at an elevated multiple.
Yet here is the critical detail: The vast majority of analysts remain bullish on Apple, and the MarketBeat consensus rating is still a Moderate Buy, even after the verdict. That consensus suggests Apple’s fundamental economics are strong enough to weather the verdict without materially changing the investment case.
A Legal Scare, Not Yet a Thesis Breaker
That said, the $5.7 billion verdict is a real risk, and the royalty question deserves close monitoring as the appeal proceeds. But Apple’s pricing power, broader revenue growth and fortress balance sheet give the company substantial resources to address the problem—whether through an appeal, a settlement or the kind of margin management it has proven adept at executing.
For those who are bullish on Apple over the long term, the verdict might create a window for an entry point, as it is almost certainly not a reason to abandon the bullish thesis. Investors comfortable with Apple’s valuation at current levels might therefore see the recent pullback as a buying opportunity dressed up as a legal scare.
These 3 Agentic AI Stocks Have More Than Hype Behind Their Growth Stories
Author: Chris Markoch. Article Published: 9/19/2026.
Key Points
- Agentic AI has become one of the market’s fastest-moving themes, making it harder to separate genuine enterprise adoption from expectations already embedded in stock prices.
- The stronger setups are companies showing that AI agents can translate into product adoption, recurring revenue, or a broader platform advantage.
- ServiceNow, UiPath, and Palo Alto Networks approach agentic AI from different directions, giving investors three ways to assess whether the fundamentals can support the enthusiasm.
- Special Report: Trump goes "all-in" on Grand Canyon energy breakthrought.
The market frequently misprices the gap between what a company is actually building and what investors think it’s building. Nowhere is that gap wider right now than in agentic artificial intelligence (AI). This refers to software that doesn’t just answer questions but takes actions and makes decisions while operating with minimal human input.
The growth of agentic AI has happened quickly, arguably faster than the fundamentals of the companies building out the technology. That means some names are being bid up on hype, while others with real infrastructure and revenue are being lumped into the same “overextended” story.
This New Trading Engine Spots Moves Before the Charts Do (Ad)
K.I.R.A. is a new trading engine built to flag market setups before they show up on standard charts.
Former hedge fund trader Lance Ippolito says it identifies early moves and lets traders set their own risk level instead of guessing.
Claim free access to K.I.R.A. and see it in actionThose stocks with strong fundamentals to support their growth are where the opportunity lies. These companies have agentic AI exposure backed by actual product traction, enterprise adoption, or platform advantages that can hold up once the noise clears.
While it’s fair to say that some of these stocks don’t come cheap, they all have durable moats wide enough to withstand the current volatility, which won’t be going away anytime soon.
ServiceNow: A Major Endorsement Is the Tailwind
ServiceNow Inc. (NYSE: NOW) is a prime example of a stock where the price is catching up to the fundamentals. NOW is down approximately 11% in 2026, but it has been moving sharply higher since it reported its Q2 earnings in July.
The stock also got a boost from NVIDIA (NASDAQ: NVDA) chief executive officer (CEO) Jensen Huang, who called the company’s Now Platform the “platform destined to be the best platform, the operating system of enterprise AI agents.”
That’s the agentic AI argument in a nutshell. The company validated that growth in its Q2 report, reporting that customer adoption of agentic AI had grown ninefold over the prior nine months. It also reported that first-time AI buyers were up more than 45% year over year.
ServiceNow also announced an expanded partnership with Anthropic to integrate the latter’s Claude models more deeply into its AI platforms.
UiPath: The Stock Wall Street Is Still Discovering
UiPath (NYSE: PATH) has a business model that defines agentic AI. The company develops enterprise automation software that helps organizations automate repetitive, rules-based and increasingly complex business processes.
But investors have been fading PATH stock, which is down more than 15% in 2026—at least until recently. PATH stock is up more than 31% over the last three months. In the middle of that period was the company’s Q2 earnings report for its 2027 fiscal year (FY2027).
In that report, UiPath delivered revenue of $410.3 million, up 13% year over year, along with its fourth consecutive quarter of GAAP profitability. Maestro, its agentic orchestration layer, is doing exactly what the bears said wouldn’t happen. It helped UiPath earn recognition as a Forrester Wave leader and drove a real acceleration in enterprise deal activity.
Analysts still have a consensus Hold rating on PATH. However, price targets have been increasing since the earnings report. The UiPath analyst forecasts on MarketBeat show a consensus price target of $16.75, implying upside of more than 21%.
Palo Alto Networks: The Definition of an Essential AI Stock
The case for Palo Alto Networks (NASDAQ: PANW) is straightforward. If AI expands faster than we can control it, enterprise customers will need an AI-powered system ready to play defense.
That’s a key reason PANW is up approximately 25% over the last three months. Demand for the company’s product platform was evident in its Q4 earnings report for FY2026.
Support for sustained future growth came from a statement by Palo Alto CEO Nikesh Arora. He forecast that enterprises would need to spend at least $1 trillion to update aging cybersecurity infrastructure to handle attacks moving at machine speed.
To be fair, there are several other cybersecurity names that investors could choose from. CrowdStrike Holdings Inc. (NASDAQ: CRWD) and Okta (NASDAQ: OKTA) are two names that also reported blockbuster earnings. That said, Palo Alto is among the best in class and offers investors a set-it-and-forget-it option in the sector.
Why Owning These Stocks Rewards Patience
None of these three companies needs a perfect quarter to succeed. They need the market to keep noticing what’s already showing up in the numbers. That’s the setup long-term holders want: real execution that is still catching up to investor belief.
That gap is exactly where this strategy pays off. Buying before consensus catches up means tolerating volatility while the story is still being debated on trading desks. But for investors willing to hold through the noise, the reward isn’t a single earnings pop—it’s owning the re-rating itself as skepticism slowly gives way to the numbers already on the page.
This email communication is a sponsored message sent on behalf of Behind the Markets, a third-party advertiser of MarketBeat. Why was I sent this message?.
If you have questions or concerns about your account, please contact our U.S. based support team at contact@marketbeat.com.
If you would no longer like to receive promotional emails from MarketBeat advertisers, you can unsubscribe or manage your mailing preferences here.
© 2006-2026 MarketBeat Media, LLC. All rights reserved.
345 N Reid Place #620, Sioux Falls, SD 57103-7078. United States..



No comments:
Post a Comment