|
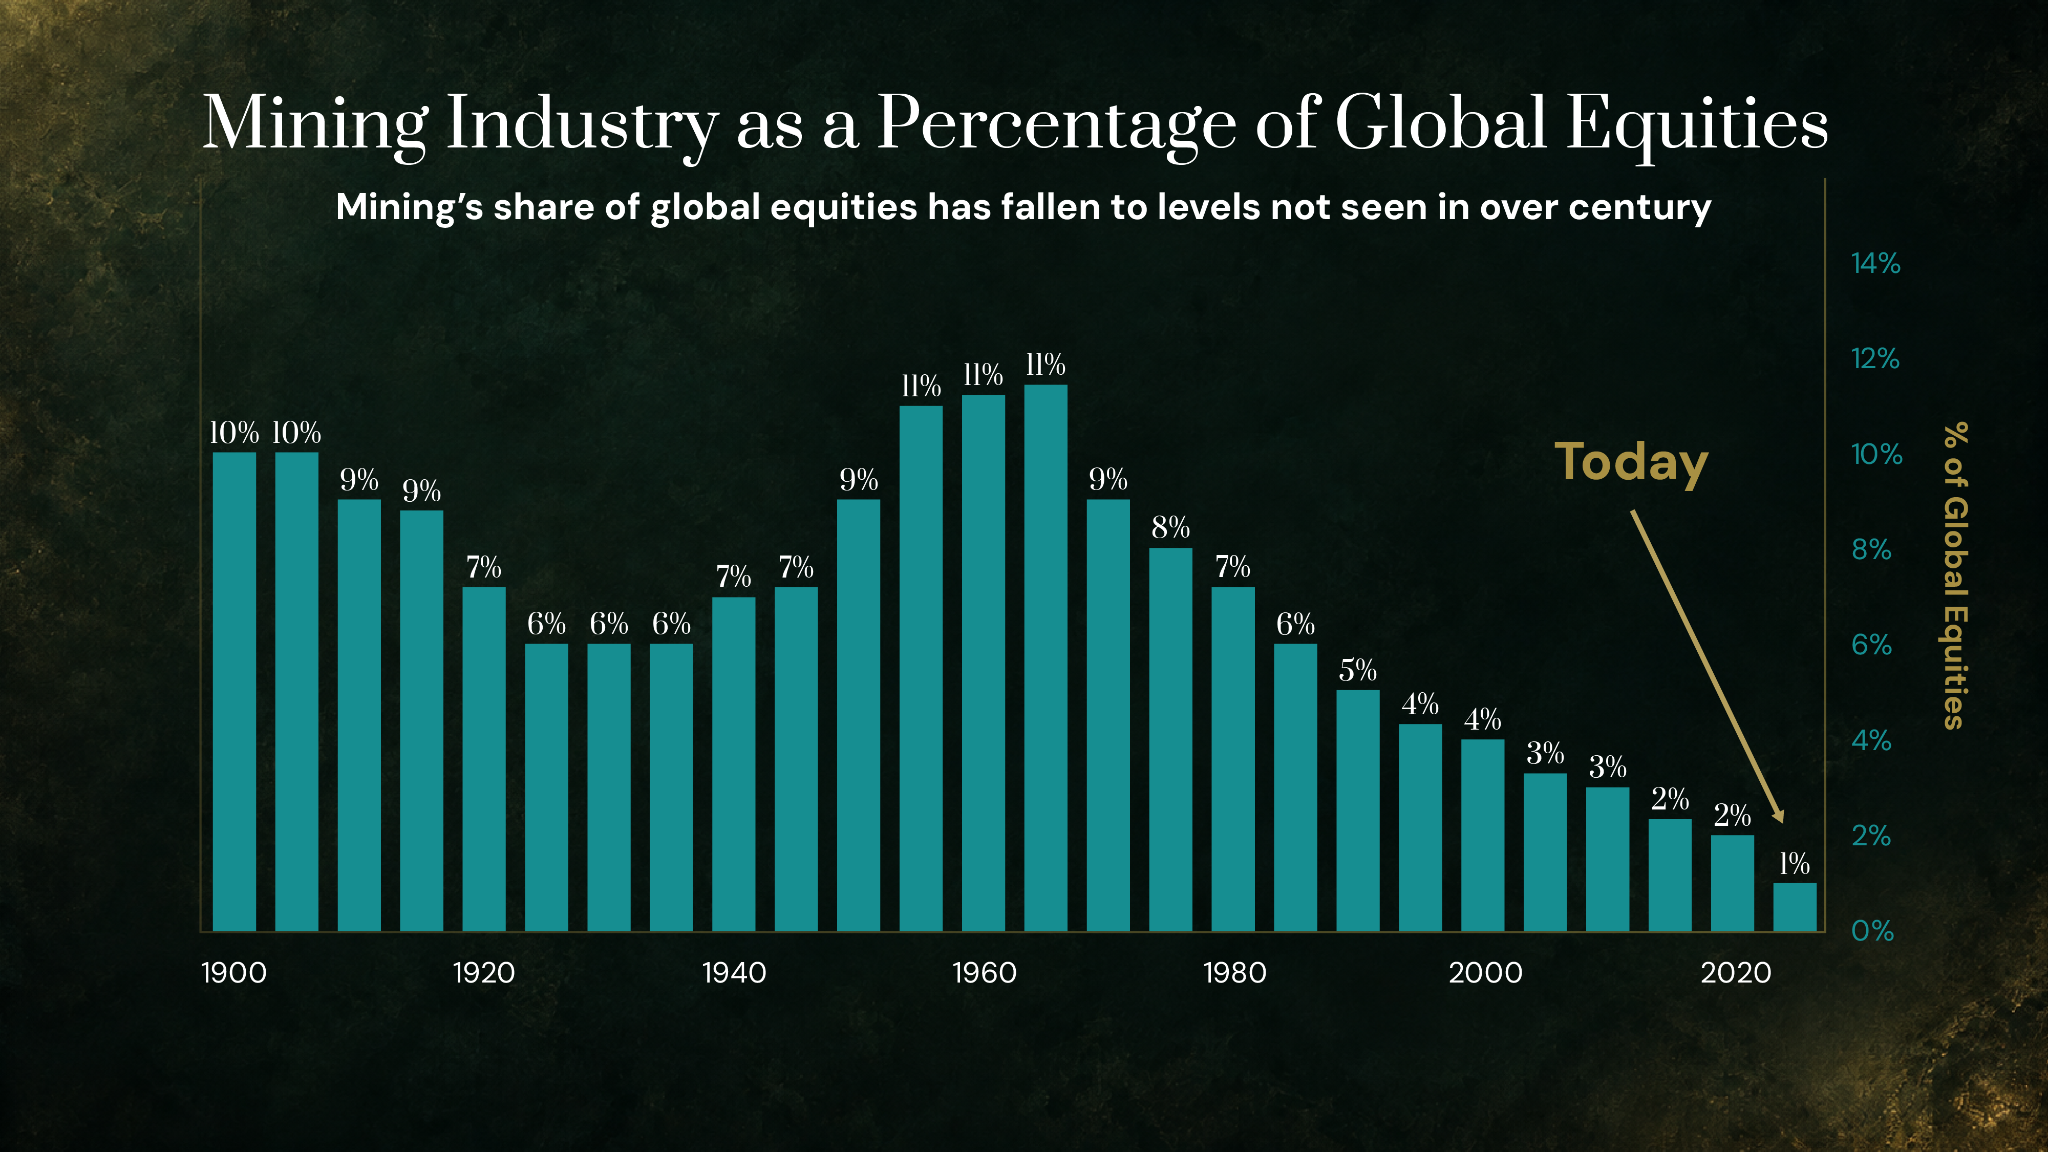
Today, mining represents just 1% of global equities – the lowest level in more than a century.
Almost nobody owns them. Now consider… What happens if even a small amount of the enormous capital currently chasing AI/tech/growth stocks starts looking for somewhere else to go… I call this a "Great Rotation" – when money flees growth stocks looking for undervalued hard assets. Bottom line: The trillions of dollars currently betting on AI cannot flow into the tiny universe of gold stocks without making early investors very rich. Now… If you think money from growth/tech/AI isn't going to flood into gold stocks in the coming market correction… think again. It's happened three times before. I've spent more than 20 years studying gold and mining companies – traveling to mines around the world. If you want to potentially profit when the AI trade finally goes off the cliff, here's all you need to know: Only a small percentage of an enormous pool of money in AI/tech has to rotate into gold stocks for this tiny sector to hand early investors a generational fortune. For details on my top four miners, go here. Regards, Garrett Goggin, CFA, CMT Today’s editorial pick for you Netflix Cuts 1,000 Jobs as NFLX Stock Nears a Critical TestPosted On Oct 15, 2026 by Chris Markoch 
Netflix layoffs are back. On Oct. 14, Netflix Inc. (NASDAQ: NFLX) said it will cut about 6% of its workforce. That works out to roughly 1,000 jobs. The news comes out less than a week before the company reports third-quarter 2026 earnings on Oct. 20. Table of ContentsThe cuts are part of what management called broader “organizational changes.” Netflix didn’t explain what those changes are. Product, technology, legal, and human resources teams will take the biggest hit. It’s the company’s largest workforce reduction since 2022. Co-CEO Greg Peters said the company wasn’t growing fast enough. That’s a curious statement on its face. Netflix has delivered solid sequential and year-over-year (YOY) revenue and earnings per share (EPS) growth. It also forecasts 2026 revenue of $51 billion to $51.4 billion, an increase of 13% to 14%. Management is targeting an operating margin of 31.5%. Investors seem unmoved for now. NFLX stock slipped about 0.1% in after-hours trading. That’s neither a vote of confidence nor a rebuke. The real verdict may come next Tuesday. 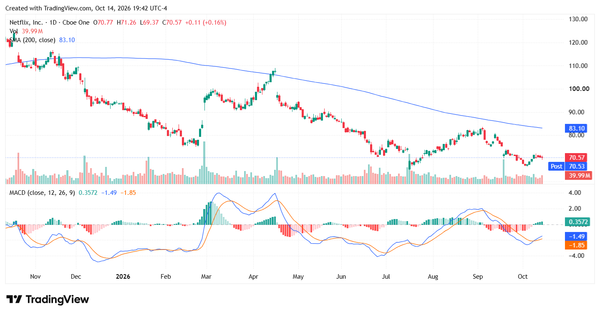
Why Netflix Is Cutting Jobs While Revenue Keeps GrowingReducing headcount is a tried-and-true way to goose the bottom line. Fewer salaries mean lower operating expenses. Those savings flow straight to margins. With roughly 16,000 full-time employees at the end of 2025, a 6% cut is meaningful but hardly existential. The internal memo struck a confident tone. Management said the business is strong and growing. It also said Netflix remains on track to hit its full-year forecast. The stated goal is more discipline about where people and resources go. That’s what makes the move feel a little odd. If the business is on track, why the urgency? And why say growth isn’t fast enough? One reading is that Netflix is reallocating, not retreating. Money saved in back-office functions can fund live sports, games, and advertising. Another reading is less flattering. Management may see slower growth ahead than its guidance implies. What to Watch in Netflix’s Q3 Earnings Report on Oct. 20Netflix guided for Q3 revenue of roughly $12.9 billion with an operating margin of about 33.2%. Consensus EPS sits near $0.82 to $0.84. For context, Q2 revenue was $12.56 billion, up 13.4% YOY. Diluted EPS came in at $0.80 with a 33.4% operating margin. Investors will want answers on three fronts. First, whether a restructuring charge is coming and how large it will be. Second, what the “organizational changes” actually involve. Third, whether full-year revenue and margin targets still hold. Keep in mind that Netflix’s Q3 forecast came in below Wall Street’s expectations. A modest beat against a lowered bar may not be enough. The tone of the post-earnings interview with Peters and co-CEO Ted Sarandos could matter more than the numbers. Did the Skydance Selloff Bury Netflix’s Layoff News?Is this a case of bad timing, or good timing? Netflix made its announcement the same day Skydance (NYSE: SKYD) shares plunged more than 22%. That pulled plenty of media-sector attention elsewhere. Much of Skydance’s drop was mechanical. Shares began trading without the right to roughly 471 million warrants distributed to former Paramount Skydance holders. Still, the stock fell further than the warrants’ value alone would explain. Investors are still trying to settle on a fair value for the company. That matters for Netflix. Skydance closed its acquisition of Warner Bros. Discovery on Oct. 6. It now controls the studios, networks, and streaming assets of both Paramount and Warner Bros. That’s a far larger rival than either company was alone. Is NFLX Stock a Buy Near Its 52-Week Low?The bigger issue for NFLX stock may be sentiment. Shares are down 24% year to date and trading near their 52-week low. The market is no longer pricing Netflix like an untouchable growth leader. Netflix still commands the largest share of the streaming market at around 19%. But competition is intensifying. Amazon’s Prime Video and Disney+ are close behind. A consolidated Skydance adds another heavyweight to the field. Netflix is also spending on several fronts at once. Live sports rights aren’t cheap. Neither is the constant need to refresh original content. Both will continue to weigh on earnings, even as headcount cuts provide some offset. Netflix Layoffs Expose a Perception vs. Fundamentals GapThis is where perception and fundamentals may be diverging. Fundamentally, Netflix is growing revenue in the low teens with operating margins above 30%. Few media companies can say that. Perceptually, the market sees a maturing streamer facing better-funded rivals and costly bets. The layoffs cut both ways. A leaner streaming company could expand margins faster than expected. But “we’re not growing fast enough” is not what investors want to hear about a stock already down 24%. Next Tuesday’s report will show which story the market chooses to believe. This is a PAID ADVERTISEMENT provided to the subscribers of StockEarnings Free Newsletter. Although we have sent you this email, StockEarnings does not specifically endorse this product nor is it responsible for the content of this advertisement. Furthermore, we make no guarantee or warranty about what is advertised above. Your privacy is very important to us, if you wish to be excluded from future notices, do not reply to this message. Instead, please click Unsubscribe. Stock Earnings, LLC |




No comments:
Post a Comment