|
Hello,
This is a quick reminder that you’re nearing the end of your first 30 days with MarketBeat, but your subscription still hasn’t been confirmed. To keep your access active, please verify your email address before the deadline. If your email isn’t verified in time, your subscription will be automatically canceled, and you’ll stop receiving MarketBeat Daily Ratings. That means you may miss daily updates on analyst rating changes, insider buying and selling activity, market news, stock updates, and other research smart investors use to stay informed and stay ahead. Confirm Your Subscription Here
Thanks!
Laycee Kluin
MarketBeat
P.S. Have questions about your account or need help confirming? Just hit reply — I’ll get you squared away.
Exclusive Article
Did Promo Spending Actually Win Back Bettors for These 3 Gambling Stocks?Author: Dan Schmidt. Article Published: 10/12/2026. 
Key Points
- Prediction markets are pressuring traditional sportsbooks, prompting Flutter Entertainment, Las Vegas Sands, and Penn Entertainment to pursue different promotional strategies with varying stock results.
- Flutter Entertainment's heavy marketing spend to defend FanDuel's market share led to a net loss and reduced 2026 guidance, pushing shares to new lows.
- Penn Entertainment's pullback from costly promotions after exiting its ESPN Bet partnership narrowed online losses and made it the best-performing stock of the three in 2026.
- Special Report: Why This Clean Energy Well Escaped the Solar and Wind Cuts.
Prediction markets have forced the gambling industry to take drastic action. While headlines often focus on Kalshi or Polymarket users betting on politics or economics, more than 80% of activity still occurs in sports markets, which is bad news for incumbent sportsbooks. In addition to taking market share, prediction markets receive preferential tax and legal treatment from the federal government, while traditional sports betting remains under the scrutiny of state gambling commissions. With the deck stacked against them for a change, sportsbooks and casinos have been offering promotions to lure back wayward gamblers. And we aren’t just talking about the parlay boosts you see Kevin Hart hawking every Sunday. Gambling companies are spending millions of dollars on marketing and promotions, and as you might expect from a mature industry, the results are mixed. Flutter Entertainment PLC (NYSE: FLUT), Las Vegas Sands Corp. (NYSE: LVS), and Penn Entertainment Inc. (NASDAQ: PENN) each took a different approach to promotion, and their 2026 stock performance shows which strategy the market is rewarding. Flutter Entertainment: Defending Market Share at Any Cost
Cindy has MS and retired to Europe with her husband Dean. Her healthcare there is exceptional and becomes free after just 90 days of residency.
A little known program is giving American retirees access to government funded healthcare abroad, an option many never knew existed. Learn how Americans are accessing free healthcare in Europe
Flutter Entertainment is the parent company of FanDuel, one of the two largest online sportsbooks in the U.S., alongside DraftKings Inc. (NASDAQ: DKNG). FanDuel is the segment under the most pressure from prediction markets, and new CEO Dan Taylor is deliberately reinvesting in the platform through marketing and the company’s own prediction-market buildout. Some of these initiatives are showing up in the numbers, and the results so far haven’t been pretty. The fiscal Q2 2026 report showed that revenue grew just 3% year over year (YOY), while the company reported a net loss of $296 million for the period. A 61% YOY increase in sales and marketing spending ate into profits, and adjusted EBITDA fell 45% from Q2 2025. The World Cup boosted user activity, but management doesn’t view that increase as sustainable and again reduced its 2026 revenue and EBITDA guidance. CEO Taylor expects continued marketing efforts to create a $270 million EBITDA drag for the remainder of the fiscal year. 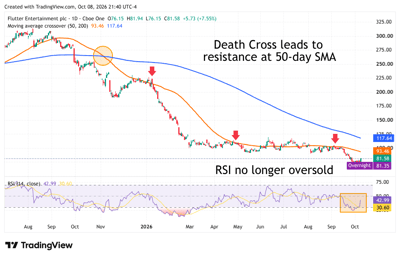
The World Cup occurs once every four years, and this one-time boost will disappear in Q3. The fiscal Q1 2026 report showed that U.S. monthly players declined 1% and handle fell 9%. The gambling ban in Brazil adds a $70 million revenue headwind, and the stock has hit new 2026 lows in recent weeks. The chart also flashes several bearish signals, including resistance at the 50-day moving average and a relative strength index (RSI) hovering between 30 and 50. Las Vegas Sands: Retaining Share Without the Profit GainsLas Vegas Sands has focused on reinvestment in Macau over the last year, with mixed success. Despite missing top- and bottom-line estimates in fiscal Q2 2026, Sands China’s mass gross gaming revenue (GGR) grew 8% YOY, compared with 4% YOY for the overall market. Meanwhile, Marina Bay Sands in Singapore reported $689 million in EBITDA. However, management is working hard to retain clients, and doing so is becoming increasingly expensive. Macau commissions and promotions topped 20% of GGR in Q2, the highest figure on record. Promotional spending was already up 28% YOY in Q1, and the company says this approach won’t change during the second half of fiscal 2026. Although management does not provide guidance, it maintained its $700 million quarterly EBITDA target for Macau. 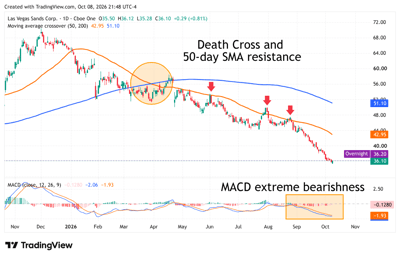
Despite maintaining more market share, LVS hasn’t been rewarded by the market. The stock is down more than 40% year to date (YTD), and the sell-off has intensified over the last month. A death cross created stiff resistance at the 50-day moving average, and the MACD now shows that buying momentum has completely evaporated. Penn Entertainment: Marketing Pullback Rewarded by the Market (Sort Of)Penn Entertainment is the best-performing stock of the three so far in 2026. Despite a recent 20% drawdown, PENN shares are still up about 5% YTD, and the story here is more about what the company didn’t do. Penn Entertainment exited its 10-year agreement with ESPN Bet in December 2025 and relaunched under its own moniker, theScore Bet. In the two months following the rebrand, interactive marketing spending dropped 65%, while online sportsbook revenue doubled. During the fiscal Q2 2026 conference call on Aug. 6, management raised the midpoint of its 2026 retail revenue guidance to $5.87 billion, citing expected margin growth in the second half of the year. In the online segment, adjusted EBITDA losses narrowed to $9.5 million from $62 million in Q2 2025. Handle is down 24%, but management says the customers leaving are promotion-dependent, and it aims to attract more VIP-level clients. Most of Penn’s revenue still comes from its physical casinos. Still, online losses have narrowed thanks to the marketing pullback, and the market currently views that as a better value proposition than paying through the nose to retain clients. 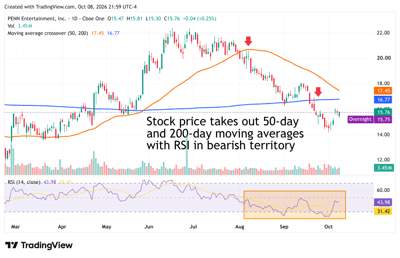
PENN shares have declined more than 20% over the last three months, pushing the price below the 50-day and 200-day moving averages. The RSI bounced off an oversold signal during the first week of October but remains below the bullish 50 threshold. While PENN has been a winner in the gambling sector, it still lags far behind the S&P 500, and its digital business continues to shrink. Getting leaner has limited losses, but this sector still needs evidence of growth before any of these stocks begin beating the market again. Penn’s Q3 2026 conference call on Nov. 5 is the next potential catalyst. If the digital base stabilizes, it could prove that pulling back on promotions is the best way to operate.
(ARReply-430) |



No comments:
Post a Comment