Trump and Musk are circling the same $5 stock 
Palantir's Q3 Bar Is Higher Than It Looks: 3 Numbers to WatchWritten by Chris Markoch on October 28, 2026 
Key Points
- Heading into its Nov. 2 earnings report, Palantir faces heightened expectations.
- Investors should scrutinize whether new customer additions, not just deeper spending from existing clients, are driving Palantir's commercial revenue growth.
- With shares trading at about 122 times 2026 earnings, Palantir's free cash flow results and forward guidance must clear high bars already priced in by Wall Street.
- Special Report: The election is close. Your report is free.

Palantir Technologies (NASDAQ: PLTR) heads into its Q3 earnings report at the center of the AI trade. It's also a persona non grata for investors who believe the stock's valuation remains too high. In the first half of 2026, the naysayers got the upper hand. PLTR first cracked $207 in early November 2025. After that, it dropped to around $107 and, for a moment, Palantir bears like Michael Burry were laughing at Palantir's loyal retail army of investors. That all changed after Palantir's Q2 report. The stock is up approximately 55% since then and closed at a new all-time high around $209 on Oct. 12. The rally changes the stakes for Palantir heading into its Q3 report on Nov. 2. While expectations were laughably low last quarter, this quarter, Palantir has a target on its back, and there's more risk to a bad report. It could even be that a good report may not be good enough. The headline numbers are likely to be strong. But they could distract investors from what's really important. Here are three specific data points investors should be watching when Palantir reports.
Elon Musk quietly filed a document with the federal government tied to artificial intelligence, one of the largest markets in the world.
James Altucher, who previously flagged Nvidia in 2008 and Bitcoin in 2013, says the filing could rival Tesla, SpaceX and xAI combined.
Few investors know this filing exists, but that is expected to change quickly. Click here to see details on Elon Musk's newest AI filing
Customer Count Shows Whether Growth Is BroadeningPalantir's U.S. commercial business is the engine of the bull case. In Q2, U.S. commercial revenue jumped 149% year-over-year to $764 million. But revenue growth can come from two places. Palantir can win new customers, or it can sell more to the ones it has. Right now, it's leaning heavily on the second. The company ended Q2 with 653 U.S. commercial customers. That's up 35% from a year ago but only 6% from the prior quarter. Meanwhile, trailing 12-month revenue from its top 20 customers rose 67% to $124 million per customer. On the one hand, deeper relationships prove that the platform delivers value. The downside is that they also concentrate risk. If customer count stalls while revenue soars, bears will argue growth is narrower than the headline suggests. Investors should look for sequential customer growth of at least 6%. That would show AIP is still landing new logos, not just expanding old ones. Free Cash Flow Tests Whether the Valuation Holds UpPalantir's cash generation is its best answer to the valuation critics. In Q2, adjusted free cash flow (FCF) hit a record $1.22 billion. That was up 115% year-over-year and represented a 63% margin. Here's the wrinkle. Palantir raised its full-year adjusted FCF guidance to between $4.5 billion and $4.7 billion. The company generated about $2.15 billion in the first half. That leaves roughly $1.18 billion to $1.28 billion per quarter for the back half. In other words, the guidance implies free cash flow that's roughly flat with Q2. That's likely conservatism from a team that has beaten estimates for eight straight quarters. But with PLTR trading at about 122 times 2026 earnings, investors want proof. A Q3 number well above $1.22 billion would make the valuation easier to defend. A number in line with guidance could be read as a plateau. That matters more because of the bar Alex Karp set for himself in a July interview with CNBC. At that time, he said Palantir's financials pointed to $15 billion to $18 billion in FCF two years out. Even this year's raised guidance would need to more than triple to get there. A flat back half would make that path harder for investors to believe.
Jeff Brown, the former tech executive who picked Nvidia in 2016 before it surged as high as 37,800 percent, just got inside Elon Musk's new Cybercab, a vehicle with no steering wheel or pedals.
In 2018, the New York Post called Musk a total fraud. Brown's latest footage shows just how far that technology has come since then. Watch the Cybercab footage and judge Elon Musk's technology yourself
Guidance Reveals Whether the Rally Has More RoomGuidance is where the gap between perception and fundamentals is widest. Palantir guided for Q3 revenue between $2.160 billion and $2.164 billion. The analyst consensus sits at about $2.18 billion. That means Wall Street has already priced in a beat. Hitting the top of Palantir's own range would be a miss relative to expectations. The full year looks the same. Company guidance calls for $8.150 billion to $8.158 billion. Consensus is closer to $8.22 billion. After Q2, management delivered what it called its largest full-year guidance raise ever. Investors now expect that pattern to continue. For a stock trading around 58 times 2026 sales, the raise matters more than the quarter. Anything short of a raise that clears consensus could be the "good but not good enough" scenario. The Chart Says Investors Are WaitingThe technical picture adds a note of caution. PLTR's MACD line has crossed below its signal line, and the histogram has turned negative. Momentum has cooled since the October high, even as the stock holds near $199. That's not a sell signal on its own. Shares remain well above the 200-day simple moving average near $153. But it suggests buyers want to see the report before committing. On Nov. 2, the three line items above will help decide which way the chart breaks. 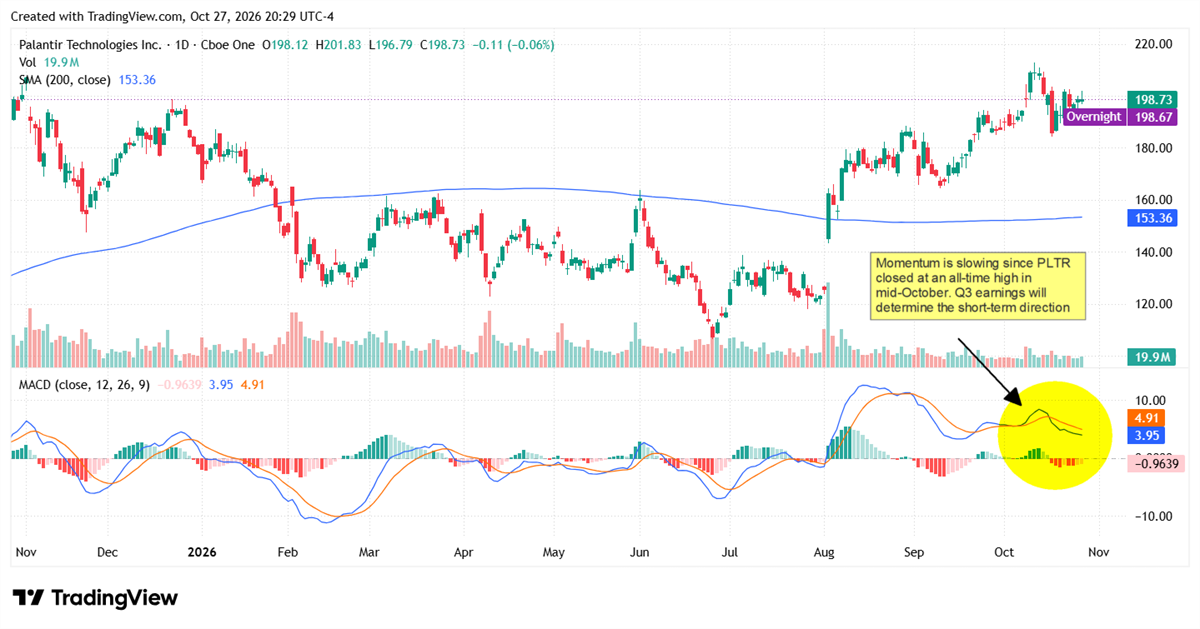
Read this article online › Further Reading
Did you find this article useful?  
|



No comments:
Post a Comment