| Unsubscribe |
Dear Reader,
Elon Musk just dropped another bombshell...
He's going after your cell phone provider.
For months, Elon kept these plans under wraps.
But late last week, he finally showed his hand.
SpaceX agreed to buy a huge chunk of the airwaves your phone uses to call and get online, reportedly for $8 billion in cash.
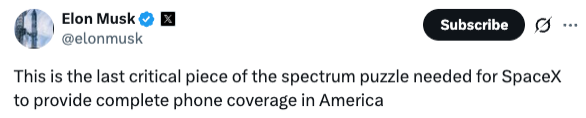
Elon took to X calling it "very big deal" and "the last critical piece" for complete phone coverage in America.
Wall Street panicked. Within hours, shares of AT&T, Verizon, and T-Mobile started falling.
But almost no one is explaining what happens next, or what it could mean for your money.
(I'm revealing the #1 stock at the heart of this story for free, here.)
I've tracked this story for months, and it's playing out exactly as I predicted.
Next, I believe Elon could launch a new device that kills the iPhone... and hands early investors his biggest payday yet. Potentially 50 times their money.
Love him or hate him, you don't want to miss this.
Best,
Josh Baylin
Frmr. Bloomberg Reporter, Frmr. SAC Capital
Senior Tech Expert, Stansberry Research
P.S. This isn't my first big mobile prediction, by the way.
In 2004, three years before the iPhone, I told Congress a smartphone was coming that would change our lives forever. Anyone who put $1,500 into Apple back then could be sitting on about $1.2 million today.
A few years later at SAC Capital, I told my former boss, billionaire Steve Cohen, that Apple wouldn't sell 1 million iPhones, as every other analyst predicted... but 1 billion.
I was laughed out of the room. But I was right both times.
Here's my next big call, and details on where to put your money now.
Apple’s $5.7 Billion Patent Verdict Raises a Bigger Royalty Question
Authored by Sam Quirke. Article Published: 10/1/2026.
Key Points
- Apple faces a $5.7 billion jury verdict after jurors found that its Taptic Engine infringed claims in two Taction Technology patents, and Apple plans to appeal.
- Apple has the financial capacity to absorb a one-time award, but a potential ongoing royalty on affected products could create a longer-lasting margin risk.
- Apple retains a Moderate Buy consensus among analysts, although its elevated valuation leaves less room for legal or operational setbacks.
- Special Report: Grand Canyon Discovery Reshapes America's Energy Tax Credits.
Shares of Apple Inc. (NASDAQ: AAPL) fell 2.66% on Tuesday, Sept. 29, extending a decline from the prior session despite having set an intraday all-time high on Tuesday, Sept. 22. A federal jury’s $5.7 billion verdict against Apple on Friday, Sept. 25, added a fresh legal overhang. It also served as a reminder that even the largest companies can see their stocks spooked by a single piece of legal news.
The ruling ordered the tech giant to pay more than $5.7 billion to Taction Technology after finding that Apple’s Taptic Engine infringed claims in two patents covering haptic-feedback technology used in iPhones and Apple Watches. Apple has said it will appeal. A $5.7 billion one-time payment might be material in absolute terms, but Apple has substantial financial capacity to absorb it, having generated nearly $117 billion in operating cash flow during the first nine months of fiscal 2026.
Ian Cooper Unveils a Simple Options Trade Strategy (Ad)
Ian Cooper's newest strategy targets triple-digit returns in just 9 days. It doesn't work every time, but a 73% win rate and 2,671% return on capital stand on their own.
Ian is breaking down the full strategy and offering his newest report at no charge.
Get the free report and see the full options strategy nowHowever, here is where the verdict gets interesting: The real threat isn't the one-time payout. It's the possibility of an ongoing royalty on every affected iPhone and Apple Watch sold going forward. That scenario would put material pressure on hardware margins over time, which is why some investors are treating this verdict as more than a legal sideshow.
Why the Royalty Risk Matters More Than the Verdict
Thankfully for investors, Apple's scale makes the headline figure look worse than the underlying economics. The company can comfortably absorb a multibillion-dollar charge without threatening its balance sheet, buybacks or ability to invest in new products.
A recurring royalty is different. It would affect the economics of every affected device for years rather than hitting earnings once. The market, therefore, has good reason to focus less on the Sept. 25 award and more on what Apple might ultimately have to pay to keep using the technology.
Apple’s Pricing Power Still Supports the Bull Case
For now, Apple's pricing power remains the foundation of the broader bullish thesis. The company has consistently raised prices on iPhone Pro models without losing meaningful volume. It has done so while managing component-cost inflation and maintaining solid gross margins.
Services revenue, which has started to exceed hardware revenue in some quarters, provides a diversification buffer that didn't exist five years ago. Recent iPhone Pro demand indicators remain healthy, with lead times elevated in several markets—a backdrop consistent with pricing power holding up.
The bulls argue that this cash-generation capacity can absorb the $5.7 billion hit. The real constraint is whether Apple can avoid paying a recurring royalty, and the appeal offers a credible path forward.
A federal district court originally granted Apple summary judgment of noninfringement in 2023, but the U.S. Court of Appeals for the Federal Circuit vacated that ruling on Aug. 13, 2025, and sent the case back for further proceedings. A successful appeal or a settlement that avoids a significant ongoing royalty would remove much of the overhang. Under that framework, the verdict creates an opportunity for a settlement that removes longer-term uncertainty without gutting margins.
Valuation Leaves Less Room for Legal Setbacks
The bearish argument continues to rest on valuation and execution risk, and bears will consider the Sept. 25 verdict another point in their favor. When you consider how Apple's valuation continues to look stretched compared with historical levels, there’s not much room for stumbles like this.
If hardware margins were compressed by new recurring royalty payments, current upgrade cycles disappointed, or component costs rose faster than pricing could offset them, the stock’s valuation could contract rather sharply.
Bears will also argue that Apple’s new premium devices may raise average selling prices without generating enough incremental earnings growth to justify the current valuation. A legal headwind only compounds that concern when the stock is already priced at an elevated multiple.
Yet here is the critical detail: The vast majority of analysts remain bullish on Apple, and the MarketBeat consensus rating is still a Moderate Buy, even after the verdict. That consensus suggests Apple's fundamental economics are strong enough to weather the verdict without a material shift in the investment case.
A Legal Scare, Not Yet a Thesis Breaker
That said, the $5.7 billion verdict is a real risk, and the royalty question deserves close monitoring as the appeal proceeds. But Apple's pricing power, broader revenue growth and fortress balance sheet give the company substantial resources to address the issue through an appeal, settlement or the kind of margin management it has proven adept at executing.
For those who are bullish on Apple over the long term, the verdict might actually be creating a window for an entry point, as it’s almost certainly not a reason to abandon the bullish thesis. Investors comfortable with Apple’s valuation at current levels might therefore see the recent pullback as a buying opportunity dressed up as a legal scare.
3 Small-Cap Stocks With Catalysts That Could Put Them in the Spotlight
Authored by Nathan Reiff. Article Published: 10/5/2026.
Key Points
- Investors are increasingly looking beyond mega-cap tech stocks toward small-caps with improving fundamentals and unique growth catalysts amid wide valuation gaps.
- Ascentage Pharma and Maze Therapeutics are biotech companies with promising oncology and kidney disease drug pipelines, strong cash positions, and Buy ratings from analysts.
- Pagaya Technologies has shown strong revenue and net income growth through AI-driven credit decisions, earning a bullish consensus price target from Wall Street analysts.
- Special Report: Grand Canyon Discovery Reshapes America's Energy Tax Credits.
Small-cap companies are accustomed to living in the shadow of mega-cap technology firms, but there are signs that the market backdrop could be changing for some of these companies. Investors have been looking beyond the Magnificent Seven for growth opportunities, and smaller companies with improving fundamentals, unique business models or other noteworthy catalysts may finally have an opportunity to attract investor attention.
Although interest rates have recently risen, this could give contrarian investors a chance to buy in before economic conditions improve further for small companies seeking financing. At the same time, the valuation gap between large- and small-cap stocks remains atypically wide, which could create opportunities to rotate into smaller names if the risk environment improves. Of course, small-cap stocks still come with their share of risks, including volatility, operational concerns and cash flow challenges. With all this in mind, the three companies below stand out for their fundamentals and unique catalysts, which could support future growth.
An Oncology Biotech Poised for a Commercial Breakthrough
The Rumors About Elon’s Next Move Are Spreading Fast (Ad)
Rumors are circulating that Elon Musk is preparing to acquire three publicly traded companies.
Dr. Mark Skousen, who met Musk in person and called the SpaceX listing months early, says he has identified all three targets in what he calls Elon's $2.1 Trillion Hit List.
See the three companies before the rumors become headlines.
Get the details on all three companies nowAscentage Pharma Group International (NASDAQ: AAPG) is transitioning from a clinical-stage biotech company into a more established commercial oncology business, thanks to its primary commercial product, olverembatinib, which is used to treat certain types of leukemia. The company has also expanded its pipeline and has hematology and oncology candidates in various stages of clinical development.
For the first half of 2026, revenue climbed more than 29% year over year (YOY) to $44.5 million, fueled by $41.6 million in product sales. The company's reach is global, although its business has been particularly strong in China. At the same time, it held more than $279 million in cash and equivalents as of midyear, providing a runway through the end of 2027.
Ascentage carries many of the typical risks and opportunities associated with growth-stage biotech firms. It remains unprofitable and is spending cash quickly, as research and development costs increased by nearly one-third YOY in the first half of 2026. The company also anticipates significant capital needs to support commercialization efforts going forward. Its success hinges on key trial results and approvals for its pipeline.
Nonetheless, the fact that commercial revenue is scaling and the company has strong drug prospects has earned it a unanimous Buy rating from 10 analysts, along with a price target of $46.43.
Multiple Promising Drug Candidates and Strong Financials for Maze
Another biotech company with upcoming clinical milestones that could drive growth, Maze Therapeutics (NASDAQ: MAZE) focuses on genetically driven diseases. Its primary drug candidate is MZE829, which targets APOL1-mediated kidney disease (AMKD), a condition affecting more than 1 million people in the United States alone. Maze reported positive topline data from a Phase 2 trial of MZE829 in March 2026, a critical step toward potential approval and eventual commercialization.
The company also stands out because of its additional drug candidates. Additional Phase 2 studies for other drugs in development are expected in the coming quarters. While the results of these pending trials are uncertain, the company's more diversified pipeline helps it stand out from some of its competitors.
Maze also distinguishes itself through its financial position: the company had about $528 million in cash and equivalents as of its most recent earnings report, thanks to a successful capital raise. This should provide sufficient runway to extend operations into 2029 while limiting near-term financing risks. The combination of a stronger financial position and promising drugs in development has led analysts to overwhelmingly rate MAZE shares a Buy. As with AAPG, Wall Street expects MAZE shares to more than double.
Pagaya's Volumes and Profitability Could Win Over Skeptics
Fintech firm Pagaya Technologies Ltd. (NASDAQ: PGY) has successfully integrated artificial intelligence and data analytics to help lenders make credit decisions. The company reported strong revenue growth of about 19% YOY in the latest quarter, while GAAP net income surged by more than 180% over the same period.
The company is performing well on multiple fronts: Partners have sent more volume, revenue from fees less production costs is soaring, and expenses have remained stable. Because it earns up to about 5% in net fees per loan issued, Pagaya can operate an asset-light business model that supports profitability. In addition, higher volume has helped ease lingering concerns that Pagaya may not have enough investors willing to take on the loans.
To be sure, Pagaya remains a riskier investment than some other fintech names because of its size, risks in the overall funding market, the potential for a macroeconomic slowdown and other factors. However, Wall Street analysts are heavily bullish on PGY shares and have assigned a fairly lofty consensus price target of $31.25 per share.
This email content is a paid advertisement from Stansberry Research, a third-party advertiser of MarketBeat. Why was I sent this message?.
This ad is sent on behalf of Stansberry Research, 1125 N Charles St, Baltimore, MD 21201. If you would like to optout from receiving offers from Stansberry Research please click here.
If you have questions or concerns about your subscription, feel free to email our South Dakota based support team at contact@marketbeat.com.
If you would no longer like to receive promotional emails from MarketBeat advertisers, you can unsubscribe or manage your mailing preferences here.
Copyright 2006-2026 MarketBeat Media, LLC. All rights protected.
345 North Reid Place #620, Sioux Falls, S.D. 57103-7078. United States of America..



No comments:
Post a Comment