I don't write about politics. Until today. 
Microsoft's AI Spending Didn't Change—Wall Street's View of It DidWritten by Chris Markoch on October 1, 2026 
Key Points
- Microsoft shares rebounded sharply in the third quarter as Azure growth and accelerating Copilot adoption helped change investor sentiment around AI spending.
- Microsoft 365 Copilot surpassed 30 million paid seats in fiscal Q4, while Azure and other cloud services revenue grew 43% year over year.
- Microsoft still faces risks from elevated Treasury yields and heavy AI capital spending, making future usage and monetization trends important to watch.
- Special Report: How NASA Contracts Have Sent Small Space Stocks Sharply Higher

Microsoft (NASDAQ: MSFT) investors have owned two different companies in 2026. Or at least, they've been told two very different stories about the same one. In the first half of the year, the story was fear. AI would disrupt software. Copilot was an expensive add-on nobody would pay for. Data center spending looked out of control. Not surprisingly, by late June, MSFT had sunk to roughly $355. But in the second half, the story is about discipline. Microsoft shares rose more than 36% in the last three months and turned positive for the year. It's a remarkable comeback for a stock that had fallen 20%. The reason why may come as a surprise. The same capital spending that scared investors in the spring has become a selling point. To illustrate that point, CNBC's Jeff Marks now calls Microsoft "one of the few hyperscalers that is living within their means." So what actually changed? Less than you might think. The business was improving the whole time. What flipped was the narrative investors used to interpret it. Here's how the change in sentiment happened, and what the chart says about what comes next.
Data centers appeared in about 164 campaign ads last August alone, and a new Pew survey found 50% of Americans believe they raise home energy costs.
One producer already answering the power question generated $2.3 billion in operating cash flow and $1.2 billion in net income in the first half of 2026, backed by a multi-year Palantir partnership that improves well performance and cuts operational surprises. See why this cash-rich Palantir partner is worth watching now
Copilot Growth Was Already Hiding in Plain SightMicrosoft's fourth quarter of fiscal 2026 ran from April through June, which is the exact stretch when the stock slid toward its lows. But the Q4 earnings report showed that during those same three months, Microsoft was delivering results on Copilot, which had been considered a major obstacle. Microsoft ended the quarter with 30 million paid Copilot seats, up 10 million in a single quarter and the fastest seat growth since Copilot launched. Q4 revenue increased 18% year-over-year to reach $90 billion. In other words, customers were buying Copilot at a record pace. At the same time, investors were dumping the stock on fears that nobody would. Investors simply didn't have the data yet. Same Spending With a Different SentimentSpending tells the same story. Earlier this year, Microsoft's data center budget was treated as a liability. Investors questioned whether hyperscalers could generate sufficient returns on their enormous AI investments. Microsoft didn't slash spending to win them back. Instead, it brought more capacity online, delivered 43% revenue growth from Azure and other cloud services, and remained free cash flow positive. That's the key point. Capital expenditure (CapEx) didn't change. The return on investment story did. Once investors saw capacity turning into revenue, "reckless" became "disciplined." Analysts followed the price. Stifel upgraded MSFT from Hold to Buy on Sept. 22, arguing that the company had decisively turned a corner. Then came the Copilot redesign on Sept. 25. On Wednesday, Sept. 30, Piper Sandler raised its price target to $610 from $550 while maintaining an Overweight rating, saying the Copilot narrative had “improved materially” this year. Those upgrades arrived after the stock had rallied more than 40% off its lows. That's how sentiment changes work. Analyst consensus confirms a move. It rarely starts one.
The Chart Shows a Rally Catching Its BreathAfter the post-earnings move, Microsoft has spent about two months trading mostly between $485 and $520. Meanwhile, the 50-day simple moving average has climbed steeply to about $480. That's a constructive setup. Price is digesting its gains while the trend catches up underneath it. Momentum has cooled, though. The MACD line sits at 7.02, just below its signal line at 7.35. The histogram is only slightly negative. Put simply, the stock isn't overheated. It's resting. A MACD crossover back above the signal line would suggest the consolidation is resolving higher. If that happens, the next major test is the 52-week high near $554. On the downside, the rising 50-day average near $480 is the level to watch. 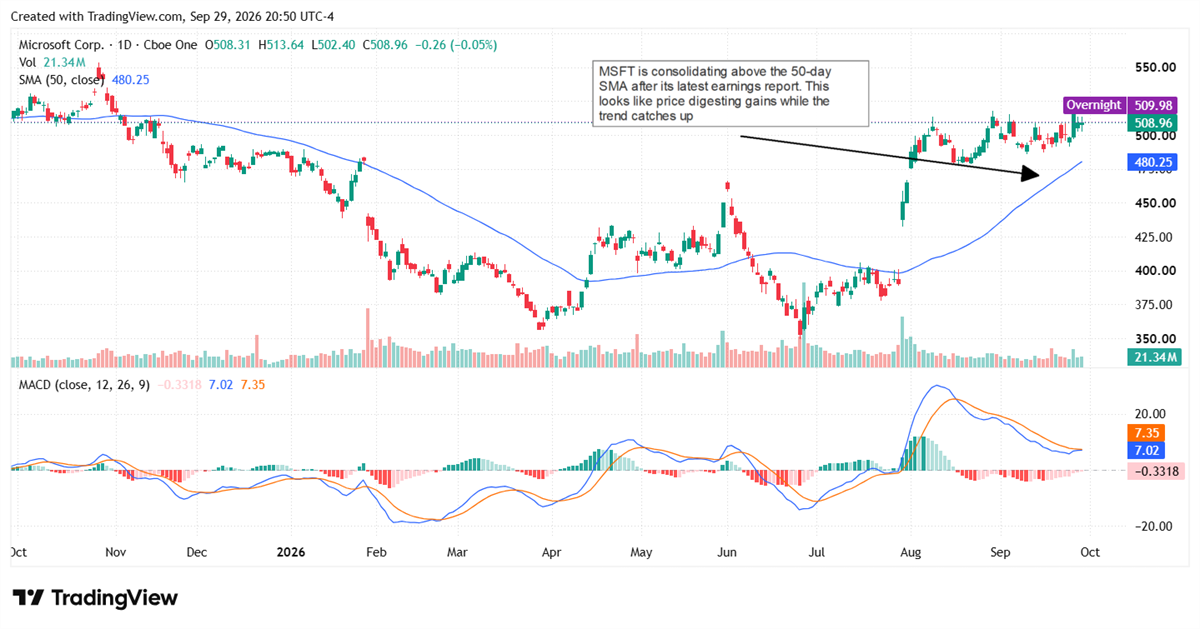
The Risk Now Is Chasing the New NarrativeSentiment whiplash cuts both ways. Investors who sold near $355 on a bad story can just as easily overpay on a good one. The macro backdrop deserves respect, too. The 10-year Treasury yield advanced to 5.25%, its highest level since 2007. That puts pressure on big tech valuations. The next chapter of this story will be written in usage data. The more advanced Cowork, Code, and Autopilot features shift to usage-based pricing. That's the metric to watch when Microsoft reports again in late October. MSFT Outlook: Fundamentals Still Matter More Than SentimentMicrosoft didn't become a great business in August. It was already one in June. The only thing that changed was how investors chose to tell the story. That's the real lesson for patient investors. Narratives swing quickly, while fundamentals compound quietly. The next time the story around Microsoft turns, check whether the numbers do too. Read this article online › Read More
Did you like this article?  
|



No comments:
Post a Comment