| Unsubscribe |
Fed Chair Kevin Warsh just shockingly raised rates…
Fixed income investors are now at the mercy of a central bank stuck between higher interest costs and higher inflation.
The only likely winner in this scenario is gold, and specific gold securities.
And right now, one of the world’s best gold mines is yielding up to 10%.
That’s real income that can help any investor protect their wealth from whatever comes next.
The only caveat:
The longer you wait to own this security, the higher the risk that the market bids up the price.
Don’t wait…
Get started now with this high yield gold security.
Best,
Garrett Goggin, CFA, CMT
Lead Analyst and Founder, Golden Portfolio
But their potential 10% yield is what caught my attention.
The Rothschilds, Vanguard, and BlackRock are already in. Join them here.
Copper Is the AI Trade No One Priced In—3 Miners With the Most to Gain
Authored by Bridget Bennett. First Published: 9/8/2026.
Key Points
- Copper futures hit a record above $6.70 a pound in August as structural demand from data centers, grids, EVs and defense outpaces mine supply limited by falling ore grades.
- Copper's futures curve has flipped into backwardation, with buyers paying a premium for immediate delivery, signaling a genuine physical shortage rather than just speculation.
- Miners like Freeport-McMoRan, Hudbay Minerals and Trekor Metals offer leveraged exposure to rising copper prices through fixed costs, though smaller names carry greater execution risk.
- Special Report: SpaceX is offering you shares. Don't take them.
Copper spent two years as the least interesting story in the commodity complex. Gold took the headlines, and semiconductors took the capital. Copper simply kept grinding higher until COMEX futures printed a record above $6.70 a pound in August. Prices have eased since then as rising oil prices and bond yields pressured the demand outlook, but the trend has not broken.
The record is not the interesting part. The arithmetic underneath it is. Demand from data centers, grid replacement, electric vehicles and defense budgets is compounding at the same time that mine supply is constrained by falling ore grades and permitting timelines measured in decades. That is not a problem that price can solve quickly, and it lands directly on the income statements of the companies pulling copper out of the ground.
Copper's Supply Problem Is Structural, Not Cyclical
Here’s Why Trump Won’t End The Iran War (Ad)
Trump has called an Iran deal close 38 times since the war began, yet the fighting keeps flaring back up.
One day it's a ceasefire, the next it's bombs again. The back and forth may be masking a bigger story most investors are missing.
See the real reason this conflict may never fully end.
Uncover the real reason Trump may never end this warRoss Givens, lead strategist at Traders Agency, treats copper as a three- to five-year position rather than a trade. He is a technician by habit, sizing entries based on consolidation patterns and signs of quiet accumulation instead of headlines. He walks members through that analysis live each week inside his Black Ops Trading Club. Applied to copper, his view is that the AI buildout has been priced into the obvious names first. NVIDIA (NASDAQ: NVDA) is already the most valuable company in the world. The physical layer underneath it has not attracted the same level of investment, even though none of it can be built without wires, transformers and substations.
The tightness is measurable. The U.S. Geological Survey estimates that miners have pulled roughly 700 million metric tons of copper out of the ground across all of recorded history. S&P Global has cited industry estimates that the world will need to mine that much again within about 22 years just to sustain baseline growth, and that figure ignores electrification entirely. Ore grades are working against that math, having fallen roughly 40% globally since 1991. Work compiled by analyst Thierry von Arvy shows supply flattening early next decade while demand continues to climb. New mines take well over a decade to move from discovery to production, so no amount of drilling can close the copper supply deficit within that timeframe.
The Futures Curve Is Signaling a Physical Copper Shortage
Futures curves normally slope upward because storage and financing cost money. Copper's curve has inverted, a condition traders call backwardation, meaning buyers are paying a premium to take metal today rather than wait for December delivery. Nobody does that for metal that is readily available in a warehouse.
Backwardation steepened sharply across Western exchanges this year as traders rerouted metal into U.S. warehouses ahead of the possibility that refined cathode could be swept into the tariff regime. Once that copper lands in a bonded warehouse, it is effectively stuck there, draining supplies from the rest of the world even as domestic inventories swell. A surplus that looked comfortable on paper a year ago now appears balanced at best outside the United States and closer to a deficit if those flows continue.
Freeport-McMoRan Offers the Cleanest Operating Leverage
Freeport-McMoRan (NYSE: FCX) is the largest U.S.-listed name in the group and the biggest domestic producer of refined copper, with stakes in Grasberg, Cerro Verde and Morenci. Shares set a record close in late August and trade near the upper end of their 52-week range, while institutions hold four-fifths of the float.
The reason miners move more sharply than the metal is operating leverage. All-in sustaining costs are largely fixed once a mine is running, so every incremental dollar in the copper price flows toward the margin line. Freeport's first-half net income climbed 65% year over year on that dynamic, while U.S. mining operations more than doubled their contribution to operating income. Givens argues that the market is valuing the company based on today's copper price rather than the price he expects.
Hudbay Minerals and Trekor Metals Add Torque to the Copper Trade
Hudbay Minerals (NYSE: HBM) is the mid-cap version of the same exposure, anchored by Copper Mountain in British Columbia and complemented by operations in Peru. It posted record trailing-12-month adjusted EBITDA last quarter.
Trekor Metals (NYSEAMERICAN: TGB), renamed from Taseko Mines in June, is the small-cap option.
Gibraltar provides the production base, while Florence Copper in Arizona poured its first cathode in February, turning the company into a two-mine producer with a domestic asset at a moment when Washington is pushing hard to develop homegrown supply chains.
Institutional ownership thins out further down the list, which Givens interprets as a constraint on large funds rather than a verdict on the businesses.
For broader exposure, the Global X Copper Miners ETF (NYSEARCA: COPX) has nearly doubled over the past year.
Where the Copper Trade Could Break Down
Not everyone treats this price move as a clean read on demand. Some analysts argue that a meaningful portion of the rally is a policy premium tied to tariff uncertainty rather than consumption, and that a final ruling could cool prices simply by ending the uncertainty. Stanley Druckenmiller's Duquesne Family Office added to Southern Copper (NYSE: SCCO) last quarter, though he has publicly favored the metal itself over the equities.
Execution risk also separates these three companies. Freeport's copper is already coming out of the ground. Trekor's valuation depends on a ramp-up that still has to meet its targets, and the smallest name would fall hardest if copper prices stall.
Watch the spread between spot and December delivery. As long as buyers keep paying a premium for metal today, the shortage is real, and copper mining stocks remain leveraged to it.
Uber’s Wayve Deal Shows How It Wants to Win Without Building Cars
Authored by Jeffrey Neal Johnson. First Published: 9/8/2026.
Key Points
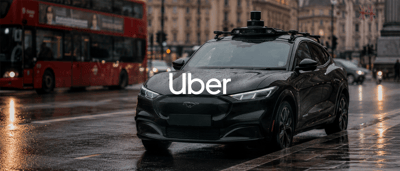
- Uber launched its first international supervised autonomous ride-hailing service in London on Sept. 3, using Wayve-powered Ford Mustang Mach-E vehicles.
- Uber is pursuing an asset-light strategy, avoiding vehicle manufacturing costs by partnering with autonomous technology and hardware providers to scale globally.
- Strong free cash flow, rising EBITDA margins, and heavy institutional ownership support a moderate buy consensus with roughly 36% implied upside.
- Special Report: SpaceX is offering you shares. Don't take them.
The market often misinterprets the structural evolution of logistics networks, valuing them based on legacy models rather than future capabilities. This dynamic is currently playing out with Uber Technologies, Inc. (NYSE: UBER). On Sept. 3, Uber launched its first supervised autonomous ride-hailing service in London. By deploying all-electric Ford Mustang Mach-E vehicles powered by Wayve's AI Driver, Uber is demonstrating a clear pivot in its business model.
Rather than absorbing the heavy capital expenditures required to manufacture proprietary autonomous vehicles, Uber is positioning itself as the commercialization and distribution layer for third-party technology. This asset-light approach allows Uber to move toward long-term autonomous margins while avoiding the risks of automotive manufacturing. Investors assessing the company's current valuation may notice a disconnect between the traditional human-driven logistics multiple and the highly scalable, AI-integrated hybrid network it is building.
Steering Clear of Manufacturing
Here’s Why Trump Won’t End The Iran War (Ad)
Trump has called an Iran deal close 38 times since the war began, yet the fighting keeps flaring back up.
One day it's a ceasefire, the next it's bombs again. The back and forth may be masking a bigger story most investors are missing.
See the real reason this conflict may never fully end.
Uncover the real reason Trump may never end this warUnderstanding the mechanics of the Wayve partnership reveals why this strategy appeals to institutional capital. Wayve uses an AV2.0 approach based on mapless, hardware-agnostic artificial intelligence (AI) that learns from complex environments rather than relying on traditional hand-coded rules. This adaptability is critical in a regulatory and geographic maze like London, where mapping every variable is nearly impossible.
The structural advantage for Uber rests on its deliberate avoidance of hardware development. Developing self-driving cars requires billions of dollars in research, development and manufacturing overhead. By supplying localized rider demand and the routing network, Uber allows partners like Wayve to focus on the intelligence, while original equipment manufacturers such as Ford (NYSE: F) and Nissan (OTCMKTS: NSANY) handle the hardware. More than 140,000 London riders have already opted into the service, suggesting that consumer adoption barriers may be lower than previously anticipated.
This strategy extends well beyond a single city. Uber participated in Wayve's recent $1.5 billion funding round, aligning the companies' financial interests and securing global scaling rights across 12 planned markets. With upcoming integration plans for the Nissan LEAF and partnerships with more than 30 external autonomous developers, Uber is on track to facilitate autonomous trips in up to 15 cities by the end of 2026. This approach allows Uber to scale its autonomous offerings globally without the traditional drag of significant capital expenditures.
Refueling With Free Cash Flow
An asset-light model relies heavily on network density and the ability to generate liquidity without significant internal cash burn. Recent financial disclosures highlight how this transition is already reflected in profitability metrics. During the second quarter of 2026, Uber generated about $2.8 billion in free cash flow and reported gross bookings of nearly $58.0 billion. Bookings increased 24% year over year, providing the liquidity framework required to fund external artificial intelligence integrations.
The ongoing shift toward third-party integration directly supports expansion of the earnings before interest, taxes, depreciation and amortization (EBITDA) margin. Adjusted EBITDA grew 33% year over year to $2.8 billion for the quarter, pushing the margin to 4.9% from 4.5% a year earlier. By allowing venture capital and external partners to absorb the research and development costs of autonomous driving, Uber preserves its cash flow to reinvest in market share and core platform density.
This density strategy is evident in concurrent corporate actions, including the ongoing €41.50-per-share (approximately $46) takeover offer for Delivery Hero. Acquiring complementary logistics networks would widen the company's multi-vertical distribution funnel. A denser network for food and freight delivery would create immediate, practical deployment routes for future autonomous fleets. It would also allow Uber to maximize vehicle utilization across a 24-hour cycle, routing autonomous cars for passenger transport during peak hours and logistics delivery during off-peak periods.
Valuations Ready to Accelerate
Capital flows often lead retail sentiment, and the structural support for Uber rests heavily on institutional accumulation. Institutional investors currently hold roughly 80% of the public float. Over the trailing 12 months, these buyers initiated inflows of nearly $39.12 billion, far outweighing outflows of roughly $10.36 billion. Entities such as the Virginia Retirement Systems hold large positions, suggesting a long-term horizon aligned with Uber's autonomous transition.
From a valuation perspective, Uber trades near $76 with a trailing price-to-earnings (P/E) ratio of approximately 16.8. Compared with broader technology-sector platforms that often command multiples well above 30, the current pricing implies that the market still views Uber as a human-reliant logistics business. As the percentage of autonomous trips increases, the marginal cost of routing a vehicle could fall substantially, improving the company's unit economics.
Sell-side analysts appear to be factoring in this evolution in margins. Of the 42 analysts covering Uber Technologies, Inc., 34 maintain a Buy rating, resulting in a consensus rating of Moderate Buy. A consensus price target near $104 suggests anticipated upside of roughly 36% from current trading levels.
The recent London rollout serves as tangible proof of concept for the broader analyst community, validating the operational feasibility of replacing human drivers with software in highly congested urban environments.
Plotting the Next Destination
The integration of Wayve's technology in the United Kingdom provides a clear template for how ride-hailing networks can achieve long-term profitability. Transitioning directly from human drivers to fully autonomous fleets carries significant regulatory and operational risks. By gradually introducing third-party autonomous vehicles alongside human-driven cars, Uber can maintain consistent reliability while steadily lowering the overall cost per trip.
This hybrid approach de-risks the technological rollout while maintaining the supply density required to serve global demand. The combination of strong free cash flow, deep institutional backing and an expanding global network of autonomous partners creates a compelling fundamental setup. Uber is positioning itself not as a car manufacturer, but as the essential operating system for global movement. Investors analyzing the shifting mobility sector may want to add Uber to their watchlists as the market begins to factor in the long-term margin expansion associated with its software distribution capabilities.
This email is a sponsored email provided by Golden Portfolio, a third-party advertiser of MarketBeat. Why did I receive this email content?.
If you need help with your subscription, feel free to email MarketBeat's U.S. based support team at contact@marketbeat.com.
If you would no longer like to receive promotional emails from MarketBeat advertisers, you can unsubscribe or manage your mailing preferences here.
© 2006-2026 MarketBeat Media, LLC. All rights protected.
345 North Reid Place, Sixth Floor, Sioux Falls, South Dakota 57103-7078. United States of America..



No comments:
Post a Comment