| Unsubscribe |
Editor's Note: Marc Chaikin's last major recommendation for our readers drew a huge response. Today he's back with a new #1 retirement pick — and he's sharing the details free, no email or credit card required.
Dear Reader,
In 2014, I recommended my readers put a big chunk of their retirement money into one stock: Nvidia.
Anyone who followed that recommendation is up more than 45,000% at this point.
I've spent 60 years on Wall Street. I built one of Wall Street's most well-known tools – Chaikin Money Flow indicator. Even Jim Cramer said he's learned never to bet against me given my decades long track record of picking stock market winners.
Now I've unearthed what I believe could be an even better retirement stock for the years ahead — and today I'm going to share the details, totally free of charge. (Click here to get the specifics.)
Here's the single biggest reason why.
This company is sitting on three fast-growing businesses, and each one could be spun off into a separate publicly traded company. If that happens — and I believe the next 12 to 24 months are when it could — anyone holding this stock beforehand could have those spinoff shares deposited into their account automatically.
In other words, one ticker today could become three tickers tomorrow. That's the kind of setup that almost never appears in a stock this size.
And Wall Street still considers this company a "dark horse" in the AI race.
It shouldn't when its autonomous vehicle division is already being called the "undisputed leader" against Tesla. And it's streaming service has 10X greater reach than Netflix.
Yet most investors have no idea it's even in those businesses.
The market is pricing this as one ordinary company instead of three extraordinary ones.
There's also a dividend — which is rare for a high-growth technology company. Most AI names pay nothing at all.
In my new presentation, I explain everything you need to know — including why a major event that just occurred in AI's frontier labs put this company at the top of my buy list.
That's why I believe this might be the greatest retirement stock in America right now.
Click here to get the details of this amazing stock, totally free of charge.
No credit card, no email required.
Sincerely,
Marc Chaikin
Founder, Chaikin Analytics
P.S. A high-growth tech stock that pays a dividend is a rarity — this one is the exception. To be in line and claim your share of the next $2.6 billion payout, you need to own at least one share by September 4th. Click here so you don't miss the cutoff.
Smart Money Shifts: U.S. Bancorp Pairs Tech With Yield
Submitted by Jeffrey Neal Johnson. First Published: 9/14/2026.
Key Points
- U.S. Bancorp recently completed a live cross-border payment using its USBDC stablecoin on the Stellar blockchain and raised its annualized dividend to $2.16 per share.
- The bank reported diluted earnings per share of $1.35, beating estimates, with a payout ratio near 43% supporting continued dividend growth and a $5 billion buyback program.
- U.S. Bancorp's dividend increase and forward yield of about 3.5% outpace rival Truist Financial, which has kept its dividend unchanged amid sector-wide margin pressure.
- Special Report: SpaceX is offering you shares. Don't take them.
Income investors often face a frustrating trade-off between securing dependable cash yield today and backing companies that are building forward-looking technology. Most banks rarely deliver both. Legacy clearing networks and regulatory compliance burdens can slow regional banks, leaving lucrative corporate payment corridors open to modern fintech disruptors.
U.S. Bancorp (NYSE: USB) is challenging that old assumption. On Sept. 9, 2026, the Minneapolis-based institution completed a live cross-border payment using USBDC, its proprietary U.S. dollar-backed stablecoin, settled across the public Stellar (XLM) blockchain.
She knows the real him - and why he almost walked away (Ad)
Porter Stansberry nearly canceled the entire project. When he first saw the claimed returns - only one down year in nearly two decades and total gains of almost 2,000% - his immediate reaction was disbelief.
It took a trusted friend's personal vouching for Emmet Savage and a face-to-face trip to Ireland to change his mind. The full documentary, Investigating Project Prophet, is now live.
Watch the full story and see the verified track record for yourselfAlongside this breakthrough, the board approved an estimated 3.85% increase to its cash dividend, lifting the annualized distribution to $2.16 per share. This combination demonstrates that an established bank can modernize its payment infrastructure while maintaining disciplined capital allocation for shareholders.
U.S. Bancorp Takes Payment Plumbing On-Chain
Moving money across borders has long depended on traditional correspondent banking relationships. These arrangements route client capital through multiple intermediary banks using the SWIFT messaging network. That structure creates friction: global transfers typically require two to five business days to clear, incur layered processing fees and stop completely outside standard business hours.
U.S. Bancorp tested an alternative model by settling transfers between affiliated bank operations in North America and Europe across the Stellar blockchain. Stellar is a decentralized ledger designed specifically for currency issuance and international payments, and it settles transactions in seconds for a fraction of a cent.
Moving real capital across a public network naturally attracts regulatory attention. To address prudential requirements, U.S. Bancorp developed its internal Digital Asset Platform with integrated administrative controls. Management retains the ability to mint, redeem, freeze and claw back digital units if necessary. This design enables the bank to comply with anti-money laundering regulations while providing around-the-clock liquidity management.
Keeping Commercial Fees Out of Fintech Hands
Business payment services are a key driver of non-interest income for regional banks. When business clients conduct transactions abroad or pay overseas vendors, currency conversions and wire fees generate high-margin revenue. Over the past decade, non-bank fintech platforms have steadily captured payment volume by offering faster, cheaper settlement alternatives.
By bringing public-ledger infrastructure in-house, U.S. Bancorp is directly defending this corporate revenue pool. Corporate treasurers prioritize real-time liquidity and automated cross-border collateral mobility. When a full-service institution can clear international payments almost instantly and at low cost, commercial clients have fewer incentives to shift deposits to third-party payment competitors.
This connects directly to U.S. Bancorp's broader payments infrastructure, including its talech point-of-sale platform and Bento for Business corporate expense services. Connecting modern payment rails to established customer relationships allows the bank to enhance corporate retention and support fee-based revenue during periods when net interest margin faces broader pressure.
Cash Returns Backed by Disciplined Capital
Technological upgrades hold little appeal for income investors if research and development spending compromises the balance sheet. U.S. Bancorp pairs its modernization efforts with sound financial performance. In its latest quarterly filing, the bank reported diluted earnings per share of $1.35, outpacing consensus expectations of $1.28 and supported by quarterly revenue of roughly $7.69 billion.
Over the trailing 12 months, the company generated approximately $7.57 billion in net income on roughly $29.58 billion in total revenue. These results produced a net margin of about 18.49% and a return on equity of roughly 13.69%. Profitability at this scale provides comfortable financial headroom for the newly established $2.16 annualized dividend. Against trailing diluted earnings per share of around $5.01, the payout ratio stands near 43%, leaving substantial retained earnings to maintain capital adequacy reserves.
Supporting this dividend growth, the board maintains an active $5 billion share repurchase program. Repurchasing company shares at current valuation levels reduces the total share count and provides sustained support for future per-share earnings growth.
Real Dividend Growth Outpaces Stagnant Regional Rivals
A look across the regional banking sector shows a clear divergence in performance among peers. Many mid-sized and large lenders remain constrained by higher deposit costs and cautious credit demand, leading them to freeze dividend growth.
Truist Financial Corporation (NYSE: TFC) serves as a primary point of comparison. Truist has kept its quarterly dividend unchanged at 52 cents per share, representing an annualized payout of $2.08. In contrast, U.S. Bancorp moved its quarterly distribution to 54 cents per share, establishing an attractive forward yield of around 3.5% at current market prices.
This widening payout gap demonstrates how operational efficiency can translate into capital flexibility. While competing regional lenders prioritize defensive expense cuts to protect profitability, U.S. Bancorp is advancing transaction technology while simultaneously expanding cash returns to shareholders.
Reasonable Multiples Meet Modern Banking Plumbing
Trading near $62 per share, U.S. Bancorp is valued at a trailing price-to-earnings ratio of about 12.4 and a forward multiple of roughly 11.9.
Shares trade at about 1.64 times book value, with book value around $37.85 per share. Wall Street analysts maintain a Moderate Buy consensus on the stock, with an average 12-month price target near $67.06 based on reports from 25 analysts.
Prudent investors should recognize the ongoing execution risks. The stablecoin transaction remains an internal pilot across affiliated bank entities, meaning broader deployment to clients will require continued alignment with guidelines from the Fed and the Office of the Comptroller of the Currency.
Regulatory filings also note that CEO Gunjan Kedia sold 27,267 shares in late August 2026, though executive equity ownership across the management committee remains substantial.
Investors focused on building a durable income portfolio might view current price levels as an attractive opportunity to accumulate. U.S. Bancorp delivers an appealing yield of 3.4%, supported by conservative earnings coverage, while offering potential upside as real-world asset tokenization reshapes modern commercial banking.
GameStop’s Comeback Case Is Getting Interesting, But eBay Still Looks Stronger
Submitted by Thomas Hughes. First Published: 9/10/2026.
Key Points
- GameStop’s collectibles segment surged in Q2 and became its largest sales category, but total revenue still declined sharply as video games and pre-owned sales contracted.
- GameStop’s large eBay stake, cash-like assets and improved profitability give the stock a different story, but its retail strategy remains unclear.
- eBay offers the cleaner operating comparison, with steadier growth, capital returns, analyst coverage and its own exposure to collectibles and AI tools.
- Special Report: SpaceX is offering you shares. Don't take them.
GameStop’s (NYSE: GME) Q2 2026 results offer intriguing details suggesting it may be time to take the stock seriously. Maybe. The critical details lie within the Collectibles segment, which has long been the company’s growth focus. The segment grew 57% year over year to account for 45.1% of sales and is expected to continue growing. It also contributed to the company’s profitability, but that may not be enough to sustain market momentum.
As encouraging as the news is, Collectibles still represent less than 50% of the business. The remaining segments are in sharp contraction, and there aren’t many other reasons to want to own the stock. Collectibles are unlikely to ever eclipse the company’s strong games and hardware business, raising the question of what investors are really getting. As it stands, the company increasingly looks like a collectibles retailer, a cash-rich holding company, and an eBay (NASDAQ: EBAY) investor, while eBay remains by far the cleaner operating business. eBay is growing, producing steadier profits and, more importantly, generating cash in a way that supports capital returns.
She knows the real him - and why he almost walked away (Ad)
Porter Stansberry nearly canceled the entire project. When he first saw the claimed returns - only one down year in nearly two decades and total gains of almost 2,000% - his immediate reaction was disbelief.
It took a trusted friend's personal vouching for Emmet Savage and a face-to-face trip to Ireland to change his mind. The full documentary, Investigating Project Prophet, is now live.
Watch the full story and see the verified track record for yourself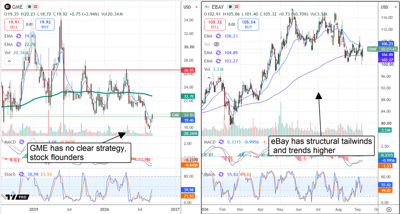
GameStop Rises After Better-Than-Expected Results
GameStop issued an arguably better-than-expected Q2 report, but there isn’t much strength to be seen. The company’s $790.2 million in revenue was slightly above consensus but down nearly 20% from last year, reflecting comparisons with last year’s console launches, store closures and its exit from France. Collectibles was the strongest segment, offset by a 47% contraction in Software and a 32% decline in Hardware and Accessories. Neither decline is expected to end soon.
Software and hardware sales are impaired for numerous reasons, including consumer headwinds and AI. AI and the cloud aren’t expected to replace console-based gaming, but they are changing the environment, primarily through their impact on costs. High demand for DRAM and memory is pushing console prices higher, leading owners to hold on to older models longer, potentially indefinitely. The shift toward cloud-based games also raises questions about longevity: cloud-based games can disappear, but a disc you own lasts forever, more or less.
Profitability is a factor that investors should note. Not only is the core business generating profits, but its substantial eBay holding and cash position also contribute to results. The takeaway is that GameStop has potential, but the strategy remains murky, and risks abound. Profitability and collectibles strength are likely to be inconsistent. Looking ahead, investors can expect GameStop’s core business to continue floundering, Collectibles to offset some of that weakness and eBay to continue driving value for investors.
Analysts and Institutions Say eBay Is a Better Choice
GameStop’s analyst and institutional activity suggest an improvement may be underway, but it shows little confidence. MarketBeat tracks a single analyst with a current rating, but it is a fresh rating pegged at Hold, up from last year’s Sell. The bad news is that no price target has been given, providing no market impetus. Meanwhile, institutional holdings remain small at about 30%, and short interest remains high at just over 13%.
Conversely, 34 analysts rate eBay at a consensus of Hold, providing stronger conviction in the investment. The data shows a 45% Buy-side bias, with some upside to the consensus target, creating a more favorable risk-to-reward scenario. Critical details include steady coverage, firming sentiment and an uptrend in price target revisions, with recent targets pushing the high end of the range higher. Consensus as of early September suggests about 12% upside for eBay stock, while the high end of $145 represents just over 30% upside.
eBay Has Structural Tailwinds, GameStop Does Not
Looking ahead, eBay’s analyst trends are likely to continue, as the company is forecast to sustain mid-single-digit revenue growth while widening margins. Its catalysts include a sharper focus on key categories, including collectibles and luxury authentication, alongside a greater emphasis on AI. AI is helping internally and, more importantly, is improving the consumer experience, with better listing tools and stronger engagement showing up in sales and profits.
From a technical standpoint, eBay also looks stronger, with its share price holding up better while GME remains vulnerable to another leg lower. The earnings-driven rebound may lead to a fuller recovery, but hurdles remain. The drop to fresh lows in late summer was suggestive, pointing to a market that is losing confidence and appears on track to push prices lower. The only cushion investors have is the cash pile, which accounts for most of the stock’s value.
What the bulls get wrong about GME is that it is no longer a meme stock with the potential for explosive short-covering rallies. While short interest remains high, it is well below the astronomical levels seen during the height of the meme frenzy. The bears are right that core operations are unreliable, hardware and software sales are unlikely to rejuvenate the business, and Collectibles are unlikely to replace them. In this scenario, strategic focus and execution are crucial, and both are severely lacking.
This email content is a paid advertisement provided by Chaikin Analytics, a third-party advertiser of MarketBeat. Why did I get this email?.
This ad is sent on behalf of Chaikin Analytics, 201 King Of Prussia Rd., Suite 650, Radnor, PA 19087. If you would like to optout from receiving offers from Chaikin Analytics please click here.
If you need help with your newsletter, please contact our South Dakota based support team at contact@marketbeat.com.
If you would no longer like to receive promotional emails from MarketBeat advertisers, you can unsubscribe or manage your mailing preferences here.
© 2006-2026 MarketBeat Media, LLC. All rights reserved.
345 N Reid Place #620, Sioux Falls, SD 57103. USA..



No comments:
Post a Comment