| Unsubscribe |
In his most recent interview with The Economist, Elon Musk said that because of AI “money will be irrelevant by the year 2036.”
I can see that happening too.
AI is already displacing millions of jobs.
One report says 40% of all jobs could be automated within the next decade.
When that happens, the government will have no choice but to pay people some sort of Universal Basic Income.
But this could take 20 years to materialize
So while Musk tweets and Congress holds hearings, what are you supposed to do? Wait?
I don't think so.
But you don’t have to. Universal Income already exists.
It's not funded by robots or AI. It's funded by America's oil and gas infrastructure, and it pays 10% a year, 42 times a year, to everyone who holds units.
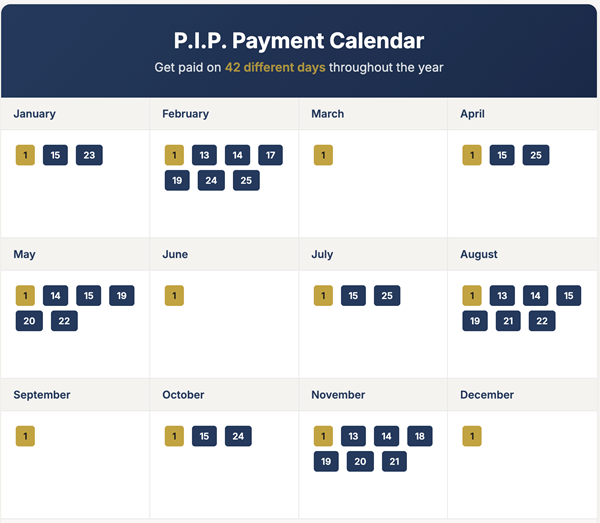
It’s called the Patriot Income Plan, or P.I.P. for short.
And this year it’s expected to pay a record $53 billion in distributions.
Think of it as your own personal sovereign wealth fund, backed by the biggest energy producer on planet earth.
Enroll in P.I.P. before the next payout
P.S. Since 2020, the average partnership in P.I.P. has produced 20% avg. annual gains. That’s in addition to the 10% yield. One investor already collects $4,800 a month. Another hasn't worked in years. Show me something better. I'll wait. [Enroll in P.I.P. →]
Can Apple Overtake NVIDIA as the World's Most Valuable Company?
Written by Sam Quirke. Publication Date: 9/22/2026.
Key Points
- Apple's market cap has climbed to about $4.98 trillion, closing in on NVIDIA's roughly $5.50 trillion valuation amid a strong iPhone launch.
- NVIDIA's stock has stalled since May due to investor caution over AI spending sustainability, export risks, and margins, despite still-strong underlying growth.
- NVIDIA's revenue is growing more than 80% annually versus Apple's 14%, suggesting any Apple overtake in market cap could prove short-lived.
- Special Report: Everyone wanted SpaceX. Smart money wants this.
For most of the past two years, NVIDIA Corporation (NASDAQ: NVDA) has stood at the summit of the stock market. As the chipmaker whose processors power much of the artificial intelligence boom, it was perhaps no surprise that it became the first company ever to reach a $5 trillion market cap. After hitting that record in October 2025, it has spent much of 2026 comfortably above the mark.
Yet its perch has not gone unchallenged. In July of this past summer, Apple Inc. (NASDAQ: AAPL) briefly leapfrogged NVIDIA, closing in on the $5 trillion milestone before NVIDIA reclaimed the top spot. Now, the iPhone maker is closing the gap once more. Apple's shares are up about 6% since the first week of September, putting its market cap at roughly $4.98 trillion. NVIDIA, meanwhile, is down about 1.6% over the same period and has stalled at around $5.50 trillion.
Rickards Predicts: Trump to buy tiny $2 stock? (Ad)
Jim Rickards believes the Trump administration is about to take a direct stake in a $2 stock sitting on the largest mineral reserve in the country - enough gold for a new Fort Knox, enough copper to rebuild the U.S. electric grid 25 times over.
The Trump administration has previously staked positions in MP Materials, Lithium America, Trilogy Metals, and USA Rare Earth - each time shares moved higher. A landmark policy decision expected before November 3 could reprice this stock from $2 to $20 or more within a year.
Click here to see why Rickards believes this stock is nextFor companies this large, that is close enough to make another overtaking a real possibility in the coming weeks. The question is no longer whether Apple can catch NVIDIA, but whether it can stay ahead once it does.
How the Race Has Tightened
The shift in momentum has been steady rather than sudden, with Apple outpacing NVIDIA for much of the past 12 months. Since this time last year, for example, Apple's shares have climbed around 32%, comfortably outpacing NVIDIA's 24%. Since early August, Apple has rallied roughly 11%, while NVIDIA has gained barely 1%.
Recently, Apple's uptrend has been driven by a clear catalyst. Its Sept. 9 product launch, headlined by a new lineup of premium iPhones and its first-ever foldable model, generated both pre-release hype and encouraging post-release results. Early demand signals have been positive, and analysts have continued to warm to the story. Some, including TD Cowen, have already raised their price target to $400 this month.
NVIDIA's plateau, by contrast, seems to be less about its business faltering than about investor nerves. Its growth remains phenomenal, but investors have grown more cautious about how long the frenzied AI-infrastructure spending can last. They are also weighing risks ranging from thinning margins to Chinese export restrictions. As a result, the stock hasn’t hit a fresh all-time high since May.
What Would Get Apple Over the Line
To match NVIDIA's current market cap, Apple's shares would need to rise only around 11%, a move they have already made once since early August. Given how the two stocks have diverged lately, a continued Apple rally paired with more of NVIDIA's recent drift could close the gap within weeks.
The most likely fuel would be further evidence that the new iPhones are flying off the shelves. If demand for the latest premium models proves as strong as early indicators suggest, and the foldable carves out a lucrative new niche, the rally could have enough momentum to continue. Investors won't have to wait long for a read on that, with Apple's next earnings report due at the end of October. It should reveal whether the early enthusiasm is showing up in the numbers.
Why It's Far From a Done Deal
Yet for all Apple's momentum, the underlying numbers still favor the incumbent, and this is the crucial caveat. NVIDIA may have posted smaller share-price gains lately, but its business is growing at a blistering pace, with revenue expanding more than 80% over the past year versus Apple's far more modest 14% growth.
That difference matters enormously, and it explains why NVIDIA commands the larger valuation in the first place: Investors are willing to pay for much faster growth. For Apple to not just catch NVIDIA but stay ahead, it would need to sustain its rally while its rival continues expanding several times faster—a difficult task.
Apple's own path carries risks, too. The foldable market remains small, and its aggressive pricing could deter some buyers. If the iPhone cycle disappoints or enthusiasm fades, the recent surge could stall as quickly as it began.
Does the Top Spot Even Matter?
So, is Apple about to reclaim the top spot? Based on current trends, it is tantalizingly close. If its rally holds while NVIDIA continues to drift, the overtaking could happen in the weeks ahead. For now, momentum is firmly with the iPhone maker.
However, investors should be wary of reading too much into a market-cap milestone. Being the world's most valuable company is a headline, not a verdict on which stock is the better buy. NVIDIA's faster growth means that any lead Apple seizes could prove short-lived.
For now, the race is remarkably close, and a symbolic changing of the guard may be near. Whether it proves lasting, though, will come down to the far less glamorous business of who can keep growing. Apple has the momentum, NVIDIA has the numbers, and the coming weeks will show which matters more.
SoFi Is Bypassing the Banking Bottleneck With Stablecoin Settlement
Written by Jeffrey Neal Johnson. Publication Date: 9/26/2026.
Key Points
- SoFi Technologies is migrating its roughly $25 billion annualized card program to stablecoin settlement using SoFiUSD across Mastercard's network.
- SoFi Bank's national charter gives the company regulated banking infrastructure that several fintech competitors are still working to bring in-house.
- The stablecoin rollout could eventually lower settlement friction and expand SoFi's fee-based financial infrastructure business beyond traditional lending.
- Special Report: Everyone wanted SpaceX. Smart money wants this.
Legacy payment infrastructure acts as a tollbooth on commercial capital. Every swipe, transfer and settlement involves multiple intermediaries that extract fees and tie up liquidity in correspondent accounts. That friction creates an operational drag for businesses managing high-volume treasury flows. A structural shift is underway as modern digital rails integrate with traditional banking frameworks to streamline these processes.
SoFi Technologies, Inc. (NASDAQ: SOFI) is bridging regulated commercial banking and real-time digital asset settlement by migrating its card program to a stablecoin-powered network. Operating under an Office of the Comptroller of the Currency national bank charter, SoFi Technologies is deploying SoFiUSD to bypass traditional clearinghouses.
The REAL Reason Trump is Invading Iran (Ad)
For a moment…
Forget about Trump’s ties to Israel.
Forget about reports of Iran’s nuclear program.
Because my research has led me to believe we’re risking World War 3 with Iran for a completely different reason.
Click here to find out what it is.By eliminating these intermediaries, SoFi aims to reduce payment-processing costs and capture commercial deposits from legacy financial institutions. A review of this infrastructure upgrade reveals its broader impact on the competitive landscape and SoFi's valuation.
Ditching the Clearinghouse for Blockchain
Migrating a national bank's debit and credit card program to blockchain-based settlement marks a maturation of financial technology. SoFi Bank is migrating approximately $25 billion in annualized transaction volume across Mastercard's (NYSE: MA) global payments network to settlement using SoFiUSD. The digital asset is a stablecoin backed one-to-one by cash reserves and operates entirely in the background as a settlement layer.
Traditional correspondent banking relies on batch processing, domestic clearinghouses and limited operating hours, all of which can delay access to capital. By shifting to an on-chain ledger, merchants using SoFi's commercial banking platform can receive instant, around-the-clock settlement without additional costs. Business owners do not have to hold cryptocurrency directly, manage digital wallets or upgrade their point-of-sale hardware. The tokenized settlement architecture removes institutional friction, providing merchants with immediate access to dollars for payroll, inventory and operational expansion.
This value proposition could serve as a structural magnet for commercial treasury accounts. When a bank can offer instant liquidity without traditional interchange and processing delays, it creates a compelling incentive for high-volume merchants to move deposits away from incumbent regional banks. SoFi is positioning itself as a primary destination for modern corporate capital.
The OCC Charter: A Built-In Regulatory Moat
The broader financial technology sector is scrambling for the regulatory legitimacy needed to replicate this model. Operating an on-chain settlement network inside a chartered national bank may eliminate regulatory hurdles that are currently slowing nonbank stablecoin issuers and payment processors.
Competitors are spending capital to close this gap. Chime Financial (NASDAQ: CHYM) recently agreed to acquire Stride Bank for around $590 million in cash, a move specifically designed to secure a national charter, protect interchange revenue and reduce partner-bank fees. Similarly, Block, Inc. (NYSE: XYZ) filed with the Office of the Comptroller of the Currency to form a national trust charter to unify compliance across its Cash App and Square ecosystems.
Because SoFi already holds an active national bank charter, it enjoys a potential multi-year competitive advantage. SoFi can deploy its stablecoin infrastructure in a compliant manner, capturing market share while peers navigate lengthy acquisition and regulatory approval processes. Building this infrastructure in-house rather than renting a bank charter also allows SoFi to retain more of the economics from each transaction it clears.
Core Lending Provides the Capital Foundation
Transitioning to a modernized settlement network requires capital, and SoFi Technologies' core lending operations are providing that foundation. The most recent second-quarter 2026 earnings report demonstrated sustained fundamental execution, with SoFi posting earnings per share of about 12 cents and beating consensus estimates by 1 cent. Revenue expanded about 42.5% year over year, indicating steady top-line momentum amid shifting macroeconomic conditions.
Consumer lending stocks have faced recent macroeconomic headwinds, with peers such as Upstart Holdings, Inc. (NASDAQ: UPST) and Affirm Holdings, Inc. (NASDAQ: AFRM) also experiencing selling pressure as investors grow cautious about pure-lending exposure. SoFi has maintained stable credit quality, reporting improving delinquencies alongside steady loan originations.
This core lending profitability funds the expansion into fee-based, scalable infrastructure. Current net margins stand at around 14.78%, with a return on equity of about 6.22%. By routing billions of dollars in volume through a proprietary stablecoin network instead of third-party clearinghouses, SoFi could lower its unit operating costs. As these transaction savings scale, they could provide a clear structural pathway to margin expansion and higher return on equity in the coming fiscal years.
Looking Past the Retail Noise
Despite the long-term operational advantages of the Mastercard integration, SoFi's stock price has experienced near-term pricing inefficiencies. SoFi Technologies shares declined about 9% over the past month, trading near $16.50. Some of this downward pressure stemmed from retail investor caution surrounding recent executive stock sales.
Chief Technology Officer Jeremy Rishel and Executive Vice President Kelli Keough sold blocks of shares worth about $325,000 and $173,000, respectively. These transactions were executed under prearranged Rule 10b5-1 trading plans. Planned sales are standard components of executive compensation management and do not necessarily indicate a lack of confidence in the business's trajectory. Both executives retained substantial equity positions following the transactions.
Institutional investors appear to be looking past this short-term noise. Major asset managers maintain a firm grip on the float, with BlackRock Inc. holding an approximate 5.65% stake and Bank of America Corp. maintaining a position of about 0.71%. This institutional support may provide stability against sector-wide pullbacks and reflects confidence in SoFi Technologies' transition from a consumer lender to a comprehensive financial infrastructure provider.
A Strategic Entry Into Modern Banking
The current valuation suggests the broader market has not fully priced in the potential operational efficiencies of the new settlement network. Trading at a trailing price-to-earnings ratio of about 34.48 and a forward price-to-earnings ratio of around 27.13, SoFi is still largely valued as a traditional consumer finance operation rather than as a scalable technology platform.
The integration of SoFiUSD represents a capital-efficient transformation that diversifies revenue away from pure interest income and toward transaction-based services. As correspondent-banking friction is reduced, the resulting cost savings could begin to appear on the balance sheet.
Investors with a multiyear time horizon may want to add SoFi to their watchlist as earnings momentum builds around this infrastructure deployment. Those monitoring the stock may prefer to look for accumulation opportunities before lower payment-processing costs are fully reflected in quarterly margins. Investors should continue to monitor upcoming earnings reports for specific data on transaction volumes and incremental profit growth from the stablecoin integration.
This email content is a sponsored email sent on behalf of Freedom Financial, a third-party advertiser of MarketBeat. Why was I sent this email message?.
If you need assistance with your subscription, feel free to email MarketBeat's South Dakota based support team at contact@marketbeat.com.
If you would no longer like to receive promotional emails from MarketBeat advertisers, you can unsubscribe or manage your mailing preferences here.
Copyright 2006-2026 MarketBeat Media, LLC. All rights protected.
345 North Reid Place #620, Sioux Falls, S.D. 57103. United States of America..



No comments:
Post a Comment