Keep an eye on Carnival Corp. (NYSE: CCL). The company is preparing to report its fiscal third-quarter earnings on Thursday, September 17 and expectations are running high.
Table of Contents
That’s because the third quarter includes the busy summer vacation season, making it one of the cruise line’s most important reporting periods of the year. Investors will be looking for strong revenue, healthy onboard spending, and evidence that cruise demand remains resilient despite elevated fuel costs and geopolitical uncertainty.
According to estimates, Wall Street expects Carnival to report third-quarter revenue of about $8.40 billion, up from $8.15 billion during the same quarter last year. Analysts also expect adjusted earnings of about $1.35 per share, compared with $1.43.
At first glance, those numbers send a mixed message. Revenue is expected to increase by roughly 3%, suggesting passengers are still booking cruises and spending money onboard. However, earnings are expected to decline modestly, largely because higher fuel costs and other expenses are pressuring Carnival’s margins. That means this earnings report will be about much more than whether Carnival beats the headline estimates.
President Trump recently said AI will not be stopped by brilliantly run destructive forces. And that it will be the greatest economic development engine in history. All while the GOP tries to curb concerns about AI ahead of the midterm elections.
This divide is one reason why Whitney Tilson believes that in less than 100 days, an 'AI Civil War' will begin in America. And it will have huge implications on your portfolio.
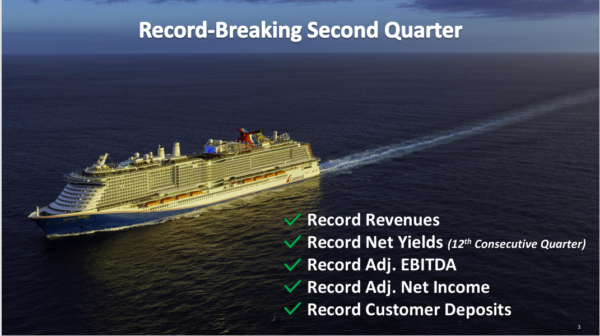
The most important part of Carnival’s report may be what management says about future demand. During the second quarter, Carnival reported record revenue of $6.7 billion and adjusted earnings of 41 cents per share. That was comfortably ahead of Wall Street’s earnings estimate of 35 cents.
The company also reported a record $9 billion in customer deposits. Its booked position for the second half of 2026 was ahead of the previous year and secured at historically high prices. Even better, Carnival said demand for cruises in 2027 and beyond was continuing to exceed year-ago levels. Those are encouraging signs.
Customer deposits give investors a valuable glimpse into future demand. When deposits are rising, it generally means passengers are booking more trips or paying higher prices to secure them. Either way, it suggests consumers still view cruises as an attractive vacation option.
Wall Street will want to know whether that momentum continued throughout the summer.
Investors should pay especially close attention to Carnival’s comments about booking volumes, ticket prices, occupancy, and the amount passengers are spending on food, drinks, casinos, excursions, Internet packages, and other onboard services.
Strong onboard spending could help Carnival offset some of the pressure coming from higher operating costs.
Fuel Costs Could Be Carnival’s Biggest Headwind
Fuel remains one of the biggest risks facing the company. That’s because, unlike some of its competitors, Carnival typically does not hedge its fuel exposure.
That leaves it more vulnerable when oil and marine fuel prices rise quickly. In its second-quarter report, the company said fuel costs had risen nearly 30% from the prior year. Management estimated that fuel and currency reduced quarterly earnings by approximately six cents per share.
For the third quarter, Carnival projected fuel expenses of approximately $620 million, based on an estimated fuel cost of $812 per metric ton. That helps explain why earnings are expected to decline even though revenue should reach another record.
The encouraging part is that the company has been working aggressively to improve efficiency. Fuel consumption per available passenger berth fell 5.6% during the second quarter, helping soften the impact of higher prices.
Wall Street will be watching to see whether those efficiency gains continued in the third quarter and whether management now expects fuel costs to become more or less of a problem during the remainder of 2026.
Carnival previously projected third-quarter adjusted earnings of approximately $1.35 per share. At the time, that was below the $1.42 Wall Street had expected, and the softer forecast contributed to a sharp drop in the shares.
Expectations have now adjusted to Carnival’s forecast, creating an opportunity for the company to deliver a positive surprise. Still, the stock’s reaction may depend more heavily on management’s updated outlook than on the third-quarter results themselves.
Investors will be listening for changes to Carnival’s full-year earnings forecast, projected net yields, operating costs, fuel expenses, and 2027 bookings. Progress on debt reduction and additional share repurchases could also influence sentiment.
The bottom line is that Wall Street expects another record revenue quarter from Carnival, but rising costs could keep earnings below last year’s level. A strong report combined with upbeat 2027 commentary could reinforce the bullish argument that Carnival’s recovery still has room to run. However, another cautious outlook—particularly around fuel prices or European demand—could leave investors wanting more.
Daily Options Signals is a subsidiary of StockEarnings, Inc. (SE). SE is a research service and not a registered broker or investment advisor. Please view full disclaimers.
Daily Options Signals33 SE 4th St, Suite 100,Boca Raton, FL 33432 USA




No comments:
Post a Comment