|
The Flaw Your Financial Advisor Will Not Name 
3 More AI Infrastructure Plays Beyond the Big NamesWritten by Nathan Reiff on September 27, 2026 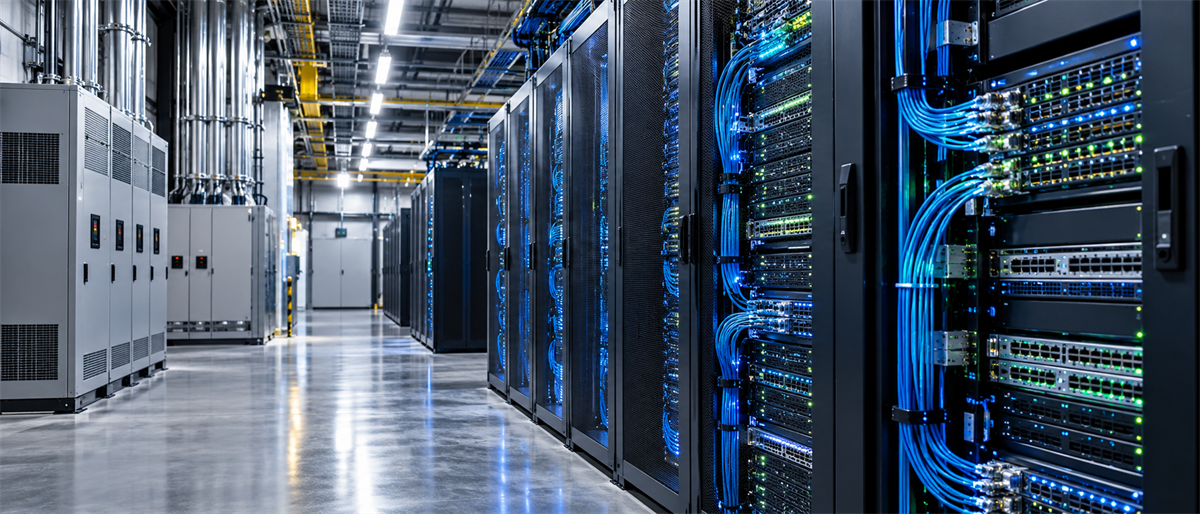
Key Points
- AI infrastructure buildouts continue at a rapid pace despite some tech firms signaling caution about future AI development spending.
- Bloom Energy, Ciena, and Twilio each occupy a distinct niche in power, networking, or AI orchestration and show strong revenue growth and raised guidance.
- All three stocks have risen sharply year to date, with analysts largely bullish but suggesting investors watch for pullbacks before buying.
- Special Report: Congress Has a “Secret Weapon” 1 From 1974

With major tech firms appearing to reverse course by calling for a slowdown in AI development, investors may have reason to think that demand for AI training may shift in the future. For the time being, though, AI infrastructure projects—which tend to have timelines spanning multiple years due to the complexities of securing electrical power, building facilities, and so on—are continuing to proliferate at a breakneck pace, even as AI applications expand into new industries. A host of firms are involved in the broader AI infrastructure space, and investors willing to do some searching can find lesser-known names poised to benefit from strong demand. A key decision is whether to focus on firms providing power, networking capabilities, or other types of orchestration between AI providers and their client base. The companies below each occupy one of these three corners of the market and enjoy strong financial results alongside optimistic guidance and analyst support.
On January 1, 2027, new Pentagon rules tighten sourcing restrictions on critical minerals tied to foreign adversaries. China controls more than 90% of global rare earth processing capacity, while the U.S. imports 100% of its titanium sponge.
SAGA Metals has drilled more than 23,000 meters at its Radar project, with all 92 drill holes intersecting mineralization. A maiden mineral resource estimate is expected in Q4 2026, alongside ongoing drilling at the Wolverine heavy rare earth project. See what's next for SAGA Metals before the deadline hits
Bloom Energy's Fuel Cells Are Increasingly Vital Across the Data Center SpaceTo be sure, Bloom Energy Corp. (NYSE: BE) is not a small company by any means—its market capitalization sits at nearly $83 billion—but compared to some of the major tech firms involved in AI, it may seem tiny. The firm has a unique niche as a provider of solid oxide fuel cell systems that are increasingly critical to energy infrastructure for their usefulness as backup power systems and in distributed generation applications. Bloom is one of the key companies helping data centers ensure that they have enough electrical power to operate reliably. The data center boom has meant skyrocketing revenue, which climbed 166% year over year (YOY) to almost $1.1 billion last quarter, driven by product revenue that more than tripled over the same period. With this in mind, management has recently raised guidance, suggesting about 100% growth at the midpoint compared to this time last year. Bloom is also improving its profitability, suggesting that the top-line gains are sustainable: gross margin for the last quarter climbed 668 basis points YOY to 33.4%. Bloom's products are broadly distributed across all major U.S. hyperscalers, and a major partnership with Oracle Corp. (NYSE: ORCL) means it will stay busy with deployments for the foreseeable future. Shares of BE are up about 225% year to date (YTD) after all of the good news, so investors might watch for signs of a small pullback to find an opportunity to buy. In late September, a setback to an Oracle data center project did just that, providing a window in which investors could buy at a slightly reduced price. Ciena's Reliance on AI Networking Revenue May Continue to Pay OffOptical networking is critical to data center infrastructure because it can enable more efficient data transfer within and between sites. Ciena Corp. (NYSE: CIEN) has built a reputation as a go-to provider of technology for routing, switching, and interconnecting data centers. Revenue for the latest quarter rose by 37% YOY as adjusted earnings per share (EPS) more than tripled, also leading to a sharp increase in full-year guidance. A risk for Ciena investors is that the company is heavily concentrated in its AI networking business, with more than 81% of revenue last quarter attributable to Networking Platforms. Still, with expanding margins and the expectation that the company will benefit from a multi-year bandwidth upgrade cycle in the years to come, combined with new technologies that should boost efficiency for data transfer, it's clear why three-quarters of analysts rate CIEN shares a Buy. These shares have climbed by only about 54% YTD, modest compared to BE, and still have plenty of upside in store according to Wall Street.
The US government still values its gold reserves at 42 dollars an ounce, a price Congress set in 1973. Gold trades above 4000 today, leaving official books showing about 11 billion dollars for holdings worth more than 1 trillion in the real market.
A bill now moving through Congress would require the Treasury to reprice that gold at current market value, while companion legislation could trigger the first audit of US gold holdings in more than 65 years.
More than 60 million Americans qualify to move part of their savings into physical gold, tax-free and penalty-free. Request your free 2026 Gold Guide to see how it works
Twilio's Rapid Growth May Warrant Watching and Waiting for an Opportunity to BuyUnlike the companies above, Twilio Inc. (NYSE: TWLO) isn't a data center hardware maker. Rather, it offers services allowing AI agents to interact with people via voice, messaging, and other channels. It is, therefore, a different type of AI infrastructure company, but nonetheless one that has seen significant success amid the buildout. Revenue growth of 22% YOY for Q2 2026, paired with strong free cash flow of $353 million, prompted management to raise full-year guidance across multiple categories. Crucially, Twilio has demonstrated its capacity to expand revenue within existing customers, as its customer cohort generated about 16% more revenue YOY for the last quarter. The company's unique voice AI tools are especially popular. Shares of TWLO have also appreciated rapidly, climbing by 99% YTD. While analysts remain overwhelmingly positive in their assessments of TWLO shares, Wall Street seems to suggest that the stock may be due for a slight correction, meaning that investors may want to watch it for signs of an opportune moment to buy. Read this article online › Featured Stories
Did you find this article helpful?  
|



No comments:
Post a Comment