Katelyn, Alex, and Michael bring you minute-by-minute action, bold hot takes, and the biggest storylines as they unfold—live in Chicago, right in the heart of race day.
The show goes live on our YouTube channel at 7:00 a.m. CT/8:00 a.m. ET.
You can also follow every step of the 2026 Bank of America Chicago Marathon with our live blog—real-time updates, key moments, and on-the-ground coverage by our team.
The course loops through 29 neighborhoods on Sunday, and with a CTA fare and a runner's pace, a spectator can see the same person six times between the Loop and the finish. These are the spots worth standing at, and when to get there.
Brigid Kosgei and defending champion Hawi Feysa lead a field with 12 women under 2:20, Sharon Lokedi runs her first flat marathon, and Emma Grace Hurley, the American 8K record holder, makes her marathon debut.
Three men in the field have run close enough to Conner Mantz's 2:04:43 to threaten it, and one has already gone faster on a course that does not count. Emily Sisson's 2:18:29 is a bigger ask, though a debutant coming off a 1:06:23 half-marathon believes she is in 2:20 shape.
The defending champion ran 2:00:28 in London in April, and beating Sabastian Sawe's 1:59:30 on Sunday would mean finding another 59 seconds on a morning forecast to start in the low 60s.
The 2026 Chicago Marathon is almost here, and in this bonus episode of The Running Story, Michael Doyle and Jessy Carveth cover everything you need to know before race day.
The AI trade has become so concentrated that it is easy to forget how much money has to be spent before an AI model can answer a single prompt. Nvidia (NASDAQ: NVDA) supplies the GPUs, while other mega-cap technologies are building enormous computing capacity and driving the market higher at the same time.
Table of Contents
But under the hood, the physical AI buildout creates problems software cannot solve. More GPUs mean more heat. More AI infrastructure means more electricity. Thousands of accelerators also need to be integrated, deployed, and managed before they generate anything for a customer…
As of this moment, MOD is worth $9.71 billion, PENG $3.11 billion, and POWL $7.21 billion. Their market caps have climbed 25.4%, 113.9%, and 96.4%, respectively, over the past year.
The more computing power you pack into a data center, the harder thermal management becomes. That gives Modine (MOD) a direct way to participate in the AI buildout without selling a single GPU.
Modine’s latest quarterly results? show how quickly that business is scaling. Q1 fiscal 2027 revenue reached $874.1 million, up 28% year over year, while EPS rose 44%. Data Center revenue was the standout, jumping 90% year over year.
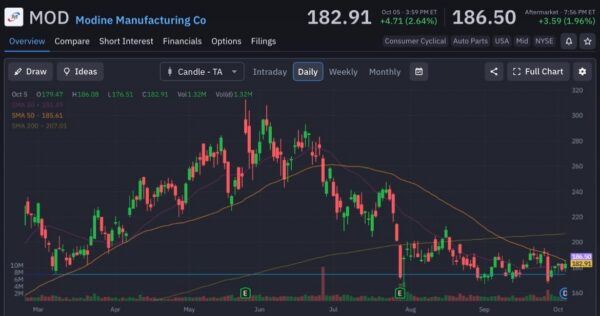
MOD closed at $182.91 on October 5, sitting just above its 20-day SMA at $181.49 but below its 50-day at $185.61 and well below its 200-day at $207.01. After falling from above $300 earlier in the year, the stock found buyers around $170-$175 in September and has started forming a higher-low structure.
A move through $186 would put the 50-day average back underneath the stock, while $200-$207 is the much bigger test. Until then, MOD is recovering from a major drawdown rather than sitting in a confirmed long-term uptrend.
That makes the operating growth particularly important. Modine already shows a business seeing substantial demand from data-center customers, while the cooling problem only becomes more demanding as computing density rises.
PENG Is Moving From Hardware To AI Factories
Penguin Solutions (PENG) sits closer to the point where AI hardware becomes a functioning system.
The company reported record Q3 fiscal 2026 revenue of $478.7 million, up 48% year over year. GAAP operating income jumped 417%, while non-GAAP EPS increased 79%. Management subsequently raised its full-year outlook as demand strengthened across its Integrated Memory and AI Infrastructure businesses.
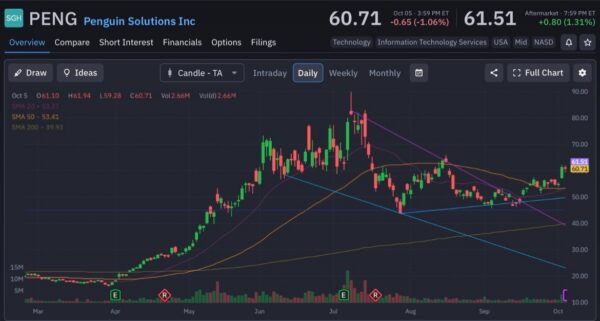
The stock chart is considerably stronger than MOD’s. PENG closed at $60.71, more than $7 above both its 20-day and 50-day SMAs, which sit around $53.37 and $53.41. The 200-day SMA is down at $39.93. More importantly, PENG has broken above the descending trendline that had capped the stock since its July peak near $80.
The next hurdle is around $62, followed by the $70 area. Holding above $53-$54 would preserve the current breakout structure. For me, that combination of accelerating revenue and a technical breakout makes PENG the most aggressive momentum setup of the three.
Powell makes engineered equipment for the management, control, and distribution of electrical energy. Its Q3 fiscal 2026 results showed $934 million of new orders, up 158%, pushing backlog to $2.4 billion, up 69%. Book-to-bill reached 3.0x. In fact, Powell also secured a data-center project worth more than $400 million.
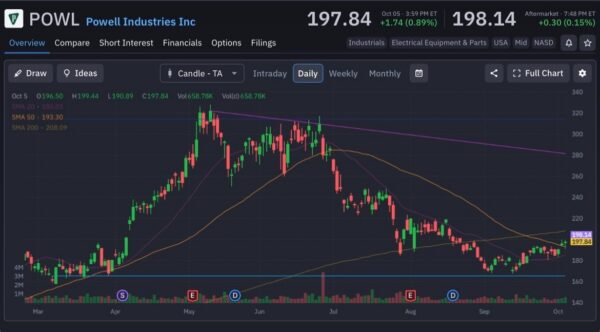
And the chart has now started recovering too. POWL closed at $197.84, above its 20-day SMA at $185.03 and 50-day at $193.30, after bouncing from the $165-$175 area in September. The 200-day SMA sits at $208.09, making $200-$208 the immediate technical ceiling.
A clean break through that zone would put POWL back above its long-term average for the first time since its summer decline. Failure there leaves the stock trapped between roughly $175 support and $208 resistance.
It's rumored to be thinner... have longer battery life... and sell for much cheaper... It could also be usable worldwide without cell towers... and run on one of the most powerful AI-based platforms in existence.
One that could not only change your life and our society... but potentially make you 50 times your money as it hits shelves.
Just last week, the FCC gave Elon a major green light to move ahead with his mobile plans. That means your window to move your money is NOW — before the official debut.
This is where I think the opportunity gets interesting for investors who already own the obvious AI winners.
Nvidia, Microsoft, Amazon, and Alphabet have captured the attention because their products sit at the center of the AI revolution. But just as you’ve seen, MOD, PENG, and POWL sit further down the chain, where the physical constraints of that revolution are becoming increasingly expensive to solve.
None of these companies needs to become the next Nvidia for the thesis to work. They need AI capital spending to keep flowing into data centers, and their recent financial results suggest that spending is already reaching their businesses. Getting exposed to this basket of 3 smaller companies, sitting underneath the same multitrillion-dollar AI spending cycle, each attacking a physical bottleneck the Mag 7 cannot simply wish away…is almost a no-brainer for me.