|
Monday, September 21, 2026
How to nail your progression run


Trump goes "all-in" on Grand Canyon energy breakthrough
| Unsubscribe |
Fellow Investor,
The biggest energy deadline in American history...
Just aimed its full firepower at ONE company.
See, on July 4th, the One Big Beautiful Bill Act killed the federal tax credits that powered alternative energy for years.
But here's what almost nobody knows:
When the White House killed credits for solar, wind, EVs, and every other renewable energy source in America…
They left one untouched.
Not only that - they reclassified it alongside oil and nuclear...
And gave it eight years of credits.
Because in June 2025, a drilling crew working near the Grand Canyon...
Unearthed a well of clean energy producing almost 8 times the output of the largest oil well in Saudi Arabia...
Capable of powering civilization for two million years.
Right here on American soil.
Everything changed that day.
Google signed a 15-year contract...
Bill Gates wrote a $100 million check.
And on July 4th, the government handed this energy source its biggest advantage ever.
One company owns the entire chain.
Time is running out to be an "early investor."
I recommend placing your trade at tomorrow's market open.
Go here now for the Grand Canyon breakthrough ticker >>
"The Buck Stops Here,"
Dylan Jovine, CEO and Founder
Behind the Markets
Enterprise AI to Boost Broadcom's Software Business? What Industry Data Shows
Reported by Leo Miller. Date Posted: 9/17/2026.
Key Points
- Broadcom CEO Hock Tan says AI adoption is becoming a growth driver for its VMware-anchored software business through private cloud deployments.
- Broadcom's infrastructure software revenue grew 29% year-over-year to $8.8 billion, though AI chip sales still dominate at 56% of total revenue.
- Mixed evidence from IDC, Kyndryl, and Hewlett Packard Enterprise offers only partial support for Broadcom's claim of accelerating private cloud AI adoption.
- Special Report: Everyone wanted SpaceX. Smart money wants this.
Broadcom’s (NASDAQ: AVGO) AI semiconductor business continues to be the dominant force behind the company’s growth and the biggest narrative surrounding the stock. However, chips are not the only area of Broadcom’s business where AI is supporting growth.
According to Broadcom CEO Hock Tan, AI adoption is also emerging as a growth driver for the company’s software business, anchored by VMware.
These gold assets are priced for $1,800 gold [it's over $4,000] (Ad)
Gold's major miners are generating record free cash flow, with margins as high as 75 percent even after gold's pullback from highs above 4000 an ounce.
Yet top junior mining assets remain priced as if gold were still stuck near 1800 an ounce, a gap analyst Garrett Goggin calls the Golden Anomaly.
With record cash on hand, majors may soon be forced to buy juniors to secure future production.
See the junior gold assets majors may target nextThis comes as Broadcom expects enterprises to increasingly deploy AI in private cloud environments.
Of course, this is exactly what the management team of a company selling private cloud AI software would say. Testing the veracity of this claim requires examining what industry participants and third-party analysts are seeing.
The State of Broadcom’s Software Business
While Broadcom’s AI chip business consumes nearly all of investors’ attention, software represents a sizable portion of its revenue base. AI chip sales grew 221% year over year (YOY) last quarter to $16.7 billion. Notably, at 56% of total revenue, this marked the first quarter in which AI chips accounted for the majority of Broadcom’s revenue. In the prior quarter, AI chips accounted for 49% of total sales.
Meanwhile, infrastructure software revenue grew 29% YOY to $8.8 billion, accounting for 30% of total sales. While this is clearly lower than the growth of AI chips, it is still a strong increase for a large software business. For next quarter, Broadcom expects software revenue of $8.7 billion. This would represent a sequential decline but still a strong 28% YOY increase. Based on Broadcom’s guidance, software’s share of total revenue would fall to a still-significant 25%, while AI chips’ share would rise to 62%.
Tan Calls Out Private Cloud AI Opportunity
Looking ahead, Hock Tan said, “Enterprise consumption of AI is, in fact, opening a new opportunity for our infrastructure software business.” This view is largely based on Broadcom’s expectation that enterprises are working to deploy more AI workloads in private clouds.
Private clouds describe environments in which a single company exclusively uses the computing resources. This contrasts with public clouds, where multiple users share the same resources. Private cloud deployments offer greater data security and customization, as well as more consistent performance and better cost control. Broadcom’s products, such as VMware Private AI Cloud, can allow enterprises to deploy AI in private environments and repatriate workloads from public clouds.
Broadcom notes that in 2026, 56% of enterprises are running or planning to run production AI inferencing on private clouds. Meanwhile, the percentage of enterprises running or planning to run the same workloads on public clouds fell from 56% in 2025 to 41% in 2026. Broadcom also says that 83% of organizations are considering repatriating workloads from public clouds to private clouds. While private cloud deployments offer greater security and control, Broadcom says they improve total cost of ownership by three times compared with native public clouds.
What Other Sources Are Saying
Other evidence indicates that the shift toward private clouds may be less pronounced than Broadcom suggests. Notably, in a 2025 survey conducted by IDC, the firm found that “organizations were deploying AI applications equally in both private and public clouds, at 49.9% and 50.1% respectively.”
Additionally, 63.6% of respondents expected more workloads to shift to the public cloud rather than the private cloud, directly contradicting Broadcom’s view. Analyst Mathew Flug does not see a massive repatriation to private clouds. Rather, he expects the overall number of workloads to increase, indicating that the markets for both private and public clouds are growing.
Commentary from cloud services company Kyndryl (NYSE: KD) aligns with this view, with the firm seeing accelerating demand “in both public and private cloud." However, the company also offered commentary that lends credence to Broadcom’s view. At the Citi 2026 Global TMT Conference, Kyndryl noted, “We are seeing now a bit of a resurgence in private cloud where five years ago, six years ago, seven years ago, private cloud had started to not shrink, but public cloud was more important in certain ways. Private cloud is kind of coming back now.”
Further supporting Broadcom’s view, Hewlett Packard Enterprise (NYSE: HPE) notes that orders for its private cloud AI (PCAI) business increased by triple digits last quarter.
What to Watch: HPE’s Private Cloud AI a Key Indicator
This evidence points to a more mixed view of the private cloud outlook. IDC’s commentary is least supportive of Broadcom’s view, although it still points to rising private cloud demand. Kyndryl’s commentary falls somewhere in the middle, with the firm noting that private cloud is seeing a resurgence. Meanwhile, HPE is seeing very strong demand for its PCAI offering. This provides significant support for Broadcom’s view that AI is increasing private cloud adoption.
Going forward, accelerating growth in Broadcom’s software business will be the best indicator of whether the company is capturing this opportunity. Paying attention to commentary from forecasters such as IDC and market participants such as Kyndryl can help investors understand where the market is heading. Commentary from these groups that becomes increasingly favorable toward private cloud would support Broadcom’s outlook.
However, tracking how HPE’s PCAI order growth evolves would likely be the best indicator, aside from Broadcom’s own results. This gives investors a metric that specifically measures AI-driven private cloud adoption, providing a way to gut-check Broadcom’s thesis.
3 Defense Stocks Riding the High-Energy Laser Boom
Reported by Nathan Reiff. Date Posted: 9/15/2026.
Key Points
- AeroVironment secured a $465 million U.S. Army laser weapon contract and a $50 million international LOCUST order, alongside record quarterly revenue of $480.5 million.
- Kratos Defense participates in high-energy laser systems through its HELEX products and Navy history, but its laser revenue remains bundled within broader weapon systems reporting.
- Red Cat Holdings lacks a direct laser program but supplies reconnaissance drones supporting laser deployments, and its stock has fallen only about 1% year to date.
- Special Report: Everyone wanted SpaceX. Smart money wants this.
A science-fiction future is becoming increasingly possible in the present, thanks to rapid advancements in high-energy lasers for military and defense applications. Major gains in fiber laser technology, tracking, optics and thermal management are making these tools a reality as potential counter-drone measures, with additional applications on the way.
In September 2026, the U.S. Army signaled just how important this technology may become by awarding a major production contract for a high-energy laser weapon system to AeroVironment Inc. (NASDAQ: AVAV). That's a significant boon for AVAV stock and a boost for the company as it continues to expand beyond its drone technology foundation.
CODE RED: AI Meltdown Imminent? (Ad)
After correctly predicting the 2008 and 2020 stock market meltdowns, I believe this AI company is about to trigger the next crash. The research firm Bernstein Research said this AI company has the power to crash the global economy for a decade, the CEO just issued a CODE RED in an internal memo warning employees they're dealing with a critical situation, and another company executive even implied they might need a government bailout. The last time I saw something like this was in 2008 when I predicted a stock market meltdown just three weeks before Lehman went under.
See the five simple steps to prepare before it's too lateCombined with a strong earnings report in the same month, AeroVironment appears positioned for a major recovery, even as the stock remains down 36% year to date (YTD).
Beyond this one company, a new technological opportunity is emerging for laser manufacturers, with several firms already establishing important footholds.
The Path Forward for AVAV After Laser Contract
Despite its poor stock performance this year, AeroVironment offers several appealing qualities for investors. The $465 million contract from the U.S. Army is one of two significant updates related to the company's high-energy laser program. The company also recently received its first international purchase order for the LOCUST Laser Weapon System, valued at more than $50 million. This suggests that AeroVironment is not only a domestic leader in this emerging field but also a key international player.
The company's latest quarter brought record revenue of $480.5 million, up about 6% year over year (YOY), along with a sizable earnings beat relative to expectations. Perhaps even more impressively, AeroVironment's funded backlog climbed 37% YOY to $1.5 billion.
With a stable balance sheet and growing momentum in its laser technologies, the company appears to have justified its optimistic ratings. Twenty Wall Street firms have rated AVAV a Buy, compared with just four that see reason to hesitate and have assigned Sell or Hold ratings. The question is what might catalyze a reversal in the company's share price. With analysts projecting nearly 36% earnings growth in the coming year, investors may be anticipating an upswing.
Kratos May Be a Closer Competitor Than Its Financials Let On
Investors might view Kratos Defense & Security Solutions Inc. (NASDAQ: KTOS) as a potential rival to AeroVironment in the laser space. While Kratos has genuine credentials in the field, its laser work is not yet visible as a distinct revenue driver.
The company provides a coherently combined laser system through its HELEX products, along with a variety of other system-integration and subsystem-support tools. Its participation in the U.S. Navy's previous Laser Weapon System program also speaks to its expertise in this emerging technology.
For now, Kratos reports high-energy laser activity within the broader weapon systems category, making it difficult for investors to determine how much of the company's recent 30.5% YOY revenue growth in Q2 2026 may have been driven by its laser business.
Still, as Kratos diversifies its offerings and the military relies more heavily on low-cost, rapidly engaging laser tools, the company could be close behind AeroVironment.
KTOS shares have followed a similar downward trajectory this year, falling 37% YTD, but they also share AVAV's broad analyst support.
Red Cat Benefits From Adjacency
Unlike the companies above, Red Cat Holdings (NASDAQ: RCAT) does not have a directed-energy weapons program. Instead, this drone reconnaissance and counter-drone technology company offers supplemental systems that are being deployed alongside laser programs in U.S. military settings. Red Cat is a play for investors who anticipate that AeroVironment's success in the high-energy laser space will have repercussions for other companies in the industry, including those not directly involved in the technology.
Specifically, Red Cat's reconnaissance drones may be able to provide target acquisition, battle-damage assessment and other critical support that could make the difference between laser weapons being effectively operational and merely theoretically capable.
Investors may also be drawn to Red Cat because of its performance relative to the other stocks discussed above. RCAT shares are down only about 1% this year, a substantially smaller YTD decline than either of the other two companies. Like both of those firms, however, Red Cat is an analyst favorite: Seven of nine Wall Street firms call it a Buy, and it has significant upside potential, with a consensus price target of $18, or about 130% above its current price.
This email content is a paid advertisement provided by Behind the Markets, a third-party advertiser of MarketBeat. Why was I sent this email content?.
If you have questions about your account, feel free to email MarketBeat's South Dakota based support team at contact@marketbeat.com.
If you would no longer like to receive promotional emails from MarketBeat advertisers, you can unsubscribe or manage your mailing preferences here.
© 2006-2026 MarketBeat Media, LLC.
345 North Reid Place, Suite 620, Sioux Falls, SD 57103. USA..
Sunday, September 20, 2026
Seven gold miners. One pattern. [look what happened to each]
| Unsubscribe |
Look at what's happened to these seven gold miners:
MAG Silver — up 56.6%
Reunion Gold — up 71.9%
Calibre Mining — up 107.7%
Probe Gold — up 166.7%
Rupert Resources — up 177.9%
Loncor Gold — up 181.8%
G2 Goldfields — up 1,228.6%
These weren't lucky picks or lottery tickets. Every one of them moved for the same reason — and it's a reason you can see coming.
Go here to see the pattern behind all seven.
Each of these was a small gold miner sitting on assets a major wanted. And one by one, the majors came and bought them.
Now here's the part that matters: all seven were in my portfolio before the buyouts happened.
Not seven picks out of hundreds. Seven names, all held ahead of the acquisition — because the same signal flagged every one of them. Once you understand what the majors are forced to do, spotting the next target stops being luck and starts being pattern recognition.
Here's why that pattern isn't slowing down — it's accelerating.
The major gold miners have a problem. Their own production is shrinking. Every ounce Barrick or Newmont pulls out of the ground makes their remaining mine worth a little less — a gold mine is a shrinking asset in slow motion.
At the same time, the majors are sitting on the most cash they've ever held, thanks to today's gold prices.
So a major has exactly two options: watch its output shrink until it's out of business… or use that record cash to buy the best small miners and replace what it's losing.
That's not a choice. It's survival. Which means the buyouts don't stop — they keep coming, one after another, until the best small assets are gone.
And here's what that looks like from the outside, if you own one of those small miners before the major comes knocking:
You go to bed owning a small gold company.
Overnight, a major announces it's buying that company — at a premium.
You wake up, and your shares are worth 40%… 67%… even 79% more than when you closed your laptop the night before. No chart to watch. No trade to time. The value reprices instantly, while you sleep.
That's already happened to all seven companies above — every one of them in my portfolio before it did. The only question left is which small miners are next — the ones with the grade, the cash flow, and the assets the big players actually need.
My name is Garrett Goggin, CFA, CMT. My readers had the chance to hold all seven of those names before the majors bought them — and it's why Porter Stansberry recently called me:
"THE most knowledgeable gold investor in the world."
Go here to see the three names I believe are next in line to get bought.
Best,
Garrett Goggin, CFA, CMT
Lead Analyst and Founder, Golden Portfolio
Oracle’s AI Spending Is Still Huge, But the Payoff Is Starting to Show in Earnings
Submitted by Thomas Hughes. Article Posted: 9/11/2026.
Key Points
- Oracle’s fiscal first-quarter revenue rose 30% as cloud infrastructure revenue surged 121% and remaining performance obligations reached $664 billion.
- Oracle generated a record $23 billion in operating cash flow, but free cash flow remained negative as data center spending stayed elevated.
- Oracle’s improving earnings leverage and swelling backlog support the AI monetization thesis, although debt, dilution, and capital spending remain important risks.
- Special Report: Everyone wanted SpaceX. Smart money wants this.
Oracle’s (NYSE: ORCL) stock price is on track for a substantial recovery and a sustained upswing as the monetization of its AI ambitions begins.
Highlights from the first-quarter fiscal 2027 (Q1 FY2027) release reveal the effects of spending, capital raises and dilution, which were overshadowed by improved earnings leverage and cash flow. The likely outcome is that monetization of its AI network will accelerate in the coming quarters, while capital expenditures (CapEx) could begin to taper over time.
These gold assets are priced for $1,800 gold [it's over $4,000] (Ad)
Gold's major miners are generating record free cash flow, with margins as high as 75 percent even after gold's pullback from highs above 4000 an ounce.
Yet top junior mining assets remain priced as if gold were still stuck near 1800 an ounce, a gap analyst Garrett Goggin calls the Golden Anomaly.
With record cash on hand, majors may soon be forced to buy juniors to secure future production.
See the junior gold assets majors may target nextThe result could be rapid profitability improvement, high-level growth, accelerated earnings and, eventually, debt reduction—a quartet of bullish stock price catalysts.
Migration to Oracle’s Cloud Accelerates in Q1
Oracle’s results were robust across metrics, driving sequential and year-over-year revenue growth acceleration to 30%. Revenue of $19.35 billion exceeded MarketBeat’s consensus by more than 100 basis points (bps), underpinned by strength in the Cloud and 850 megawatts of new GPU capacity. Total Cloud revenue grew 62%, with infrastructure up 121% and software-as-a-service (SaaS) up 10%. By segment, Services grew 5% and Hardware grew 15%, while Legacy Software, now less than 30% of the business, contracted 3%.
The real news is in the margins and cash flow. After two years of accelerating spending, negative free cash flow, increasing debt and shareholder dilution, the company is showing traction with its strategy. Backlog conversion contributed to significant improvement in operating and net income, both on a GAAP and adjusted basis, with both outpacing top-line growth. Key takeaways include a record $23 billion in operating cash flow, 55% growth in GAAP earnings per share, 30% growth in adjusted earnings and a sizable earnings beat versus consensus.
The only downside is that free cash flow remains negative because of intense data center demand. Oracle reported negative free cash flow of $5 billion in Q1 FY2027. The offset is that its backlog continues to swell, growing about 46% year over year (YOY) in the first quarter to $664 billion. More importantly, the company says the new orders will not translate into increased capital needs, meaning the revenue and earnings outlook has improved without requiring an increase to its existing capital-raising plan. Oracle said more than $30 billion in new AI cloud contracts booked during Q1 had no incremental impact on its capital-raising plans. Guidance reflects this improvement, with management citing a strong Q2, raising its full-year targets and forecasting continued acceleration.
Analysts Highlight Oracle’s AI-Driven Inflection Point: Accelerating Growth Ahead
Analysts’ responses are mixed, including at least one price-target reduction, but that view appears to be an outlier, given that most revisions are bullish. Commentary focused on the massive beats and guidance, which indicate that AI monetization is not only on track but progressing ahead of schedule. Barclays reiterated a Buy rating, expecting earnings growth to accelerate in the coming quarters.
As it stands, the 40 analysts MarketBeat tracks show high conviction in the Moderate Buy rating. The data reflects a 75% Buy-side bias, and the consensus price target, which was validated by post-release responses, implies nearly 65% upside from early September trading levels. In this scenario, analysts’ sentiment is firming and likely to continue strengthening as the year progresses.
Oracle’s Stock Price Inflection Is Here
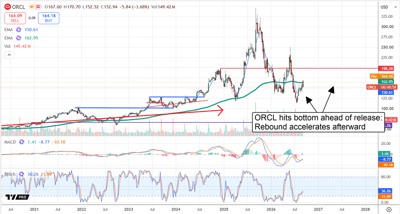
Stock price action is favorable. The late-2025 and early-2026 pullback was overdone, disconnected from the opportunity, and a reversal is now underway. The bottom is near $130, which is now the critical support level, and indicators such as the stochastic and MACD align with Buy signals across multiple time frames. The hurdle is the long-term 150-week EMA near $135, which marks an inflection point for traders and reflects the stance of institutional and long-term investors. A move above that level would signal a shift in sentiment, clearing the way for a fuller price recovery.
Institutions will make the difference because Oracle is a tightly held stock. The group owns more than 40%, a seemingly small number until considering that insiders also own more than 40%. The risk is that selling, which dominated their activity in calendar Q2, will pick up again as the price rises, but that is less likely if profitability continues to improve. Early Q3 activity reflects a surge in buying, which is the more likely outcome. With this in play, institutional buying could help limit downside if price weakness returns.
Oracle’s biggest risks are debt and dilution, but those risks are becoming easier to absorb as growth accelerates. The surging backlog and monetization reduce the threat, leaving investors to wonder when share buybacks will resume. While buybacks are unlikely in 2027, 2028 is a possible target, as most of the planned capacity will be online or nearly there. The dividend helps make up the difference, yielding about 1.3% at current prices near $150, and the distribution is expected to increase over time. Oracle does not raise its dividend annually but has a record of increasing it every few years.
2 Stocks Breaking Out Post-FOMC With One Thing in Common
Submitted by Ryan Hasson. Article Posted: 9/18/2026.
Key Points
- The AI trade is attempting to regain its footing after a volatile stretch, with strength beginning to broaden beyond NVIDIA.
- A strong post-Fed rebound in semiconductor stocks could offer an early signal that investors are rotating back toward AI infrastructure and chip names.
- Advanced Micro Devices and Intel have emerged near the front of that move, but both now face the question of whether momentum can extend after major 2026 rallies.
- Special Report: Everyone wanted SpaceX. Smart money wants this.
The Federal Reserve delivered its interest rate decision on Wednesday, Sept. 16, and the market's response in the following session was telling. As stocks pushed higher on Thursday, Sept. 17, seemingly confirming a post-FOMC bear trap, two AI-related names in particular broke out with real force. They also share a common thread that goes beyond the chart. Both Advanced Micro Devices (NASDAQ: AMD) and Intel (NASDAQ: INTC) are central players in the AI trade—the same trade that wobbled in recent weeks amid fresh fears of an AI slowdown. However, these two stocks now look like early leaders as that narrative and the broader technology sector work to regain their footing.
After a stretch of doubt that knocked the wind out of AI-linked names, capital appears to be flowing back in. And it is not simply piling back into NVIDIA (NASDAQ: NVDA). The fact that AMD and Intel have so far led the charge on heavy volume suggests the AI trade may be broadening as it recovers, with investors starting to reward names beyond the obvious winners.
AMD: Momentum Builds Behind the No. 2 AI Chip Story
The REAL Reason Trump is Invading Iran (Ad)
For a moment…
Forget about Trump’s ties to Israel.
Forget about reports of Iran’s nuclear program.
Because my research has led me to believe we’re risking World War 3 with Iran for a completely different reason.
Click here to find out what it is.Advanced Micro Devices jumped more than 6% on Thursday to close at $545.09, leading the broader chip sector higher and climbing back toward its 52-week high. It has been a spectacular year for the stock, which is now up more than 154% in 2026, as the market increasingly treats AMD as the most credible challenger to NVIDIA in AI accelerators.
The bull case rests on the company's Instinct line of AI chips, which continues to win data-center business, as well as projected earnings growth of a remarkable 111% in the year ahead. That trajectory is why investors have been willing to pay up. AMD currently appears on MarketBeat's most-upgraded stocks list, reflecting a steady run of positive analyst revisions.
Overall, the stock holds a consensus Moderate Buy rating across 47 analysts. The main drawback is that, after such an enormous rally, the stock now trades close to its average price target of $565.13, leaving only modest upside based on the Street's current numbers. But price action is king, and AMD is a momentum and growth story right now. Thursday's move suggests that momentum remains firmly intact.
Intel: A Long-Doubted Turnaround Gains Momentum
Intel Corporation was the bigger mover of the two, surging nearly 8% on Thursday to $108.80. Its run this year has been even more dramatic, with the stock up almost 195%. That is a stunning reversal for a company many investors had written off in prior years, and it reflects how much sentiment around its long-troubled turnaround has shifted.
The recent catalysts have been stacking up for the company, too. INTC reportedly raised enterprise CPU prices by 10% amid tight server-chip supply, confirmed a major manufacturing milestone with ASML (NASDAQ: ASML) involving next-generation High-NA EUV technology, and received a fresh analyst upgrade this week. Notably, insiders have been buying shares, a vote of confidence that stands out against the selling common among many peers.
That said, investors should keep the risks of chasing the stock in full view. The stock's consensus rating sits at Hold rather than Buy, and the average price target is essentially level with the current price. In the immediate term, however, there is no denying Thursday's outperformance. The breakout and momentum are real, and, as with AMD, they could signal where the next phase of leadership and capital rotation is headed.
What the Breakouts Say About the AI Trade
AMD and Intel are two of the most important names in the AI-chip space outside of NVIDIA, and their breakouts just as the AI trade steadies suggest that the recent slowdown scare may be giving way to renewed appetite across the sector. Both moved on heavy volume, outperformed the broader market and sector on Thursday, and are riding a wave of optimism about their roles in the next phase of the AI buildout.
But whether this proves to be long-term sector leadership or simply a strong post-FOMC bounce will take time to confirm. When a wobbling trade regains its footing and leadership broadens beyond the single obvious name, it often means the theme may have more room to run. For now, AMD and Intel have put themselves back in the spotlight, and how they follow through from here will say a lot about the AI trade's next chapter.
This email message is a paid sponsorship for Golden Portfolio, a third-party advertiser of MarketBeat. Why did I get this email message?.
If you need help with your newsletter, please contact our U.S. based support team at contact@marketbeat.com.
If you would no longer like to receive promotional emails from MarketBeat advertisers, you can unsubscribe or manage your mailing preferences here.
Copyright 2006-2026 MarketBeat Media, LLC. All rights reserved.
345 North Reid Place #620, Sioux Falls, SD 57103-7078. U.S.A..
-
Having trouble viewing this email? View it as a Web page . You are subscribed to Constit...
-
Plus, Deaths of foreign fighters draw renewed attention to the military volunteers in Ukraine. ...
-
We'll be sending you the latest buy and sell ratings from Wall Street's top analysts, but first,...


